Sooner or later someone in a chat group mentions options, usually in the same breath as the words limited risk, and the question arrives: how to trade in gold options, and is it safer than what I am doing now. It is a fair question and it has a real answer, but the answer is not on the buy side of the screen. It is in the arithmetic of what the contract charges you before you are right about anything.
Here is the short version so nobody has to read three thousand words to understand the shape of it. You pay a fee up front for the right, not the obligation, to trade gold at a fixed price by a fixed date. If gold does not move far enough in your direction before that date, the fee is gone. Your maximum loss is known on the day you buy. So is the fact that the most likely outcome is losing all of it.
The part worth staying for is the other side of the trade, the one where somebody sells you that right. That side has no known maximum loss at all, and it is the side that retail accounts wander into by accident when a platform makes it look like collecting income.
How to Trade in Gold Options, the Mechanical Part
Start with the vocabulary, taken from the regulator rather than from a course, because the definitions are precise and the marketing versions are not. The US Commodity Futures Trading Commission publishes a full glossary of these terms, and it is worth reading in the original.
- The premium is, in the CFTC’s words, “the payment an option buyer makes to the option writer for granting an option contract.” It is paid at the start and it is not refundable.
- The exercise price, also called the strike price, is “the price, specified in the option contract, at which the underlying futures contract, security, or commodity will move from seller to buyer.”
- The expiration date is “the date on which an option contract automatically expires.” After it the contract is worth its intrinsic value, or nothing.
- The option writer is “the person who originates an option contract by promising to perform a certain obligation in return for the price or premium of the option.”
Note the asymmetry in that last definition. The buyer has a right. The writer has a promise to perform.
From those four pieces you get four possible positions. Buy a call, the right to buy gold at the strike, which pays if gold rises far enough. Buy a put, the right to sell at the strike, which pays if gold falls far enough. Or write either of those, collect the premium, and take on the promise.
Where they trade matters more than most beginners realise. Exchange-listed gold options are options on gold futures contracts, cleared by a central counterparty, with published contract sizes and standardised terms. Everything else is a bilateral arrangement with whoever is on the other side of your account, which makes the counterparty part of the risk. Find out which of the two you are being offered before anything else.
The Price of the Ticket, Measured
An option’s price is not arbitrary. You can get close to it with public data and a page of arithmetic, which means you can check whether what you are being quoted is roughly sane before you pay it.
The dominant input is volatility, so start there. Taking the London Bullion Market Association’s published gold benchmark history and measuring the daily variation of the benchmark from January 2000 to September 2026, across 6,674 observations, gold’s realised annualised volatility works out at 17.42 per cent. Over the most recent ten years it was 16.06 per cent, over five years 17.98 per cent, over three years 20.27 per cent, and over the last twelve months 27.66 per cent. The metal has been considerably livelier lately than its own long-run average.
Feeding the long-run 17.42 per cent figure into the standard option pricing formula, with the assumptions written out below, gives the cost of a call as a percentage of the gold price:
- A call struck at today’s price, expiring in 30 days, costs about 1.99 per cent of the gold price. At 90 days, 3.45 per cent. At a year, 6.94 per cent.
- A call struck 5 per cent above today’s price costs about 0.45 per cent at 30 days, 1.58 per cent at 90 days, and 4.89 per cent at a year.
- A call struck 10 per cent above costs about 0.06 per cent at 30 days and 0.62 per cent at 90 days.
The assumptions, stated openly because a number without its assumptions is a decoration: the Black-Scholes formula, a zero interest rate, no storage or lease costs, constant volatility, and price movements that follow a log-normal distribution. Real option markets have none of those things exactly. Real quotes also carry a bid-ask spread, and the far out-of-the-money contracts in the list above have the widest ones relative to their value. Treat these as the shape of the cost, not as a price list.
The Number That Decides Everything
Now combine the two halves, because this is the calculation almost nobody does before buying their first option.
A call only pays at expiry if gold finishes above the strike. But you did not get the strike for free, you paid a premium for it. So the price at which you actually begin to make money is the strike plus the premium, and the move required is both of those added together.
On the 90 day contracts priced above:
- Struck at today’s price: premium 3.45 per cent, so gold must rise 3.45 per cent just to get your money back. Probability of finishing above that, on the same model: 33.17 per cent.
- Struck 3 per cent above: premium 2.20 per cent, so the required rise is 5.20 per cent. Probability: 26.44 per cent.
- Struck 5 per cent above: premium 1.58 per cent, required rise 6.58 per cent. Probability: 21.76 per cent.
- Struck 10 per cent above: premium 0.62 per cent, required rise 10.62 per cent. Probability: 11.31 per cent.
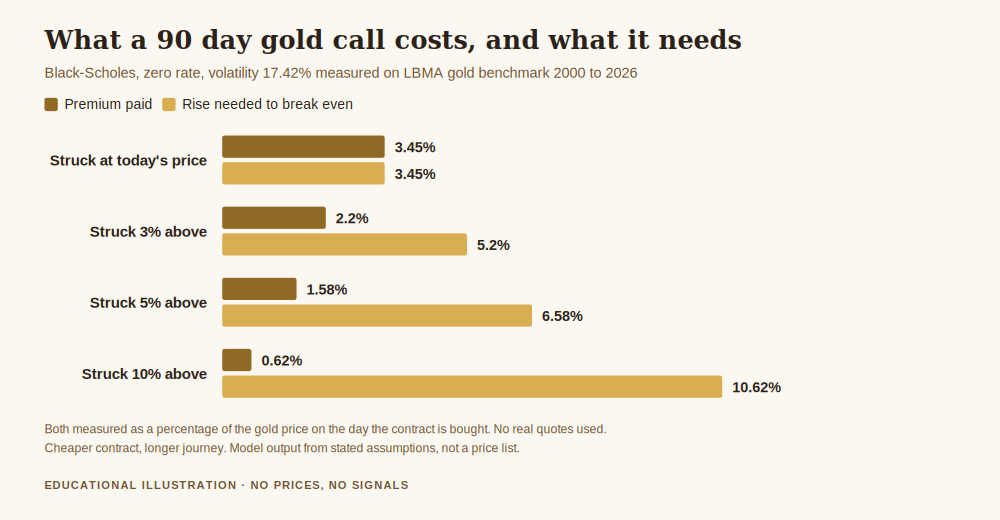
Read the shape rather than the individual numbers. The cheap-looking contracts are cheap because they are unlikely to pay. The far out-of-the-money call, the one usually described as a lottery ticket, costs a tenth as much as the one struck at today’s price and needs three times the move. That is not a bargain, that is the price being approximately right.
Note also what this does to a trader used to spot gold. On a normal position you can be roughly right about direction and slightly wrong about timing and still end up fine. On a bought option you can be exactly right about direction, watch gold rise two per cent, and lose every penny because the contract expired on a Friday and the move happened the following Tuesday.
Time Is the Other Side of the Trade
The CFTC glossary calls it time decay: “the tendency of an option to decline in value as the expiration date approaches, especially if the price of the underlying instrument is exhibiting low volatility.”
Put numbers on it. Take that 90 day call struck at today’s price, and hold gold perfectly still. What is left of your premium as the clock runs?
- With 60 days to go: 81.66 per cent of what you paid.
- With 45 days to go, the halfway point: 70.7 per cent.
- With 30 days to go: 57.75 per cent.
- With 7 days to go: 27.90 per cent.
- With 1 day to go: 10.54 per cent.
Half the calendar gone, roughly seventy per cent of the value left, and then it falls off a cliff. Nothing has to go wrong for that to happen. The market does not have to move against you. Standing still is enough, and standing still is what markets mostly do.
Get the free Gold Empire survival sheet, a one-page guide to protecting your account through exactly the kind of decision this article describes, including how to state your maximum loss in money before you click anything. One email, no spam, unsubscribe anytime.
The Side That Can Take More Than You Put Up
Everything above is the buyer’s side, where the worst case is losing the premium. Now the other side, because this is where accounts actually die.
The CFTC defines a naked option as “the sale of a call or put option without holding an equal and opposite position in the underlying instrument.” You collect the premium up front. In exchange you have promised to perform, and if gold runs, your obligation grows with it, without a ceiling.
Here is that in numbers, using the same model and the same public price history. Sell a 30 day call struck 5 per cent above the market and you collect about 0.45 per cent of the gold price. Now look at what gold has actually done. Across every 30 calendar day window from 2000 to September 2026, the largest rise was 23.75 per cent, from 30 December 2025 to 29 January 2026, with 22.26 per cent in 2006 and 21.57 per cent during September and October 2008 close behind.
Meet the biggest of those while short that call and you owe 18.75 per cent of the gold price against the 0.45 per cent you collected. That is 42.1 times your income on a single contract, and it did not happen in the distant past. It happened this year.
And it is not a freak. Of all 6,679 thirty day windows in the sample, 18.16 per cent saw gold rise more than 5 per cent. Nearly one in five. The strategy that looks like collecting rent works most of the time, which is precisely why people scale it up, and then one window in the tail removes more than every premium collected before it.
If you take nothing else from this article, take this: buying an option and writing one are not two variations of the same trade. They are opposite risk shapes wearing the same name. A platform that offers both behind the same button is not doing you a favour.
What This Does Not Say
It does not quote a price for any gold option. Every figure here is a model output from stated assumptions, produced to show the shape of the cost, and real quotes will differ, sometimes materially.
It does not say the model is right. Black-Scholes with constant volatility and zero rates is a simplification. Real markets price a volatility skew, real gold has fatter tails than the log-normal distribution, and those fat tails make the sold-option case worse than the arithmetic above, not better. Where the model is wrong, it is wrong in the direction of understating the danger of writing.
It does not predict anything, and it does not tell you to trade options or not to. Measuring the last twenty-six years describes the past, and the 23.75 per cent window is a reminder that the historical maximum was set recently rather than a forecast. What this article gives you is what the contract charges before you are right, which is information you are entitled to have before you decide.
Five Questions to Answer Before You Trade a Gold Option
None of these are about direction. They are the questions that decide whether a loss is survivable.
- Is it exchange-listed and centrally cleared, or is my counterparty the firm holding my money? If it is the second, the counterparty is part of the risk.
- What is one contract worth in my currency? Not in per cent, in money. If you cannot state the figure, you cannot size the position.
- What is the bid-ask spread as a share of the premium? On a contract costing 0.62 per cent of the gold price, a spread worth a tenth of the premium is a large cost before anything else happens.
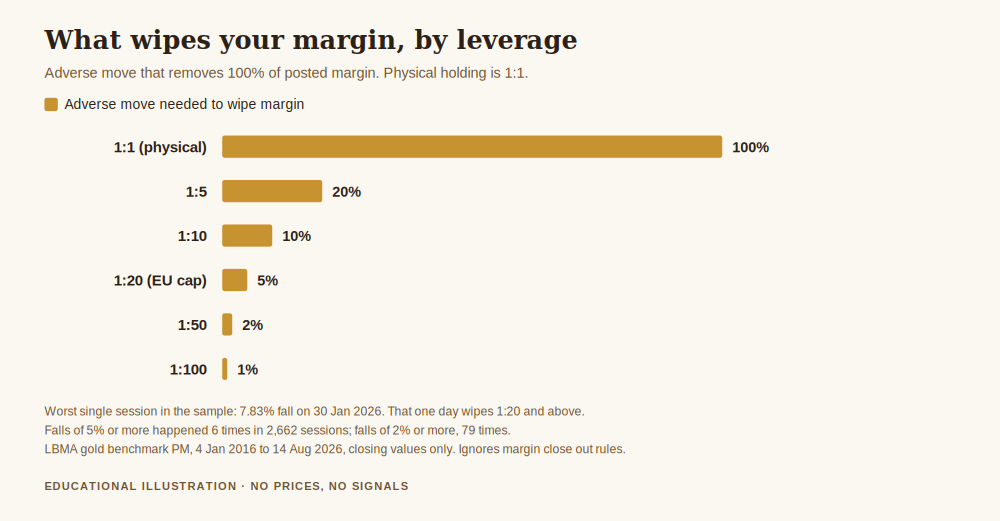
- Am I buying or writing, and what is my maximum loss? If you are writing, there is no maximum, and you need to know how your broker will close you out. Leverage in gold trading covers why that close-out arrives sooner than people expect.
- Does this instrument fix a problem I actually have? Accounts rarely blow up for lack of a second instrument. They do so for the reasons in why you keep blowing your trading account, none of which are solved by adding complexity.
Frequently Asked Questions
How to trade in gold options as a complete beginner?
The honest answer is that this is the wrong first instrument. An option adds a second variable, time, to a trade you are already trying to get right on direction and size. If direction and size are not yet reliable, adding a clock does not help.
Are gold options safer than spot gold or CFDs?
A bought option has a known maximum loss, which is genuinely different from a leveraged spot position. A written option has no maximum loss at all. So the instrument is not safer or riskier; the side you take is what decides that.
Why did my option lose money when gold went my way?
Almost always time decay, sometimes a fall in priced volatility. Gold has to move far enough, and soon enough. The 90 day at-the-money contract above needs a 3.45 per cent rise simply to return the premium.
Is selling options a reliable income strategy?
It produces small regular receipts and rare very large payments out. On this data, 18.16 per cent of 30 day windows saw gold rise more than 5 per cent, and the worst rose 23.75 per cent, which is 42.1 times the premium a 5 per cent out-of-the-money writer would have collected. Frequency of winning is not the same as expectancy.
Where did the numbers in this article come from?
Volatility, the 30 day windows and the historical maximum rise were calculated from the published LBMA gold auction history linked below, downloaded before publication. Premiums, break-even moves, probabilities and decay were computed with the Black-Scholes formula under the assumptions stated in the text. The definitions are quoted from the CFTC glossary linked above. None of it is a price quote, a forecast or a performance claim.
Where Gold Empire Fits
Gold Empire is free to follow. Daily XAU/USD analysis on Telegram, with the reasoning stated before the trade rather than after it, losing days included. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the full method. Nothing here promises a profit and nothing here is a signal service.
A new instrument is a risk decision before it is anything else. Risk management for gold trading is the pillar this article sits under, how much to risk per trade is the arithmetic that decides whether any of this is survivable, and the difference between gold and gold futures covers the instrument these options are usually written on. The price history comes from the London Bullion Market Association price record. More about who writes this is on the about page.
About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He has watched more than one trader discover that the side of an option trade they were on was not the side they thought. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.
Disclaimer: This article is general educational content about derivative instruments, option pricing mechanics and risk in retail trading. It is not financial advice, not investment advice and not a recommendation to buy, sell, write or use any product, contract, platform or firm. Availability of gold options, contract specifications, tax treatment and regulatory protections vary by jurisdiction and change over time, and current terms should be checked with your own broker and with the sources linked in the text. Options can expire worthless and writing options can produce losses greater than the premium received and greater than the capital in the account. Trading leveraged products carries a substantial risk of loss and most retail accounts lose money. Figures are calculations from the stated public data and stated assumptions, not predictions or performance claims.
One step first
Where should we send the Gold Survival Sheet?
Leave your email and we will send the free one page checklist, then take you straight to the Telegram channel.
No cost and no obligation. Educational only, not financial advice, and nothing here promises a return. Unsubscribe any time in one click.