GOLD EMPIRESurvive First, Then Grow

Category: Tools & Brokers

  • What Is an ECN Broker, and Does the Label Change Who Takes the Other Side

    What Is an ECN Broker, and Does the Label Change Who Takes the Other Side

    Someone in the community sent me two broker adverts last week and asked which one to open with. Both used the same three letters in the headline. He wanted to know what is an ecn broker, whether it was better than what he had, and whether switching would stop the bleeding in his account.

    I want to answer the first part properly, because the term has a real technical meaning and it is worth knowing. Then I want to show you the arithmetic on the second part, because I have watched a lot of people change broker looking for a fix and arrive at the new one with exactly the same problem.

    What is an ecn broker, in the original sense

    ECN stands for Electronic Communication Network. It came out of the equity markets, and it described something specific: a system that matched buy and sell orders from many participants directly against each other, displayed the resulting book, and charged a fee for the match rather than making money on the difference between the two prices.

    The important word in that description is match. In a true ECN, the venue is not the other side of your trade. It is a place where your order meets somebody else’s. If you buy, another participant sold. The venue took a fee and went home flat, not caring at all which way the price went afterwards.

    Set against that is the dealer model. You click buy, and the firm you clicked with sells to you. It is your counterparty. It now holds a position, and it either hedges that position somewhere else or it holds the risk itself. Its revenue is the difference between the price it showed you and the price it can get elsewhere, plus whatever your position does.

    Those are genuinely different arrangements and it is reasonable to want to know which one you are in. The problem is what happened to the label on the way to the retail advertising department.

    The label is not a regulated category, and here is the proof

    This is the part almost nobody checks, and it took me one page of a regulator’s website to find.

    The US Commodity Futures Trading Commission wrote the rulebook for off-exchange retail foreign exchange after Dodd-Frank. Its Foreign Currency Trading page sets out what that rulebook requires, and the relevant sentence is this: the regulations “require the registration of counterparties offering retail foreign currency contracts as either futures commission merchants (FCMs) or retail foreign exchange dealers (RFEDs), a new category of registrant.”

    Read the word the regulator chose. Counterparties. Not venues, not networks, not matching engines. In the eyes of the rulebook governing retail forex in the United States, the firm offering you the contract is the other side of it, and the category it must register under is literally called a dealer.

    There is no ECN category in that list. Not because ECNs are banned, but because what is being offered to a retail client is not a match on a venue, it is a contract with a firm.

    Two more numbers from the same page, and they are worth having. The final rules were published on 10 September 2010 at 75 Fed. Reg. 55410, effective 18 October 2010. And the capital requirement is specific: FCMs and RFEDs “are required to maintain net capital of $20 million plus 5 percent of the amount, if any, by which liabilities to retail forex customers exceed $10 million.”

    Twenty million dollars, before a single client deposits. That figure tells you more about the business you are dealing with than any three letter label. It exists because the regulator concluded the firm is carrying your risk and must be solvent enough to honour it.

    What the label usually means in practice

    None of this makes the word meaningless. When a retail broker advertises an ECN or raw spread account, it is normally signalling three real things, and they are worth understanding on their own terms rather than as a brand.

    • A different pricing structure. Tighter quoted spread, plus an explicit commission per round turn, instead of a wider spread and no visible commission. This is a cost question, and it is the whole subject of a separate article, what is an ECN account, which takes the same three letters from the account side, works through the US equity market definition at 17 CFR 242.600, and does the spread against commission sum. This article is about the firm and who is on the other side. That one is about the account and what it costs you.
    • Aggregated pricing. The quote is built from several liquidity providers rather than one internal desk. That usually does mean a tighter and more competitive price.
    • An intention to hedge rather than warehouse. The firm is telling you it expects to pass your risk on rather than sit against it.

    Every one of those is a genuine thing a broker might do. What none of them is, is a regulated guarantee. A firm can hedge one client’s flow and hold another’s, and switch which is which based on how the client is doing. That practice has a name in the industry and it is entirely legal and disclosed in the terms you agreed to. The label on the account does not decide it.

    Now the arithmetic, which is why I am not excited about the label

    Here is the calculation that changed how I think about this, and you can check every step.

    Take an account with no edge at all. Not a bad trader, not an emotional one. A perfectly disciplined account whose trades are a fair coin flip: 200 trades in a year, each one either winning exactly one unit of risk or losing exactly one unit of risk, with equal probability. Then subtract a fixed cost per round turn, expressed in those same units.

    This is exact binomial arithmetic, not a simulation, so there is no seed and no sampling error. The question is: what share of those accounts finish the year in profit?
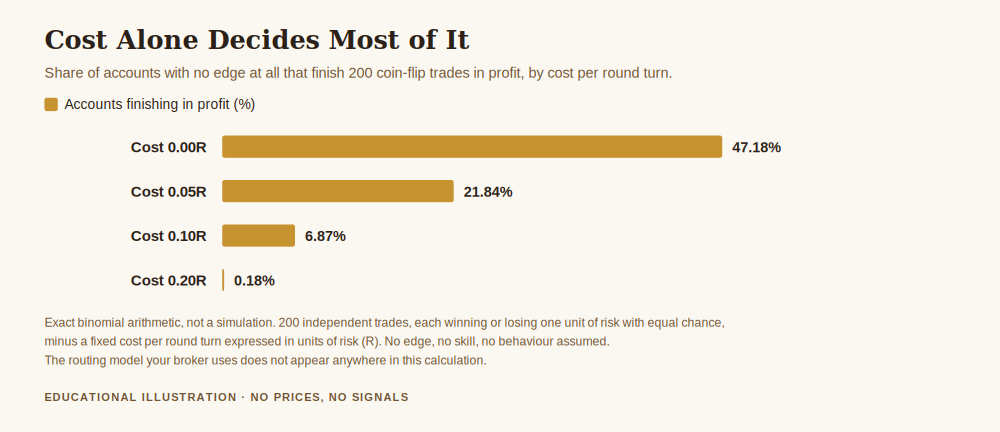
    What is an ecn broker, chart showing the share of accounts with no edge that finish two hundred trades in profit at four different cost levels per round turn
    What is an ecn broker worth to you, answered sideways: the share of no-edge accounts finishing 200 trades in profit, by cost per round turn. The routing model does not appear in this calculation.
    • At zero cost, 47.18 per cent finish in profit. Not fifty, because with an even number of trades a good many land exactly at break even.
    • At 0.05R per round turn, it falls to 21.84 per cent.
    • At 0.10R, it falls to 6.87 per cent.
    • At 0.20R, it falls to 0.18 per cent. Roughly one account in five hundred and fifty.

    Read those four numbers again, because they are the whole article. Nothing changed between them except the cost per trade. No psychology, no revenge trading, no bad entries, no leverage, no news event. Cost alone took a group of accounts from a near coin flip to a near certainty of loss.

    And now hold that against what the European Securities and Markets Authority found when it looked at real accounts. In the announcement of its measures on binary options and CFDs, ESMA reported that national regulators’ analyses “shows that 74-89% of retail accounts typically lose money on their investments, with average losses per client ranging from €1,600 to €29,000.”

    Between 74 and 89 per cent losing. My no-edge accounts at 0.05R cost lose 78.2 per cent of the time. At 0.10R they lose 93.1 per cent of the time. The regulator’s observed range sits almost exactly where friction alone would put it.

    I want to be careful about what I am claiming. I am not saying costs are the only reason retail accounts lose, and I cannot prove that from this. Real traders are not coin flips, some have an edge and some have habits far worse than random. What I am saying is narrower and I think more useful: you do not need to assume anybody behaved badly to reproduce the regulator’s numbers. Ordinary friction, applied to an account with no advantage, gets you there on its own.

    What this means for the question you actually asked

    So, should you move to an ECN account? Here is how I would order it, and notice that the label comes last.

    First, the break-even win rate. On a 1:1 payoff, cost 0.05R per round turn means you must win 52.5 per cent of the time to break even. At 0.10R it is 55.0 per cent. At 0.20R it is 60.0 per cent. Those are the hurdles your method has to clear before it produces anything at all. Work out yours before you compare any two accounts, because it tells you how much a cost saving is worth to you specifically.

    Second, trade count. Every figure above scales with the number of round turns. Two hundred trades a year at 0.10R is a 20R drag. Cut to fifty trades and the same cost per trade is a 5R drag. For most people the largest available reduction in friction is not the account type, it is the number of times they click.

    Third, solvency and regulation. The twenty million dollar figure above is the kind of thing worth checking. Is the firm registered, where, and what does that regime actually require of it. That question matters far more than routing when something goes wrong.

    Fourth, and only fourth, the cost structure. Raw spread plus commission against an all-in wider spread. This is arithmetic you can do in ten minutes for your own trade count, and it is a real saving when it goes your way, and it is usually smaller than people expect.

    The gentleman who wrote to me was trading roughly eight times a week. Moving accounts might have shaved a fraction of a unit of risk off each round turn. Halving his trade count would have done several times more, cost him nothing, and required no paperwork at all.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account from the kind of slow friction this article describes, before it becomes the reason you quit. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    So what is an ecn broker, in one sentence?
    Strictly, a venue that matches your order against another participant’s and charges a fee for the match rather than earning the spread. In retail forex advertising it usually means an account with a tight raw spread, a separate commission and aggregated pricing from several liquidity providers. Those are two different statements and the marketing rarely separates them.

    Is an ECN account safer than a dealing desk account?
    Safety comes from regulation, segregation of client money and the firm’s capital, not from routing. The CFTC page above requires registered counterparties to hold net capital of $20 million plus 5 per cent of retail liabilities above $10 million, and that requirement applies to the firm regardless of what its account types are called. Check the registration and the regime. The label tells you about pricing, not about what happens if the firm fails.

    Does an ECN account mean my broker cannot trade against me?
    No, and I would treat any firm that claims otherwise with caution. Under the US rules the firm offering the contract is registered as a counterparty, which is what the word dealer means. Whether it hedges your particular flow in the market or holds it internally is an operational decision described in your terms, and it can differ between clients and change over time. The account label does not control it.

    Will switching to a lower cost account fix a losing account?
    It helps, and the numbers above show exactly how much it can help, but look at the direction of the effect. Going from 0.10R to 0.05R per round turn moves a no-edge account from a 6.87 per cent chance of a profitable year to 21.84 per cent. That is a real improvement and still a losing proposition, because cost reduction does not manufacture an edge. It makes an existing edge survive. If there is no edge to protect, a cheaper account only slows down the same outcome.

    Where do the percentages in the chart come from?
    They are my own exact binomial arithmetic, computed in Python and reproducible with a pocket calculator and patience. 200 independent trades, each winning or losing one unit of risk with probability one half, minus a fixed cost per round turn in the same units. An account finishes in profit when wins minus losses exceed total costs. No behaviour, skill, leverage or market condition is modelled, which is the entire point: these are the numbers before anything human happens.

    What are the limits of that calculation?
    Several, and I would rather state them than have you find them. Real trades are not 1:1 payoffs and not independent. Real costs vary with volatility, time of day and how the order fills. Real traders are not coin flips. And a 200 trade year is one choice of many. The calculation is not a model of you, it is a floor: it shows what cost does before anything else is added, and everything else is added on top of it.

    Does Gold Empire recommend a particular broker?
    There are broker articles on this site and some carry partner links, which are always disclosed on the page itself. Nothing here, including this article, is a recommendation to open any particular account, and the arithmetic above is deliberately the sort that no broker’s marketing department would commission.

    What Gold Empire actually does

    Gold Empire is a free resource for people trying to survive their first years in gold rather than get rich in them. The articles are free, the daily analysis on Telegram is free, and the Gold Survival Sheet is free. There is no profit promise anywhere on this site and there never will be, because the arithmetic in this article is precisely why nobody can make one honestly.

    If cost is the thread you want to pull, raw spread account vs standard account does the full comparison with your own trade count, and what is the spread in gold trading covers the first cost every trade pays. The article underneath all of them is risk management in gold trading, and if you are choosing a firm rather than an account type, best broker for gold trading is the one to read.

    About the author. Matthew writes Gold Empire. He changed broker three times early on looking for the thing that was wrong, and the thing that was wrong turned out to be how often he was clicking. Nothing in this article is financial advice or a recommendation to open any account, and no entry, stop or target discussed should be treated as a signal.


  • Best Forex Telegram Channel for Forex Signals: How to Judge One Before You Trust It

    Best Forex Telegram Channel for Forex Signals: How to Judge One Before You Trust It

    Search for the best forex telegram channel for forex signals and you will get lists. Ranked lists, “top ten” lists, lists with star ratings and affiliate links underneath them. What you will almost never get is the one thing that would actually help you, which is a method for telling a good channel from a lucky one using nothing but arithmetic you can do yourself.

    That is what this article is. I run a channel, so read everything below with that in mind, and then apply the same test to mine. If it does not survive the test, you should not follow it either. That is the only honest way I know to write this piece.

    Why the Usual Way of Picking the Best Forex Telegram Channel for Forex Signals Fails

    Here is the normal process. Someone joins three or four channels, watches them for a fortnight, notices that one of them called several moves correctly, and stays with that one. It feels like evidence. It feels like due diligence, even, because you watched rather than just believing a screenshot.

    The problem is that a fortnight of correct calls is exactly what luck looks like. Not sometimes. Routinely. And the arithmetic that shows this is simple enough to do in your head once you have seen it done once.

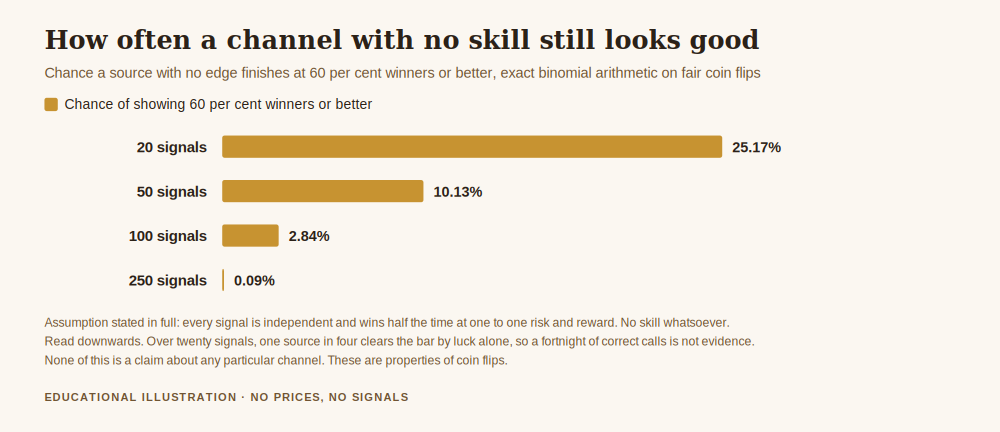
    Take a channel with no skill at all. Not a fraud, just someone with no genuine edge, whose calls are effectively coin flips at one to one risk and reward. Ask how often that channel finishes a run of signals looking impressive.

    • Over 20 signals, a pure coin flipper finishes at 60 per cent winners or better 25.17 per cent of the time.
    • Over 50 signals, 10.13 per cent of the time.
    • Over 100 signals, 2.84 per cent of the time.
    • Over 250 signals, 0.09 per cent of the time.

    Those are exact binomial probabilities, not estimates from a simulation. One in four channels with zero skill will show you a 60 per cent hit rate over twenty calls. If you are comparing four channels over a fortnight, you should expect one of them to look good. The impressive one is not the outlier. It is the arithmetic working normally.

    Chart for choosing the best forex telegram channel for forex signals, showing how often a channel with no skill at all still finishes above sixty per cent winners across twenty, fifty, one hundred and two hundred and fifty signals
    Choosing the best forex telegram channel for forex signals from a short record is guesswork: a channel with no skill whatsoever clears 60 per cent winners a quarter of the time over twenty signals.

    The Streak Screenshot, Explained

    The other thing you will be shown is a streak. Eight winners in a row, twelve winners in a row, posted as a screenshot with the losses cropped out.

    Run the same arithmetic. In 50 coin flips, the chance of at least one run of eight consecutive winners somewhere in there is 8.36 per cent. In 100 flips it is 17.02 per cent. In 250 flips it is 38.40 per cent. So a channel that has been posting for a year, with no skill at all, is more likely than not to have produced at least one eight winner streak it can screenshot forever.

    This is the part I want you to take away even if you remember nothing else. A streak is not evidence of skill, because a long enough record produces streaks by accident. The only thing a streak proves is that the channel has been posting for a while.

    How Much Evidence Would Actually Be Enough

    Turn the question around. Suppose a channel genuinely does win 60 per cent of the time. How many signals do you need to see before that result separates itself from luck?

    Working it the other way, at a one sided five per cent threshold, you need 62 signals. At that point a channel showing 38 wins out of 62 has produced something a coin flipper manages only 4.90 per cent of the time. Below 62 signals, you genuinely cannot tell the difference, and no amount of confidence in the presentation changes that.

    Sixty two is the floor, and it assumes the record is complete. It assumes nothing was deleted. In practice, a deleted losing call is worth far more than a posted winning one, because it corrupts the entire sample. So the real requirement is sixty plus signals in a record you have reason to believe is complete, which is a much harder thing to find.

    The Four Questions That Actually Separate Channels

    Since the track record is mostly unreadable, judge the process instead. These are the four things I would check, in order.

    One. Is the reasoning posted before the outcome, or after it? This is the single most informative signal available to you, and it costs nothing to check. Scroll back six months. Does each call state a reason at the time it was made, or do explanations only appear once the market has moved? Hindsight commentary is free to produce and worth nothing. A channel that commits to a reason in advance is making itself falsifiable, which is the entire game.

    Two. Are the losses still there? Scroll for losing days specifically. If you cannot find any, that is not a good channel, it is an edited one. Every genuine record has bad weeks in it. A channel that posts its worst month is telling you something a channel that posts its best month never can.

    Three. Is there a number attached to the risk? Look at whether calls mention position size, invalidation, or what happens when the idea is wrong. A channel that only ever posts direction is not giving you a trade, it is giving you an opinion with a ticker attached. The thing that decides whether your account survives is not the direction, it is how much you had on, which is the whole reason I keep pointing people back to how much to risk per trade before anything else.

    Four. What is the business model? Somebody is paying for the channel to exist. If it is you, through a subscription, then the incentive is to keep you subscribed, which rewards excitement. If it is a broker, through a referral fee per lot you trade, then the incentive is volume, which rewards overtrading. Neither is automatically disqualifying, but you are entitled to know which one you are in, and a channel that will not say is answering the question anyway.

    The Regulatory Numbers Nobody Puts in the Ranked Lists

    Two published figures put the rest of this in context, and both come from public bodies rather than from anyone selling anything.

    The first is the scale of the loss. The FBI’s Internet Crime Complaint Center publishes an annual report, and its 2024 Internet Crime Report records 47,919 complaints in the investment category, with reported losses of 6,570,639,864 US dollars in that category alone, against 16.6 billion dollars of reported losses across all categories that year. Investment fraud is not a fringe risk in this space. It is the largest single category of reported loss in the report.

    The second is more useful still, because it tells you what the honest baseline looks like. When the European Securities and Markets Authority restricted contracts for difference sold to retail clients, one of the measures it imposed was a standardised risk warning, including the percentage of losses on a CFD provider’s retail investor accounts. The same package capped leverage on gold at 20 to 1 and required negative balance protection on a per account basis.

    Read that second one slowly. A regulator looked at this market and concluded that the single most useful thing a retail client could be told was what share of accounts lose money. Not which strategy works. Not which channel is best. What share of accounts lose money. If a signal channel has never once mentioned that most retail accounts lose money, it is presenting a version of this business that a regulator specifically legislated against.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting an account before you follow anyone’s analysis, including the questions worth asking of any channel you join. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    The Mistake That Costs More Than Picking Wrong

    Here is the thing I have seen do the most damage, and it has nothing to do with which channel someone picked.

    People size their positions based on how much they trust the source. A call from a channel they rate highly gets three times the risk of a call from a channel they are still evaluating. It feels rational. It is the single fastest way I know to turn an ordinary losing streak into a closed account, because the losing streak arrives regardless of how good the analysis was, and it arrives exactly when confidence is highest, which is after the run of winners that earned the trust in the first place.

    Position size is a decision about your account. It is not a vote of confidence in someone else’s analysis. Those are two different things and merging them is how people who followed perfectly reasonable channels still ended up blown out, which is the pattern behind why accounts keep getting blown up even when the analysis was fine.

    The right structure is boring. Decide your risk per trade before you open Telegram. Apply it identically to every idea regardless of who posted it. Let the source affect whether you take the trade, never how much you put on it.

    What a Channel Can Honestly Offer You

    Nobody can hand you a shortcut past your own decision making, and any channel implying otherwise is selling something. What a channel can genuinely do is narrower and more useful than that.

    It can show you a process being applied consistently, so you can learn the shape of it. It can point out context you would have missed, like a data release you had not checked. It can give you a second opinion that is not your own anxiety talking. And it can model what it looks like to sit out, which is the hardest habit in this business to learn alone.

    What it cannot do is make a bad position size safe, and it cannot make you a trader by proxy. The account is yours. The decision is yours. That does not change no matter how good the analysis is.

    Frequently Asked Questions

    How do I find the best forex telegram channel for forex signals?
    Judge process, not results. Check four things: whether the reasoning is posted before the outcome, whether losing calls are still visible in the history, whether risk and invalidation are stated alongside direction, and how the channel makes money. A short run of correct calls tells you almost nothing, because a channel with no skill at all clears 60 per cent winners a quarter of the time over twenty signals.

    How many signals do I need to see before I can judge a channel?
    At least 62, and only if you believe the record is complete. Below that number, a genuine 60 per cent hit rate cannot be separated from luck at a one sided five per cent threshold. Most people decide after ten or twenty, which is well inside the range where coin flips look like skill.

    A channel showed me eight winners in a row. Is that good?
    It is unremarkable. In 100 coin flips the chance of at least one run of eight consecutive winners is 17.02 per cent, and in 250 flips it is 38.40 per cent. Any channel that has been posting for a year has probably produced one by accident. Ask to see the month either side of the streak instead.

    Are paid signal channels better than free ones?
    Price tells you about the business model, not the quality. A subscription means the incentive is to keep you subscribed. A broker referral fee means the incentive is the volume you trade. Free with no funnel at all usually means the channel is marketing for something else. None of these is disqualifying, but you should know which one applies before you join, and be wary of any model that pays more when you trade more.

    Where did the probabilities in this article come from?
    Exact binomial arithmetic, computed rather than estimated, on the stated assumption that a channel with no edge produces independent signals that win half the time at one to one risk and reward. The streak figures come from an exact dynamic programming calculation over the same assumption. Anyone can reproduce all of them. They are properties of coin flips, not claims about any particular channel.

    Where Gold Empire Fits

    Gold Empire is free to follow, and I would rather you applied the test above to it than took my word for anything. Daily XAU/USD analysis goes out on Telegram with the reasoning stated before the trade rather than after it, and the losing days stay up. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the whole method. Nothing here promises a profit, and nothing here is a signal service in the sense that phrase usually means.

    If you are working through this properly, the pillar underneath all of it is risk management for gold trading. The companion piece on whether these groups are legitimate at all is are forex signal groups legit, and the practical mechanics of using one without handing over your judgement are in how to get signals for forex trading.

    Looking for the best forex telegram channel for forex signals is a reasonable thing to do. Just do it with arithmetic rather than with screenshots, and remember that the number which decides your outcome is the one you choose, not the one someone else posts.

    About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He has been keeping a count of his own losing calls for long enough to know exactly how ordinary a good fortnight is. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about evaluating information sources and about probability. It is not financial advice, not investment advice and not a recommendation to buy, sell or hold any instrument or product, nor an endorsement of any channel or provider. Trading gold and leveraged products carries a substantial risk of loss and is not suitable for everyone. Most retail accounts lose money. Past results of any source do not guarantee future results. Only risk capital you can afford to lose, and seek independent advice if you are unsure.


  • How to See Gold Chart in TradingView, and Which Gold It Shows

    How to See Gold Chart in TradingView, and Which Gold It Shows

    Most people asking how to see gold chart in TradingView want a two minute answer, and there is one. Type XAUUSD into the symbol box, press enter, and a chart appears. Done. The trouble is that the chart which appears is one of several different gold charts the platform can show you, they do not all say the same thing, and almost nobody checks which one they landed on.

    That sounds pedantic until you realise what it costs. You size a position using the volatility you see on the screen, but you get filled on a feed that belongs to your broker, and if those two are not the same thing, your risk calculation was built on someone else’s data. So I want to cover the two minute answer properly, and then spend the rest of this on the part that actually protects an account.

    How to See Gold Chart in TradingView, Step by Step

    Open the platform and click the symbol box at the top left, where the current instrument name sits. Type gold, or XAUUSD, and wait for the dropdown to populate.

    Here is the first thing worth noticing. You will not get one result. You will get a list, and each entry has a small provider name attached to it on the right hand side. Some of those entries are spot gold quotes contributed by different liquidity providers. Some are futures contracts with expiry months attached. Some are contracts for difference offered by individual brokers. Some are gold priced in other currencies entirely.

    Pick one and the chart loads. To keep it, click the star to add it to a watchlist, then set the timeframe from the toolbar. That is the mechanical answer, and if that is all you came for, you now have a gold chart.

    But scroll that dropdown list again before you move on, because the length of it is the actual lesson. There is no single instrument called gold. There is a family of related instruments, and knowing which branch of that family you are looking at is the difference between analysis and guesswork.

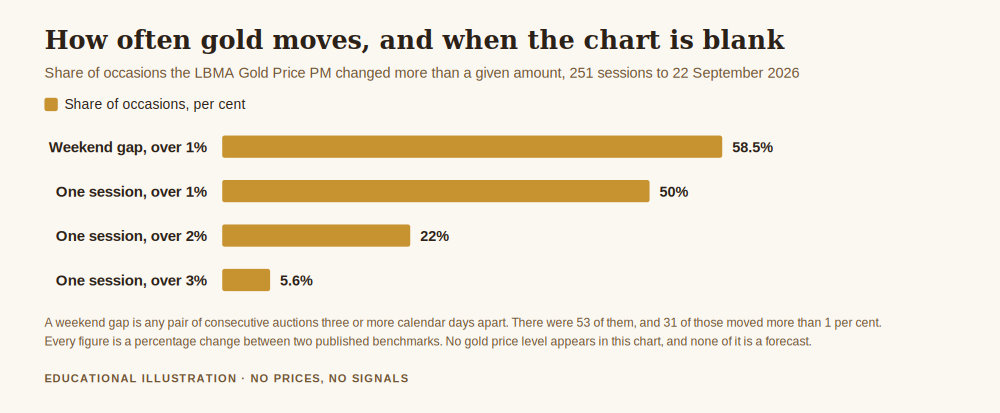
    Chart supporting how to see gold chart in TradingView, showing how often the LBMA gold benchmark moved more than one, two and three per cent between sessions and across weekend gaps
    Once you know how to see gold chart in TradingView, the next question is what the chart does not draw: the weekend gap is the likeliest stretch of all to move more than one per cent.

    The Three Different Golds You Might Be Looking At

    Spot gold is a quote for metal for immediate settlement, traded over the counter between large institutions rather than on an exchange. When a platform shows XAUUSD without a broker name attached, it is usually an aggregate of contributed quotes. It has no expiry and no central order book, which means there is no single authoritative version of it. Two providers can show slightly different spot gold at the same instant and neither is wrong.

    Gold futures are exchange traded contracts for delivery at a set date. The US Commodity Futures Trading Commission’s weekly Commitments of Traders report for the COMEX division lists the benchmark gold contract under code 088691, and states its unit in capitals directly under the column headings: contracts of 100 troy ounces. A futures chart trades at a different level from spot because it carries the cost of holding metal to the delivery date, and that difference narrows as expiry approaches. A futures chart is not a spot chart with a different skin.

    Your broker’s CFD is a third thing again. It is priced off the first two, with your broker’s own spread applied, and possibly a financing charge for holding it overnight. This is almost certainly what you are actually trading, and it is the only one of the three that determines what price you get filled at.

    There is a fourth reference that is not a chart at all but is worth knowing about, because it is what the industry settles against. The London Bullion Market Association runs an auction that produces a published benchmark twice each trading day, and those LBMA precious metal prices are used for valuation and settlement worldwide. Two fixed prints per day, not a continuous line.

    Why the Chart You Choose Has to Match the Account You Trade

    This is the survival point, and it is simple enough to state in one sentence: analyse on the instrument you trade, or accept that your levels are approximations.

    If you mark a level on an aggregated spot chart and place an order on your broker’s CFD, the two are near each other but not identical. Most of the time the difference is small enough to ignore. The times it is not small are precisely the times it matters most, which is at the week’s open, around major data releases, and in thin liquidity, exactly when a stop is most likely to be tested.

    The practical fix takes one minute. If your broker publishes a feed on the platform, chart that. If it does not, chart the closest available and know that you are working with a proxy. Either way, place the order on your platform and look at the fill you actually received rather than the price you expected. Keeping a record of that difference is one of the cheapest habits in this business, and it is part of what I mean by tracking your trades properly.

    What the Chart Does Not Draw

    Here is the part that does not show up in any tutorial, and it is the reason for the chart above.

    A gold chart looks continuous. It is not. The market closes for the weekend, and during that closure the world keeps happening. To put a size on what that means, I took the LBMA Gold Price PM benchmark, which is a published reference rather than any broker’s feed, over the twelve months to 22 September 2026. There were 251 auction sessions in that period, and 250 session to session changes to measure.

    • The median absolute change between consecutive sessions was 1.00 per cent, and the mean was 1.29 per cent.
    • 125 of the 250 changes, exactly 50.0 per cent, exceeded 1 per cent.
    • 55 of them, 22.0 per cent, exceeded 2 per cent.
    • 14 of them, 5.6 per cent, exceeded 3 per cent. The largest single change was 7.83 per cent.

    Now isolate the weekend. I counted every pair of consecutive auctions three or more calendar days apart, which captures weekends and holiday closures. There were 53 of them. Their median absolute change was 1.14 per cent, slightly larger than an ordinary session, and 31 of the 53 exceeded 1 per cent, which is 58.5 per cent of them against 50.0 per cent for sessions generally. The largest weekend change was 5.36 per cent.

    Read that back. The stretch your chart draws nothing at all for is, on this evidence, marginally more likely to produce a move above 1 per cent than a normal trading day. The blank space is not quiet. It is unobserved, which is a very different thing, and it is why I keep coming back to what a weekend gap does whenever someone tells me their stop protects them at all times.

    These are percentage changes in a published benchmark. They are not a forecast, and no gold price appears anywhere in this article.

    Chart Settings That Reduce Mistakes

    A few small things, each of which has caused someone a bad morning.

    Set your timezone deliberately. TradingView defaults to a timezone that may not match your broker’s server, and gold trades in distinct session patterns. A daily candle that closes at a different hour than your broker’s is a different candle, with a different high and a different low, which means a different level.

    Check whether the symbol shows extended or continuous hours, especially on futures contracts, because a chart that hides part of the day will hide part of the range with it.

    Beware the continuous futures contract, usually written with a 1! suffix. It stitches successive contract months into one line, which is convenient for looking at long history and misleading for precise levels, because the join between two contracts is a step that no trade ever printed.

    Finally, and this is the boring one that matters most, put the instrument name somewhere you will actually see it. Screenshot a level from one chart, come back two hours later on a different symbol, and you have a level from an instrument you are not trading, which is how people end up defending a line that was never there.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to working out what a position actually exposes you to before you take it, including the gap you cannot see on the chart. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently Asked Questions

    How do I see gold chart in TradingView in the fastest way?
    Click the symbol box at the top left, type XAUUSD, and choose from the dropdown. The chart loads immediately. The part worth an extra thirty seconds is checking the provider name next to the entry you picked, because the list contains spot quotes, futures contracts and individual brokers’ CFDs, and they do not all show identical prices.

    Which gold symbol should I actually use?
    The one closest to what you trade. If your broker publishes its own feed on the platform, use that, because it is the price you will be filled at. If not, an aggregated spot quote is a reasonable proxy, but treat your marked levels as approximate and confirm the fill on your own platform before drawing conclusions.

    Why does my TradingView gold chart differ from my broker’s?
    Because they are different instruments. Spot gold is an over the counter aggregate with no central order book, futures carry the cost of holding metal to a delivery date, and a broker CFD adds its own spread on top. Small differences are normal. They widen when liquidity is thin, which tends to be when it matters most.

    Is TradingView’s gold data good enough to trade from?
    For analysis, yes, provided you know which instrument you selected. For execution, your broker’s price is the only one that pays you. Treat the chart as the map and your platform as the road.

    Where did the numbers in this article come from?
    From the LBMA Gold Price PM benchmark series, linked above, over the twelve months to 22 September 2026: 251 auction sessions and 250 session to session changes. The percentages are counts of those changes exceeding each threshold, arithmetic anyone can repeat on the same public series. The weekend figures count the 53 pairs of consecutive auctions three or more calendar days apart. None of it is a forecast.

    Where Gold Empire Fits

    Gold Empire is free to follow. Daily XAU/USD analysis on Telegram, with the reasoning stated before the trade rather than after it, losing days included. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the whole method. Nothing here promises a profit, and nothing here is a signal service.

    The pillar this sits under is risk management for gold trading, the settings companion is best chart settings for TradingView, and if you are weighing up which platform to analyse on at all, TradingView vs MetaTrader covers that comparison.

    Knowing how to see gold chart in TradingView takes a minute. Knowing which gold you are looking at, and what the chart leaves out, is the part that keeps an account open.

    About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He has a long standing habit of checking which instrument a screenshot came from before arguing about the level on it, which has saved him more money than any indicator. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about charting software and the differences between gold instruments. It is not financial advice, not investment advice and not a recommendation to buy, sell or hold any instrument or product. Trading gold and leveraged products carries a substantial risk of loss and is not suitable for everyone. Most retail accounts lose money. Past behaviour of any price series does not guarantee future results. Only risk capital you can afford to lose, and seek independent advice if you are unsure.


  • How to Set Price Alerts on MT5, and Where to Actually Put Them

    How to Set Price Alerts on MT5, and Where to Actually Put Them

    Learning how to set price alerts on mt5 takes about ninety seconds. Learning why it matters takes rather longer, because the feature looks like a convenience and is actually a piece of risk control. An alert is the difference between a trader who checks the market when something has happened, and a trader who sits in front of a chart for six hours so that nothing can happen without being watched. The second one is not more diligent. He is just more tired, and tired accounts make expensive decisions.

    This article covers the mechanics, which are simple, and then the part almost nobody does, which is working out where the alert should actually sit. That second question has a measurable answer, so rather than guess, we will use the published London gold benchmark and count.

    How to Set Price Alerts on MT5, the Ninety Second Version

    The alerts panel lives in the Toolbox at the bottom of the MetaTrader 5 window. If the Toolbox is hidden, View then Toolbox brings it back, or Ctrl+T does the same thing. Along the bottom of that panel is a row of tabs, and one of them is Alerts.

    Right click anywhere inside the Alerts tab and choose Create. A small dialog opens with the fields that matter:

    • Action. What the platform does when the condition is met. Sound, file, mail or notification. Notification is the one that reaches your phone.
    • Symbol. The instrument the alert watches. On most gold accounts this is XAUUSD, though brokers name it differently, so take the name from Market Watch rather than typing what you expect it to be.
    • Condition. Bid above, Bid below, Ask above, Ask below, or Time equals. Gold spreads can be wide, so it is worth being deliberate about whether you are watching Bid or Ask.
    • Value. The level. This is the field this article is really about.
    • Expiration. When the alert stops being valid. Leave this at the default and you will collect dead alerts for levels that stopped being interesting weeks ago.
    • Maximum iterations and timeout. How many times it may fire and how long it waits between firings. One iteration is usually right. Five is how you teach yourself to ignore your own alerts.

    For the alert to reach your phone, the desktop platform needs your MetaQuotes ID, which appears in the Messages tab of the mobile app under settings, and gets pasted into Tools, Options, Notifications on the desktop. MetaQuotes documents the whole notification path on its own trade alerts page, including the point that the platform will notify you by sound, email or push so that you do not have to spend hours watching price movement on a monitor.

    One caveat that costs people real money: desktop alerts are evaluated by the desktop terminal. If the machine is asleep, the terminal is closed, or the connection has dropped, the alert does not fire and nothing tells you it did not. If an alert genuinely has to fire while you are away from the computer, it needs to live somewhere that stays awake, which in practice means a phone app alert, a broker side alert, or a hosted terminal.

    Where to Put the Alert, Measured Rather Than Guessed

    Here is where most guidance stops and mine starts. An alert is only useful if it fires rarely enough to mean something and often enough to be worth setting. That is an empirical question, and gold has a public record that answers it.

    The London Bullion Market Association runs the auction that sets the world benchmark price for gold and publishes the entire history free. Taking the afternoon auction from 4 January 2000 to 18 September 2026 gives 6,698 consecutive sessions. For every one of them, I asked a simple question: if you had set an alert a given distance away from that day’s benchmark, in either direction, would it have fired within the next five sessions, meaning roughly one working week?

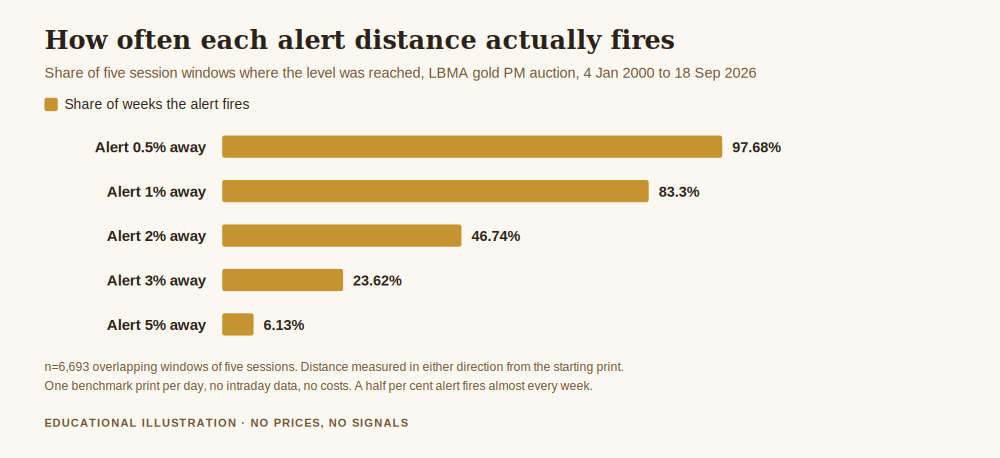
    The answer, counted across 6,693 overlapping five session windows:

    Chart showing how often each alert distance fires within a week, the core of how to set price alerts on mt5
    How often each alert distance fires within one working week, which is the number that should decide how to set price alerts on mt5.

    An alert placed half a percent away fired in 97.68 per cent of weeks. That is not an alert, that is a metronome. Gold moves through half a percent almost every week of its life, and a notification that arrives with that reliability trains you to swipe it away without reading it, which is worse than having no alert at all.

    One per cent away fired in 83.30 per cent of weeks, and when it fired, the median wait was two sessions. Two per cent away fired in 46.74 per cent of weeks, so slightly less often than a coin. Three per cent fired in 23.62 per cent, roughly one week in four. Five per cent fired in 6.13 per cent of weeks, about three times a year.

    For context on the scale, the typical single session moved 0.547 per cent from the previous benchmark, with a mean of 0.767 per cent, and there were 251 benchmark sessions in 2025. Method, so you can repeat it: one benchmark print per day, no intraday data, distance measured in either direction from the starting print, five forward sessions per window, overlapping windows, no costs, no spread, no absolute price quoted anywhere in this article.

    What Those Percentages Actually Tell You to Do

    Read the numbers as a budget for your own attention. If you set alerts at half a percent on a handful of instruments, you have signed up for several notifications a week that say nothing except that the market is open. Within a month you will stop looking at them. The alert has not failed. Your relationship with the alert has failed, and it took your trust in the whole system with it.

    Set alerts at two or three per cent instead and each notification carries information, because something has happened that does not happen most weeks. The cost is that you will sometimes wait a fortnight for one. That waiting is the product, not a defect of it.

    This is the same reasoning behind every rule in risk management for gold trading. You are deciding in advance which events deserve a reaction, and building a machine that ignores everything else on your behalf, because you will not reliably ignore it yourself at four in the afternoon on a slow Thursday.

    Four Alerts Worth Having

    These are categories rather than instructions. The levels are yours, and they should come from your own plan, not from a number in an article.

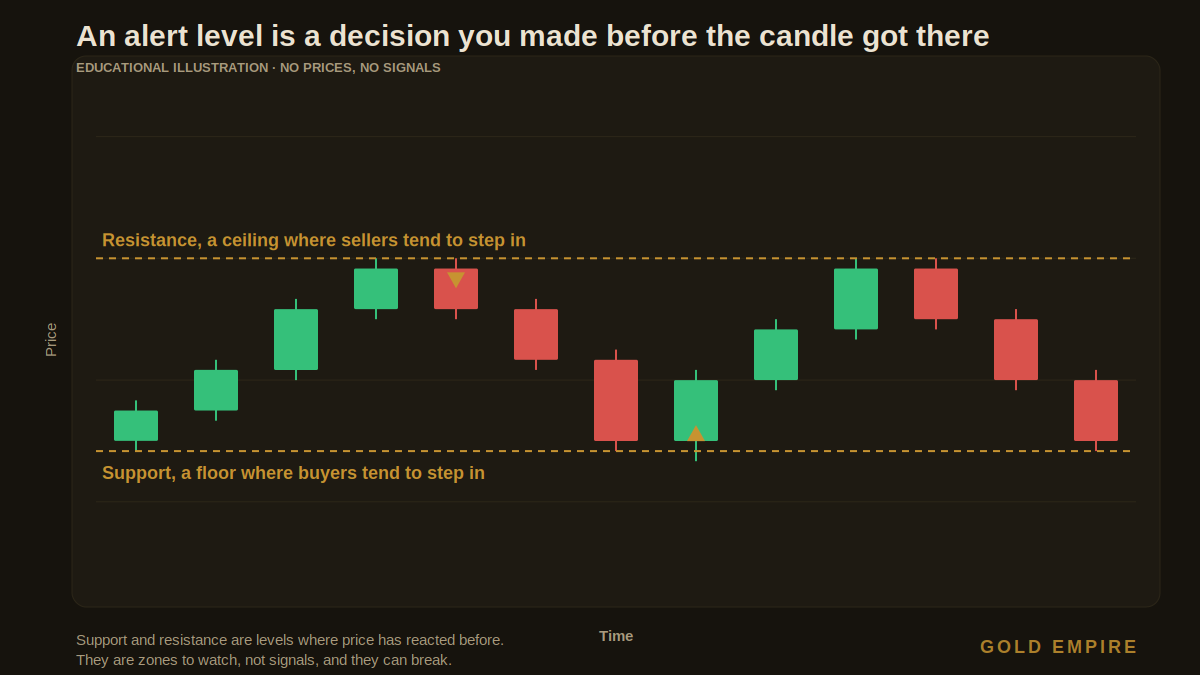
    Candle illustration of the support and resistance levels where you would set price alerts on mt5
    Levels the market has already reacted to are the usual home for an alert, which is the practical half of how to set price alerts on mt5.

    The level you already decided matters. If your analysis says a particular area is the one that would change your mind, that is an alert. Writing it into the platform converts an opinion into something the computer will remember after you have gone to bed and after you have talked yourself into a different story.

    The level that says you were wrong. Traders set alerts for the price they are hoping for and almost never for the price that invalidates the idea. The second one is the one that protects capital. If you hold a position and the market reaching a certain area would mean the reason for the trade no longer exists, that deserves a notification at least as much as the happy case.

    The time alert before a scheduled event. The Time equals condition is the least used field in the dialog. A notification fifteen minutes before a release you care about is a reminder to check your exposure while you still have a choice about it, rather than discovering it as the spread widens.

    The alert on the instrument you are not in. The whole purpose of this feature is that you can be absent. If you want to be in gold only when a particular condition appears, an alert lets you close the platform and live your life until that condition appears. People who watch a market they are not trading end up trading it.

    And one worth deleting: any alert you have snoozed twice. If you have dismissed it without acting, the level does not mean what you thought it meant when you set it. Remove it rather than leaving it to erode your attention.

    The Real Problem an Alert Solves

    I am going to be blunt about the mechanism, because it is not really a software feature at all.

    The account damage caused by screen watching is not caused by watching. It is caused by what watching leads to. A trader who is present for every tick will eventually see a move that was not in his plan, feel the pull of it, and take a position that his written rules would never have authorised. He did not abandon his method. He was just in the room when the opportunity walked past, and being in the room is most of what it takes.

    An alert removes you from the room. You are not fighting the impulse with willpower, you are arranging your day so the impulse never gets a chance to speak. That is the same design principle as a written risk limit, and it works for the same reason: rules that enforce themselves beat rules that need you to be disciplined at precisely the moment you are least able to be.

    It is also why the two or three per cent alert beats the half per cent one on more than statistical grounds. A notification you receive twice a month is an event. A notification you receive daily is wallpaper.

    What an Alert Cannot Do

    An MT5 alert is a message. It is not an order, it does not size anything, it does not close anything, and it has no opinion about whether reacting is wise. If your plan requires an action to happen at a level whether or not you are awake, that is a pending order or a stop, and the alert is at best a courtesy copy.

    It also cannot make a bad level into a good one. An alert on a number you invented while feeling impatient will fire exactly as reliably as an alert on a number you derived from your analysis, which is why the level deserves more thought than the dialog box does. If you are still building the analysis that produces those levels, reading a gold chart with a clear head is the prerequisite, and adding XAUUSD in MT5 covers the step before this one if gold is not yet in your Market Watch.

    Finally, an alert will not fire on a market that is closed. Gold does not trade continuously, weekend closures exist, and a level reached while the market was shut is a level you meet on Monday at whatever the market thinks by then. That is a gap risk problem, not an alerts problem, and no notification setting solves it.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    Do MT5 price alerts work when the platform is closed?

    Desktop alerts do not. They are evaluated by the terminal on your computer, so if the machine is asleep or the platform is shut, the condition can be met without anything happening, and you will not be told afterwards. Alerts set inside the mobile app, or on a platform running on a hosted server, keep working while your computer does not.

    How many price alerts should I have running at once?

    Few enough that each one still makes you look. There is no technical limit worth worrying about, but there is an attention limit, and the measurement above shows how quickly you hit it: alerts set close to the current price fire in the great majority of weeks, and a notification stream that reliable stops being read.

    Should the alert watch Bid or Ask?

    Match it to what you would actually do. A level that matters for a buy is reached at the Ask, and a level that matters for a sell is reached at the Bid. On an instrument with a wide spread the two can be meaningfully far apart, so choosing by habit rather than by purpose will fire the alert slightly early or slightly late every time.

    Is a price alert a substitute for a stop loss?

    No, and treating it as one is a genuinely dangerous swap. A stop is an instruction sitting with the broker that executes without you. An alert is a message that requires you to be awake, holding your phone, and willing to act. Those are not the same protection.

    Why does my alert fire and then fire again immediately?

    Because maximum iterations is above one and the timeout is short. Price hovering around the level re-triggers the condition. Set iterations to one for a level you only need to hear about once, and use the timeout for the cases where you genuinely want a repeat.

    Where Gold Empire Fits

    Gold Empire is free to follow. Daily XAU/USD analysis on Telegram, with the reasoning stated before the trade rather than after it, losing days included. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the full method. Nothing here promises a profit and nothing here is a signal service.

    The pillar this sits under is risk management for gold trading, the number the alert is supposed to protect is covered in how much to risk per trade, and the platform groundwork is in how to add XAUUSD in MT5. The benchmark data behind every percentage above is published by the London Bullion Market Association, and the raw file used is the published PM auction history. More about who writes this is on the about page.

    About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He is suspicious of any setup that requires him to be at a desk, on the grounds that the desk has taken more money from him than the market ever has. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about platform features, notifications and attention management in retail trading. It is not financial advice, not investment advice and not a recommendation to buy, sell or hold any instrument, product or firm. Platform behaviour varies by broker and by version, so verify settings in your own terminal. Figures are calculations from the stated public data and stated assumptions, not predictions or performance claims. Trading leveraged products carries a substantial risk of loss and most retail accounts lose money.


  • How to Sell Gold on MetaTrader 5, and the Button That Costs People Accounts

    How to Sell Gold on MetaTrader 5, and the Button That Costs People Accounts

    There is a version of this question that the manuals answer in four lines, and a version that costs people real money. The first is mechanical: which button, which box, which number. The second is the one nobody warns you about, and it is why how to sell gold on metatrader 5 is worth more than four lines of explanation.

    Here is the short version, so nobody has to read three thousand words to place a trade. Open the Market Watch, find your gold symbol, press New Order, set the volume, press Sell by Market. That is the whole mechanical answer, and if that is all you came for, you can stop reading.

    The part worth staying for is this. On MetaTrader 5, pressing Sell while you already hold a buy position does not always do what you think it does. On some accounts it closes your position. On other accounts it opens a second one, in the opposite direction, and leaves the first exactly where it was. Same platform, same button, opposite outcome, and which one you get was decided by your broker before you ever logged in.

    How to Sell Gold on MetaTrader 5, the Mechanical Part

    Assuming the symbol is already in your Market Watch, and if it is not then adding XAU/USD in MT5 is the first job, there are three routes to a sell order and they all reach the same place.

    • Right-click the symbol in Market Watch and choose New Order. The order window opens with that symbol preselected.
    • Press F9 from anywhere in the terminal. Faster, and it uses whichever chart is focused, which is exactly why it is also the way people place orders on the wrong instrument.
    • Use the one-click trading panel in the top-left corner of the chart, if your broker has it enabled. Fastest, and the least forgiving, because there is no confirmation step between your finger and the market.

    In the order window you set four things. The symbol, which you should read rather than assume. The volume, in lots. The order type, which is Market Execution for an immediate fill and Pending Order if you want it to trigger later at a level. Then you press Sell, which sits on the left and is usually red.

    A market sell fills at the bid, and the difference between bid and ask is the spread, which you have now paid. A pending sell comes in two flavours that people confuse constantly: a Sell Limit sits above the current price and triggers if price rises into it, a Sell Stop sits below and triggers if price falls through it. If that distinction is not automatic yet, the buy-side version of the same logic explains the geometry properly.

    That is the mechanics, and none of it is the hard part. The hard part is what happens on the second press.

    Sell Does Not Mean Close, and That Is Where Accounts Get Hurt

    Picture the ordinary sequence. You are long gold. The trade goes against you. You decide to get out. You look at the terminal, you see a Sell button, and selling is obviously the opposite of buying, so you press it.

    On some accounts you are now flat, which is what you wanted. On others you are now long and short at the same time, in the same instrument, for the same volume. Your net exposure is zero, so the loss stops growing, which feels like it worked. It did not work. Your original loss is still sitting there, frozen at whatever it was, and you now own two positions instead of none, both of which still cost you money to carry and both of which you will eventually have to close.

    Traders call the second outcome a lock, or a hedge. Sometimes it is done deliberately. Far more often it is done by someone who thought Sell meant close, and the difference between those two situations is entirely a matter of whether you knew which kind of account you were on.

    Netting or Hedging: Your Broker Already Chose for You

    MetaTrader 5 has two position accounting systems, and the official documentation is unusually direct about it. As the MetaTrader 5 trading help puts it, “the system used depends on the account and is set by the broker.” You do not choose it from a menu. You inherit it.

    On a netting account, the documentation states that when “a deal is executed in the opposite direction, the volume of the existing position can be decreased, the position can be closed (when the deal volume is equal to the position volume) or reversed (if the volume of the opposite deal is greater than the current position).” So on a netting account, selling the exact volume you are long does close you out. Selling more than that flips you short, which is its own surprise if you were not expecting it.

    On a hedging account, the same documentation says that if “you have an open position for a symbol, and execute a new deal (or a pending order triggers), a new position is additionally opened. Your current position does not change.” That is the lock. Your losing trade is untouched, and a second trade now sits beside it.

    Most retail forex and gold brokers hand out hedging accounts, because MetaTrader 4 only ever worked that way and the habit carried over. But you cannot rely on a habit for something this consequential. Check it before you need to know: place one small test order in the opposite direction to something you already hold, and watch the Trade tab. If the position vanishes, you are on netting. If a second line appears, you are on hedging. Two minutes, once, and then you know.

    What the Accidental Lock Actually Costs

    People tolerate the accidental lock because it looks free. The loss stopped moving, nothing was crystallised, no harm apparently done. The harm is real, it is just spread across three separate bills.

    The first bill is spread. Closing a position correctly costs you one exit. Locking costs you an extra entry now, on the unwanted second position, and an extra exit later when you finally unwind it. Two extra crossings of the spread, and the size of that bill scales exactly with your position size.

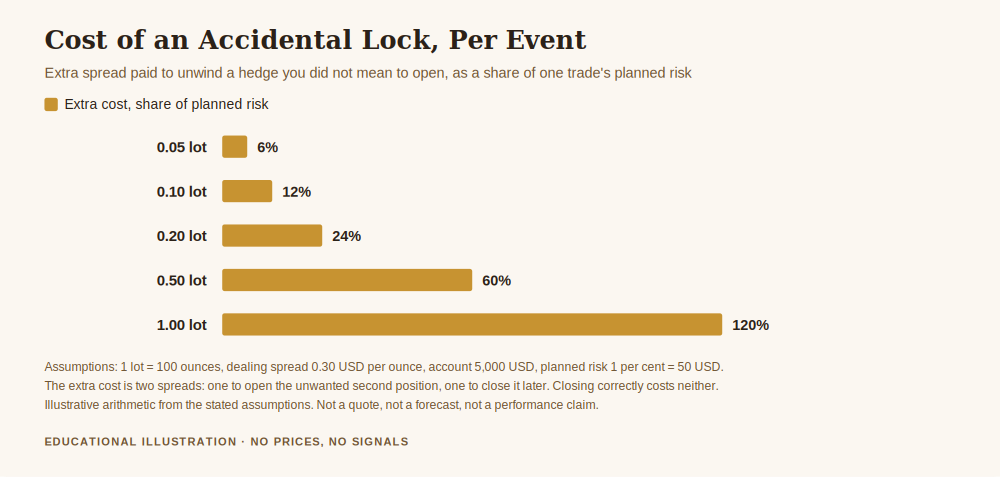
    Chart of what an accidental lock costs when learning how to sell gold on MetaTrader 5, by position size
    What an accidental lock costs by position size, when you press Sell on MetaTrader 5 expecting it to close a gold position

    Work it at a dealing spread of 0.30 US dollars per ounce, with the standard contract of 100 ounces to a lot, on a 5,000 dollar account risking one per cent, so 50 dollars, per trade. At 0.20 lot the accidental lock costs 12.00 dollars in extra spread, which is 24.0 per cent of the entire risk budget for that trade. At 1.00 lot it costs 60.00 dollars, which is 120.0 per cent, more than the whole planned risk, spent on nothing but a misunderstanding about a button.

    Now make it a habit rather than an accident. Two hundred trades in a year, with this going wrong on one in twenty of them, is ten events. At 0.20 lot that is 120.00 dollars a year, or 2.40 per cent of the account, which is 2.4 full units of risk handed over annually for no exposure and no thesis. Those are illustrative figures from the assumptions just stated, not a forecast, but the structure of the bill does not change when you substitute your own numbers.

    The second bill is swap. Both legs of a lock are financed positions, so you pay or receive the overnight charge on each of them, and on most gold accounts the two do not cancel. The net is usually a drip out rather than in, every night, for as long as the lock sits there.

    The Margin Arithmetic Nobody Shows You

    The third bill is the one that ends accounts, and it is the least obvious, because a locked pair feels safer than a naked position. It is not. It can be strictly more dangerous.

    Under the retail rules the European regulator introduced in March 2018, leverage on gold for retail clients is capped at 20 to 1, which means opening margin is 5.00 per cent of the notional value of the position. Those same measures set a margin close-out rule on a per account basis at 50 per cent of required margin, along with negative balance protection and the finding that 74 to 89 per cent of retail accounts typically lose money.

    Follow the arithmetic through a lock. One position needs 5.00 per cent of notional in margin, and the close-out rule reaches for you when equity falls to half of that, so 2.50 per cent of notional. Many brokers charge margin on both legs of a locked pair rather than netting them off. If yours does, the requirement becomes 10.00 per cent of notional, exactly twice, and the close-out level rises to 5.00 per cent of notional, also exactly twice.

    Read that last sentence again, because it inverts the intuition completely. The position that feels safe, because net exposure is zero, is the position that gets you force-closed at twice the equity level. You have not reduced your risk. You have raised the floor you fall onto, and you did it while believing you had bought yourself time. Some brokers do net the margin on locked pairs, some do not, and the platform’s own margin documentation is the place to start before you assume yours is generous.

    How to Close a Gold Position Properly on MT5

    Since Sell is not the answer, here is what is.

    • In the Toolbox at the bottom of the terminal, open the Trade tab. Every open position is listed there.
    • Find the line for your gold position and click the small × on its right-hand edge. That closes the whole position, at market.
    • To close part of it, right-click the line, choose Close Position, and set a smaller volume before confirming. Closing 0.05 of a 0.20 lot position leaves you long 0.15, not long 0.20 and short 0.05.
    • To close everything at once, right-click anywhere in the Trade tab and use Close All. Read which option you picked, because there are variants that close only profitable positions or only losing ones.

    The rule underneath all four is worth stating plainly: to reduce exposure, act on the position, not on the market. The × belongs to the position. The Sell button belongs to the market, and the market is happy to sell you something new at any hour.

    The Volume Box Is the Other Way This Goes Wrong

    The second recurring accident on MT5 is not the button, it is the number beside it. Volume is in lots, and one lot of gold is 100 ounces, so the gap between 0.10 and 1.00 is not cosmetic. It is ten times the exposure, which turns a planned one per cent risk into ten per cent on a single trade, and a ten per cent hole needs an 11.11 per cent gain to fill.

    Two habits fix this permanently. Work out the volume from your risk before the order window is open, which is what calculating lot size for gold and forex is for, and read the volume box out loud before confirming. It looks absurd, and it is the cheapest insurance in the terminal. If you need to adjust a trade rather than close it, modifying an open trade covers that logic, which is nearly identical across MT4 and MT5.

    A Short Checklist Before You Press Sell

    None of this requires a system. It requires four questions, asked in the two seconds before the click.

    • Am I opening a new short, or trying to close something I already hold? If it is the second, the Trade tab is where I should be, not the order window.
    • Is this account netting or hedging? If I do not know, I find out before I am under pressure, not during.
    • Is the volume box the number I calculated, or a number I typed quickly?
    • Is the symbol the one I meant? Gold trades under different tickers at different brokers, and F9 does not care which chart you were looking at.

    These are unglamorous questions. They also cover most of the ways a routine exit turns into an expensive afternoon, and none of them requires you to be right about where gold goes next.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently Asked Questions

    How to sell gold on MetaTrader 5 if I do not already own any gold?
    The same way. A sell here is a contract for difference on the gold price, not a sale of metal, so nothing has to be in your possession first. You are agreeing to settle the difference in price, which is also why the position carries margin and an overnight financing charge rather than a storage cost.

    Why did pressing Sell not close my buy position?
    Because your account almost certainly uses the hedging accounting system, where a new deal opens an additional position and leaves the existing one untouched. Close positions from the Trade tab in the Toolbox instead, using the × on the position’s own line.

    Is locking a position a legitimate strategy?
    Some traders use it deliberately, usually to hold exposure through an event without closing. It is not free: you pay an extra spread to open the second leg and another to unwind it, you carry swap on both legs, and if your broker charges margin on both sides, your close-out level moves against you. Doing it on purpose after counting those costs is a decision. Doing it by accident is a bill.

    How do I tell whether my account is netting or hedging?
    Place one very small order opposite to an existing position and watch the Trade tab. One line means netting, two lines mean hedging. Your broker’s account specification page will also say, and the platform sets it from the server rather than from anything you can change locally.

    Does MetaTrader 4 work the same way?
    MT4 only ever offered the hedging model, so an opposite order there always opens a second position. MT5 supports both, which is precisely why the assumption people carry over from MT4 is no longer safe.

    Where did the figures in this article come from?
    The 20 to 1 gold leverage cap, the 50 per cent margin close-out rule and the 74 to 89 per cent retail loss range are quoted from the ESMA measures linked above, checked live before publication. The netting and hedging wording is quoted from the MetaTrader 5 help pages linked above. The cost figures are arithmetic from stated assumptions: a 0.30 dollar per ounce spread, 100 ounces to a lot, a 5,000 dollar account and one per cent risk per trade. None of them is a price quote, a forecast or a performance claim.

    Where Gold Empire Fits

    Gold Empire is free to follow. Daily XAU/USD analysis on Telegram, with the reasoning stated before the trade rather than after it, losing days included. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the full method. Nothing here promises a profit and nothing here is a signal service.

    Knowing your platform is part of risk control rather than separate from it. Risk management for gold trading is the pillar this article sits under, leverage in gold trading explains why the margin arithmetic above bites so hard, and managing a gold trade after you enter covers the decisions that come after the order is filled. More about who writes this is on the about page.

    About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He has a particular dislike of interfaces that hide a consequential decision behind an obvious-looking button. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about trading platform mechanics, order handling and margin rules in retail trading. It is not financial advice, not investment advice and not a recommendation to buy, sell or use any product, platform or firm. Platform behaviour and broker terms vary and change, regulatory rules differ by jurisdiction, and the quoted documentation should be checked in its current form. Trading leveraged products carries a substantial risk of loss and most retail accounts lose money. Figures are illustrative calculations from stated assumptions, not predictions or performance claims.


  • What Is an ECN Account, and What the Label Legally Means

    What Is an ECN Account, and What the Label Legally Means

    Somebody opens a broker’s account comparison page, sees three columns, and asks the reasonable question: what is an ECN account, and is it the one a serious person picks? The page usually answers with a tighter spread, a commission per lot, and a phrase like direct market access or no dealing desk.

    That answer describes a price list. It does not describe what the three letters mean, and the gap between those two things is where the money quietly goes. So this article does both. First what an ECN actually is in the only place the term has a legal definition, which will surprise most people. Then what an ECN account is in practice at a gold broker, which is a different thing entirely. Then the arithmetic that decides whether it is cheaper for you, which is the only part you can actually act on.

    What Is an ECN Account: Start With What the Letters Mean

    ECN stands for electronic communications network. The term is not marketing language in origin. It has a definition in United States securities regulation, and you can read it yourself in the definitions section of Regulation NMS at 17 CFR 242.600.

    The definition says an electronic communications network is any electronic system that widely disseminates to third parties orders entered in it by an exchange market maker or an OTC market maker, and permits those orders to be executed against in whole or in part.

    Read that once more, because every clause is load bearing. Orders are widely disseminated to third parties, so other participants can see them. Those orders come from market makers in a regulated quoting system. And other participants can execute against them directly.

    Then the definition does something that almost nobody quoting the term mentions. It carves two things out. The first exclusion is a system that crosses orders at set times at a single price and does not let participants execute against each other outside those times. The second exclusion is the one that matters here: a system operated by, or on behalf of, an OTC or exchange market maker that executes customer orders primarily against the account of that market maker as principal, other than riskless principal.

    In plain terms, the regulation explicitly says that a venue where your order is filled mainly by the operator taking the other side is not an electronic communications network. That is not my interpretation. It is the text of the carve out.

    The Word Has a Home, and It Is Not Retail Gold

    Here is the part that reframes the whole question. That definition lives in Regulation NMS, which governs the national market system for United States equities. It applies to shares quoted and traded on American exchanges. It is a term of art from stock market structure.

    Spot gold is not an equity. XAUUSD is not listed on a national securities exchange. Neither is a currency pair, and neither is a contract for difference on any of them. So when a gold broker offers you an ECN account, it is not claiming a regulatory status under that rule, because that rule does not reach the product at all.

    You can see how seriously the real thing is regulated by looking one section over. Under 17 CFR 242.301, an alternative trading system, the broader category ECNs belong to, has to register as a broker dealer and file a Form ATS with the Commission at least 20 days before it starts operating, plus an amendment at least 20 days before any material change to how it works. That is a filing regime with a paper trail, and it exists precisely because who matches your order matters.

    None of that machinery applies to the label on a retail gold account. Which leads to the honest answer to the headline question: ECN account is a product name, not a regulated status. It might describe an excellent execution arrangement. It might describe a marked down spread with a commission bolted on. The three letters do not tell you which, and no amount of staring at the comparison table will.

    So What Is an ECN Account in Practice?

    Strip the label away and what a broker is usually offering is a pricing model, not a venue. Two models exist and every account type is one of them wearing a different name.

    The all in spread model. One number quoted, wider than the underlying market, no separate charge. The broker’s revenue is inside the spread, so you never see it itemised. Usually called standard or classic.

    The raw spread plus commission model. A much tighter quoted spread, plus an explicit commission per lot. The broker’s revenue is now on the invoice. Usually called ECN, raw, or zero.

    The second one feels more honest and often is, in the narrow sense that you can see what you are paying. But visible is not the same as cheap, and this is the trap the label sets. People read the commission as the cost of the account, compare commissions across brokers, and pick the lowest. The commission is the smaller half of the bill and it is the half that does not change.

    The Arithmetic That Actually Decides It

    Let us put a number on it. Assume a standard gold contract of 100 troy ounces per lot. I will express the spread in dollars per ounce rather than pips, because every broker defines a gold pip differently and that ambiguity is where comparison errors breed. No gold price appears anywhere in what follows, and none is needed.

    The cost of a round turn on one lot is the spread times 100 for the standard account, and the spread times 100 plus the commission for the raw account. Set them equal and you get the break even condition, which is pleasingly simple:

    The standard account has to be quoting a spread wider by the commission divided by 100, measured in dollars per ounce.

    So at a commission of 7.00 dollars round turn per lot, the standard account must be at least 0.07 dollars per ounce wider before the raw account is genuinely cheaper. At 10.00 dollars it needs to be 0.10 wider, at 14.00 dollars, 0.14 wider. That is the entire comparison, and you can run it in your head at the broker’s page instead of trusting the layout of the table.

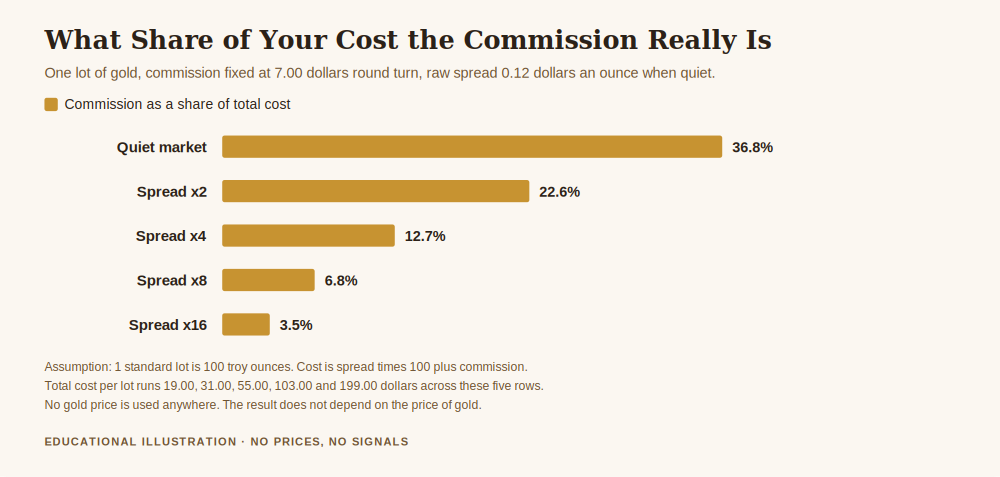
    Now the part that matters more, and that the comparison page will never show you.

    Chart for what is an ECN account, showing the commission falling from 36.8 percent of total trading cost in a quiet market to 3.5 percent when the spread widens sixteen times
    What is an ECN account worth in a fast market: with the commission fixed at 7.00 dollars a lot, its share of your total cost collapses from 36.8 percent to 3.5 percent as the spread widens, because the spread is the part that moves.

    Hold the commission at 7.00 dollars and start the raw spread at 0.12 dollars an ounce in a quiet market. Total cost per lot is 19.00 dollars, and the commission is 36.8 percent of it. Now let the spread widen the way spreads do around a scheduled release or a thin hour. At twice as wide, total cost is 31.00 and the commission is 22.6 percent. At four times, 55.00 and 12.7 percent. At eight times, 103.00 and 6.8 percent. At sixteen times, 199.00 dollars and the commission is 3.5 percent of what you just paid.

    The total bill went up 10.47 times. The commission did not move at all.

    Which tells you something the account names actively obscure. The number printed on the comparison page, the fixed and knowable one, is the part that barely matters when it hurts. The variable one, the spread, is the part that does all the damage, and it is largest exactly when you most need to get in or out. Choosing an account by its commission is optimising the component that does not vary while ignoring the one that does.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting your account from the costs that only show up when the market is moving. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    What to Check Instead of the Label

    If the three letters carry no guarantee, the useful move is to replace the label with questions that have verifiable answers. Five of them, in the order I would run them.

    One of those questions is large enough to have its own article: who is legally the other side of your trade. What is an ECN broker takes that up from the firm side, using the CFTC rulebook for retail forex rather than the equity definition used above, and shows what ordinary cost does to an account before any of these checks are made.

    Who regulates the entity you are actually contracting with? Not the group, not the brand on the website, the specific legal entity named in the client agreement. Then look it up on that regulator’s own public register, not on the broker’s page about its regulation.

    What does the order execution policy document say? Regulated firms publish one. It describes how orders are handled and whether the firm may act as principal. That document is the answer to the question the account name is pretending to answer, and almost nobody reads it.

    Is slippage symmetric? Ask whether price improvement is passed on as readily as adverse slippage. A firm that fills you worse when the market moves against you and never better when it moves for you has told you something about its model that no acronym will.

    What is the total cost per lot, in one number? Spread times contract size plus commission, calculated by you, for the hour you actually trade. Two numbers cannot be compared across brokers. One can.

    What does the spread do in the minutes that matter? Watch it yourself around a scheduled release on a demo or a small live account before you commit size. This is the only one of the five that takes patience rather than reading, and it is the one that tells you the most.

    Notice that none of those five questions mentions ECN. That is the point. The label was never the variable, and treating it as one is how people end up paying more at the account that advertised paying less.

    Frequently Asked Questions

    What is an ECN account in forex or gold trading?
    In practice it is a pricing model: a tighter raw spread plus an explicit commission per lot, as opposed to an all in wider spread with no separate charge. The term itself comes from United States equity market structure, where 17 CFR 242.600 defines an electronic communications network, and that definition does not apply to spot gold or currency pairs. So the name describes the price list, not a regulated status.

    Is an ECN account better than a standard account?
    Only if the standard account’s spread is wider than the raw spread by more than the commission divided by the contract size. With a 7.00 dollar round turn commission on a 100 ounce lot, that gap has to be at least 0.07 dollars an ounce. Below that, the standard account is cheaper. It is a calculation, not a tier.

    Does an ECN account mean my orders go to the real market?
    The name does not establish that. The regulatory definition of an electronic communications network specifically excludes a system that fills customer orders primarily against the operator’s own account as principal. Whether that applies to your provider is answered by its order execution policy and its regulator’s register, not by the account label.

    Why does my ECN account still cost more on news?
    Because the commission is fixed and the spread is not. In the illustration above, the commission holds at 7.00 dollars while total cost per lot runs from 19.00 to 199.00 as the spread widens, so the commission’s share of the bill falls from 36.8 percent to 3.5 percent. The account type does not change what happens to a spread in a fast market.

    Is a lower commission the right thing to compare?
    It is the easiest thing to compare and the least decisive. Compare one total cost per lot for the hour you actually trade instead, and check the spread’s behaviour around scheduled releases before you commit size.

    Where did the numbers in this article come from?
    The definition of an electronic communications network and its two exclusions are the text of 17 CFR 242.600, and the broker dealer registration and 20 day Form ATS filing requirements are 17 CFR 242.301, both linked above. Every cost figure is my own arithmetic under the assumptions stated in the text: 100 troy ounces per lot, a 7.00 dollar round turn commission, and a 0.12 dollar per ounce raw spread in a quiet market. Commission levels and spreads vary by firm and by hour, so run the calculation on your own numbers. No gold price appears anywhere in this article.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily gold analysis with the reasoning written out, losing days included, plus an optional Kit for people who want the method in one place. There is no promise of profit here, because nobody honest can make one.

    What an account costs you is a survival question before it is a preference, which is why this sits under risk management in gold trading. Raw spread account vs standard account takes the same comparison further into the two pricing models, what the spread is in gold trading covers the component that does all the moving, and how to choose a broker for gold trading puts the account type back in its place as one line among several. If you have not opened an account yet, how to open a gold trading account is the step before this one.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He is more interested in the mechanics that quietly drain accounts than in the setups that fill timelines. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about account types, order handling terminology and trading costs. It is not investment advice, not a recommendation of any broker, account type or platform, and not a solicitation to trade. The definition of an electronic communications network and its exclusions are quoted from 17 CFR 242.600, and the alternative trading system requirements from 17 CFR 242.301. Those are United States securities rules summarised here rather than reproduced in full, they are amended from time to time, and they do not govern retail spot gold or foreign exchange in most jurisdictions; nothing here is legal advice and account naming conventions differ by firm and by country. No statement is made about the execution model of any particular broker, and readers should check the client agreement, the order execution policy and the relevant public register themselves. Every cost figure is my own arithmetic under the assumptions written out in the text, using illustrative commission and spread values rather than any firm’s actual pricing, and no gold price level is quoted. Trading gold carries a real risk of losing money, including more than you deposit in some account types. Nothing accounts for your personal circumstances, and no entry, stop or target discussed should be treated as a signal. If you are unsure, speak to someone properly qualified in your own jurisdiction before you risk anything.


  • What Does Swap Free Mean, and What Replaces the Charge?

    What Does Swap Free Mean, and What Replaces the Charge?

    Somebody asked me last week to settle an argument he was having with himself. He had been offered a swap free account, and the offer sounded like a small miracle: hold positions as long as you like, no overnight charges, nothing quietly ticking away against you at midnight. He wanted to know what does swap free mean in practice, and whether he should move his account across.

    The short version is that swap free means the broker does not apply the overnight financing charge. The longer and more useful version is that the cost does not vanish, because it never belonged to the broker in the first place. It changes shape. And whether the new shape is cheaper than the old one depends on one number that nobody asks about, which is how many days you hold a position.

    I want to do that arithmetic in the open, because it is not difficult and it gives you a decision rule instead of a feeling.

    What does swap free mean, in plain terms

    When you hold a leveraged position past the daily rollover point, a normal account applies a swap, sometimes called an overnight financing charge or a rollover. It appears on your statement as a small debit, occasionally as a small credit, once per day, and three times on one day of the week to cover the weekend.

    A swap free account, often marketed as an Islamic account because the arrangement was created to avoid interest for observant Muslim traders, simply does not apply that line. Your position sits there overnight and no financing debit appears.

    That is the whole of the mechanical answer. What it is not is a claim that holding a leveraged position overnight has become costless, because that is not a thing a broker has the power to arrange.

    Where the swap number actually comes from

    This is the part that reframes everything, and it is why I wanted to write this article rather than a list of account features.

    When you open a leveraged position you are controlling a quantity of an asset with a fraction of its value. The rest is financed. Financing has a price, and that price is set by short term interest rates in the wider economy, not by your broker’s marketing department. This is the same mechanism I went through in what leverage in gold trading actually is, seen from the cost side rather than the size side.

    You can look up the anchor rate yourself, today, for free. The Federal Reserve publishes it in the H.15 Selected Interest Rates release every business day at 4:15pm. In the release dated 28 August 2026, the effective federal funds rate was 3.63 percent per annum, and had been 3.63 percent on each of the five preceding business days shown. The same table gives the bank prime loan rate at 6.75 percent and the one year Treasury constant maturity at 4.04 percent.

    Gold has its own layer on top of that. Reference prices and forward pricing for the physical market are published by the London Bullion Market Association, and the relationship between a spot price and a forward price is, in essence, the cost of carrying metal across time. Your swap line is a retail expression of that same idea.

    So the swap is not an invented fee. It is a real financing cost, anchored to a published rate, with a broker margin added on top. Hold that thought, because it tells you exactly what has to happen when a broker agrees to stop charging it.

    The arithmetic of what you are actually being charged

    Let me put numbers on it. Every figure below is my own arithmetic, and here are the assumptions in full so you can change them and rerun the sums yourself.

    Take a position with a notional value of 10,000 units of account currency. Take the financing rate as the published anchor of 3.63 percent plus a broker margin of 2.00 percentage points, giving 5.63 percent per annum. Use a 365 day year. Then the daily financing cost is 10,000 multiplied by 5.63 percent, divided by 365, which is 1.542 units per day.

    That is the number the swap free account removes. Now, what does it charge instead?

    In practice, brokers offering swap free accounts replace the financing line with something else, and the common forms are a flat administration fee per position per day after a grace period, a wider spread on that account type, or a higher commission. The specific numbers vary by broker and I am not going to pretend to know yours. So let us take a clearly labelled assumption and see what the shape of the answer is: a grace period of three days, after which a flat administration fee of 3.00 units per day applies to the same position.

    Chart for what does swap free mean, showing a swap free account costs less for holds under about six days and more beyond that
    What does swap free mean for your costs: the crossover sits at about six days on the assumptions stated in this article.

    Here is what falls out.

    • Hold for 1 day: normal account 1.54, swap free 0.00. Swap free is cheaper.
    • Hold for 3 days: normal 4.63, swap free 0.00. Swap free is cheaper.
    • Hold for 6 days: normal 9.25, swap free 9.00. Almost identical.
    • Hold for 7 days: normal 10.80, swap free 12.00. The normal account is now cheaper.
    • Hold for 30 days: normal 46.27, swap free 81.00.
    • Hold for 90 days: normal 138.82, swap free 261.00.
    • Hold for 365 days: normal 563.00, swap free 1,086.00.

    The crossover point comes from setting the two totals equal. The daily swap multiplied by the number of days equals the administration fee multiplied by the number of days beyond the grace period. That solves to 3.00 times 3, divided by 3.00 minus 1.542, which is 6.17 days.

    Under these assumptions, then: hold for less than about six days and the swap free account genuinely costs you less. Hold for longer and it costs you more, and the gap widens every single day after that, because the daily administration fee is about 1.94 times the daily financing charge it replaced.

    Why the answer depends on you, not on the account

    Notice what the arithmetic did not say. It did not say swap free accounts are a trick, and it did not say they are a bargain. It said the account type is the wrong thing to be arguing about.

    The variable that decides the outcome is your holding period, which is a property of your method, not of the broker’s product sheet. If you close everything the same day and hold nothing over the weekend, the swap line is nearly irrelevant to you either way and you are choosing between two versions of almost nothing. If you routinely hold positions for weeks, the choice is worth real money and, on these assumptions, points the opposite way to the marketing.

    There is a second thing worth noticing. A swap is not always a debit. Depending on the direction of your position and the rates involved, it can be a small credit. A swap free account removes that too. You are not removing a cost, you are removing a line that could go either way and replacing it with a fee that only goes one way.

    And there is a third, which is the one that quietly does the most damage. If the replacement is not an explicit administration fee but a wider spread, then the cost has moved from a line you can read on your statement into a number you never see itemised at all. That is a worse position to be in, not a better one, even if the total happens to be similar. A cost you can count is a cost you can manage. I made the same argument about account types in raw spread against standard accounts, and it applies here without modification.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of slow, quiet costs this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    The four questions to ask before you open one

    If you are considering a swap free account, these four questions get you the whole picture, and any broker worth using will answer all of them in writing.

    Is there a grace period, and how long is it? This single number moves the crossover point more than anything else. A longer grace period pushes the crossover further out and makes the account better for medium holds.

    What exactly replaces the swap, and in what unit? A fee per position per day, per lot per day, or a spread adjustment are three quite different things. Get it stated in the same unit you can measure, and do not accept a description that avoids naming one.

    Is the spread or commission different on this account type? Compare the account against the normal account at the same broker on the same instrument, at the same time of day. If the spread is wider, that difference is part of the price and belongs in your arithmetic.

    What is my actual median holding period? This one is not a question for the broker. It is a question for your own trade record, and if you cannot answer it, that is the first thing to fix, because without it you cannot evaluate any of the above. Your holding period is the input that decides the answer.

    Frequently asked questions

    What does swap free mean, in one sentence?

    It means the broker does not apply the overnight financing charge to positions held past rollover, and instead recovers that cost in another form, usually a flat administration fee after a grace period, a wider spread, or a higher commission.

    Is a swap free account actually free?

    No, and no account is. The underlying financing cost is anchored to real short term interest rates, which the Federal Reserve publishes daily and which no broker controls. What changes is the form and the visibility of the charge, not its existence.

    So is swap free cheaper or more expensive?

    It depends entirely on how long you hold. On the assumptions in this article, a grace period of three days and an administration fee of 3.00 per day against a daily financing cost of 1.542, the crossover is at 6.17 days. Shorter holds favour swap free, longer holds favour the normal account, and the gap grows with every additional day.

    Do I need to be Muslim to open one?

    The account type exists to serve traders who must avoid interest for religious reasons, and that is its purpose. Availability and eligibility rules vary by broker and by jurisdiction, so that is a question for the broker and, if the religious question matters to you, for someone qualified to answer it. This article is about the arithmetic, not about the ruling.

    Can the broker change the fee later?

    Read the terms. Fee schedules on this account type are typically variable at the broker’s discretion, which means your crossover point can move without your method changing at all. Recheck it periodically rather than assuming today’s arithmetic is permanent.

    Where did the figures in this article come from?

    The effective federal funds rate of 3.63 percent, the bank prime loan rate of 6.75 percent and the one year Treasury constant maturity of 4.04 percent are read directly from the Federal Reserve’s H.15 Selected Interest Rates release dated 28 August 2026, linked above, and the precious metals reference pricing is published by the LBMA, also linked. Everything else, the 2.00 point broker margin, the 10,000 notional, the 365 day year, the three day grace period, the 3.00 daily administration fee, the 1.542 daily financing cost, the whole table and the 6.17 day crossover, is my own arithmetic on assumptions stated in the text. No gold price appears anywhere in this article, because none is needed: every figure is a rate, a ratio or a count.

    Where Gold Empire fits

    Gold Empire is a free place to learn how gold actually behaves and how accounts actually die, written for people who would rather survive the first two years than have a spectacular first month. Everything on the site is free to read. If you are new here, start here is the guided way in. There is a free survival sheet if you want the one page version, and an optional kit for people who want the whole framework in order. Nothing here promises you a return, because nobody honest can.

    Costs are a survival topic rather than a technical one, which is why they sit under risk management in gold trading. If you want the mechanism this article assumes you already know, what swap in gold trading is covers the charge itself, and what the spread in gold trading is covers the place a removed fee most often reappears. When you are comparing account types across firms, the broker comparison is the practical companion to this one.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He is more interested in the mechanics that quietly drain accounts than in the setups that fill timelines. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about how overnight financing charges work and about the arithmetic of comparing account types. It is not investment advice, not religious or legal advice, not a recommendation of any broker, platform or account type, and not a solicitation to trade. Fee structures, grace periods and eligibility rules differ by broker and by jurisdiction and change without notice, so verify the current terms with the firm in writing before deciding anything. The interest rate figures are read from the Federal Reserve H.15 release dated 28 August 2026 and the precious metals reference pricing is published by the LBMA. The broker margin, the administration fee, the grace period and the notional are assumptions of mine chosen to illustrate the method, not observations of any firm’s actual pricing, and every derived figure is my own arithmetic on those stated assumptions. Trading gold carries a real risk of losing money, including more than you deposit in some account types. No gold price level is quoted anywhere here. Nothing accounts for your personal circumstances, and no entry, stop or target discussed should be treated as a signal. If you are unsure, speak to someone properly qualified in your own jurisdiction before you risk anything.


  • How to Trade XAUUSD in US Accounts, and Why the Order Gets Rejected

    How to Trade XAUUSD in US Accounts, and Why the Order Gets Rejected

    A reader in Ohio sent me a screenshot last month. His platform showed XAUUSD, the chart was live, the spread was quoted, and every time he tried to open a position the order was rejected. He assumed his account was broken, then that his broker was scamming him, and by the time he wrote to me he was about to wire money to an offshore firm that had promised him it would work.

    That last step is the one that ends accounts, so it is worth answering the question properly. How to trade XAUUSD in US accounts is not a platform problem, and it is not a broker being difficult. It is a rulebook, and once you can see the rulebook the answer becomes straightforward: the instrument most of the world calls XAUUSD is largely not available to United States retail clients in the form they are used to, and the routes that are available are different products with different arithmetic.

    Nobody explains this to people before they have already deposited somewhere, which is precisely why it costs them money. So here is the structure, the actual published numbers, and what changes about position size when you take one route rather than another.

    How to Trade XAUUSD in US Accounts, and Why the Order Gets Rejected

    Start with a distinction that sounds pedantic and is worth real money.

    XAUUSD as it appears on most international platforms is a contract for difference or a rolling spot contract on gold. You never receive metal. You hold a leveraged bilateral contract with your broker whose value tracks the gold price, and you close it for cash. That is one product.

    The United States regulates that product as a commodity transaction, not a currency one, and that single classification decides everything else. The Commodity Exchange Act, in section 2(c)(2)(D), covers leveraged or margined retail transactions in commodities and treats them as though they were futures contracts, which means they must be traded on a registered exchange through registered intermediaries. There is an exception, and the exception is where gold falls out: the transaction escapes that treatment only if it results in actual delivery within 28 days. The CFTC restated this in its final interpretive guidance on actual delivery of 24 March 2020, where it describes the 28 day limit and what possession and control have to mean for delivery to count.

    A rolling XAUUSD position does not deliver anything to you in 28 days. It rolls. So it does not fit the exception, and it therefore has to live on an exchange, and a retail contract for difference is not an exchange product. That is the whole mechanism. The rejection on the screen is that paragraph, expressed as an error message.

    The confusion comes from the currency side, where a genuinely different regime applies. The CFTC’s retail foreign currency rules, published on 10 September 2010 and effective 18 October 2010, created a registration category called the retail foreign exchange dealer and allow leveraged off exchange trading in currency pairs through those registered firms. EURUSD is a currency pair. XAUUSD, despite the ticker looking identical in shape, is not. The rules that let an American trade the first one do not extend to the second.

    What the Same Rulebook Says About Size

    While we are inside those rules, there are two published numbers worth carrying away, because they tell you what a regulated venue is expected to look like.

    The first is the security deposit floor. Under the final retail forex rules, the Commission set minimum security deposits of 2 percent of notional value for major currencies and 5 percent for all other currencies, with the National Futures Association authorised to set the specific levels inside those parameters. Two percent is 50 to 1. Five percent is 20 to 1.

    The second is the capital requirement on the firm itself. A futures commission merchant or retail foreign exchange dealer must hold minimum net capital of 20 million dollars, plus 5 percent of the amount by which its liabilities to retail forex customers exceed 10 million dollars. That is the bar for being allowed to sit on the other side of retail trades in that market.

    Chart on how to trade XAUUSD in US accounts, comparing the notional exposure of a full sized and a small sized gold contract against a ten thousand dollar account
    How to trade XAUUSD in US markets means choosing a contract size first: the same account carries very different exposure depending on which contract it uses.

    Run those percentages against an account and the picture sharpens. I calculated the following for this article on the stated assumption of a 10,000 dollar account. At the 2 percent floor, that account can carry 500,000 dollars of notional value. At the 5 percent floor, it can carry 200,000 dollars. Those are ceilings on what the rules permit, not suggestions about what is sensible, and the gap between those two ideas is where most accounts are lost. I have written about that gap at length in how much to risk per trade, and none of what follows replaces it.

    The Routes That Actually Exist

    So what is available. Three broad routes, and they are genuinely different instruments rather than three doors to the same room.

    Exchange traded gold futures. This is the direct analogue. Gold futures trade on a registered United States exchange through a registered futures commission merchant, and the contract is standardised. The full sized gold contract is 100 troy ounces and there is a smaller contract at 10 troy ounces. Using 3,000 dollars an ounce purely as a round reference number for the arithmetic rather than as a market quote, the full contract represents 300,000 dollars of notional value and the smaller one 30,000 dollars, a factor of ten between them. For a 10,000 dollar account those two contracts are not variations on a theme. One of them is thirty times the account and the other is three times it.

    Gold backed exchange traded products. Bought and sold like a share through a securities brokerage. No leverage by default, no expiry, no roll, and no margin mechanics to manage. It is a different exposure with different costs, and it is the route that has almost nothing in common with what a XAUUSD trader is used to doing.

    Physical metal. Bought outright, delivered, stored. The 28 day delivery test is satisfied trivially because you actually receive the gold. It is an ownership decision rather than a trading one.

    What is not on the list is the thing people go looking for after the rejection: an offshore firm that will accept a United States resident and offer the familiar XAUUSD ticker at high leverage. Those firms exist and they will take the deposit. What you give up is every protection the paragraphs above describe, starting with the capital requirement and ending with any practical route to recovering money from a firm outside the jurisdiction. The reader from Ohio was one wire transfer away from that, and the screenshot that started it looked exactly like a technical fault.

    What Changes About the Way You Trade

    Suppose you take the futures route. Four things change, and none of them are about analysis.

    Size stops being continuous. On a contract for difference platform you can trade 0.03 lots. On a futures exchange you trade one contract or none. The smallest available position becomes the question, and if the smallest available position is too large for your account then the honest answer is that the account is not yet the right size for the instrument, not that you should stretch. How much money to start trading gold is worth reading with this specifically in mind.

    Contracts expire. A rolling XAUUSD position can be held indefinitely. A futures contract has a delivery month, and holding one into that month has consequences a retail account does not want. Positions have to be rolled deliberately, on a date you know in advance.

    Margin is set by a clearing house, and it changes. It is published, which is an improvement on the bilateral version, but it moves, typically upward, in exactly the volatile conditions in which you would least like it to move.

    The cost structure is different. Commission per contract and exchange fees replace a spread that was buried in the quote. Neither arrangement is inherently cheaper. They are visible in different places, and the futures version is easier to measure precisely because it is itemised.

    What does not change is the part that decides whether you survive. The instrument determines your minimum size, your expiry and your fee structure. It does not determine your risk per trade, your stop discipline or whether you can sit out a session. Those were always the constraint, and they remain the constraint on a different venue. Risk management in gold trading is the piece that holds all of this together, and it applies identically whichever route you end up on.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting your account when the instrument or the venue changes underneath you. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    How to trade XAUUSD in US accounts, in one sentence?
    In the familiar leveraged off exchange form, generally you cannot, because United States rules treat leveraged retail gold as a commodity transaction that must go through a registered exchange unless it delivers metal within 28 days; the available routes are exchange traded gold futures, gold backed exchange traded products, or physical metal.

    Why can Americans trade EURUSD but not XAUUSD the same way?
    Because currency and gold sit under different parts of the law. The 2010 retail forex rules created a registered dealer category for off exchange currency trading. Gold is a commodity, not a currency, so it falls under the retail commodity transaction provisions instead, and those require an exchange.

    Is the 28 day rule about my holding period?
    No. It is a test applied to the contract, not to you. It asks whether the arrangement results in actual delivery of the metal, with possession and control passing to the buyer, within 28 days of the transaction. A rolling cash settled position does not, which is why it does not qualify.

    Can I just use an offshore broker?
    Firms outside the jurisdiction will often accept the account. What you are giving up is the capital requirements, the segregation rules and any realistic route to recovering funds if the firm fails or simply stops answering. That is a large amount of protection to trade away for a familiar ticker.

    Which route is best for a small account?
    That depends on facts about your situation that this article cannot see, and it is a question for a licensed professional in your jurisdiction rather than for a blog. What this article can tell you is the arithmetic: a smaller contract carries roughly a tenth of the notional exposure of the full sized one, and no entry, stop or target discussed should be treated as a signal.

    Where did the numbers in this article come from?
    The 28 day actual delivery test and the description of CEA section 2(c)(2)(D) come from the CFTC final interpretive guidance of 24 March 2020, linked above. The 10 September 2010 publication date, the 18 October 2010 effective date, the 2 percent and 5 percent security deposit floors and the 20 million dollar capital requirement plus 5 percent of customer liabilities above 10 million dollars come from the CFTC retail foreign currency page and its published question and answer document, also linked. The notional value figures were calculated for this article from the contract sizes and a 3,000 dollar an ounce reference figure chosen for legibility, not taken from any market quote.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily XAU/USD analysis on Telegram with the level and the risk written down before the trade, losing days included. There is a free survival sheet for anyone who wants the capital protection side on one page, and an optional kit for people who want the full process. No profit is promised anywhere, because nobody can promise one.

    If the venue question is live for you, how to open a gold trading account covers the practical steps and the checks worth making first, what is leverage in gold trading explains what those security deposit percentages actually do to an account, and the author page explains who writes this and why.

    About the author. Matthew writes Gold Empire. He spends most of his time on the survival end of this job, the part where an account is still there in twelve months, and he has a particular interest in the rules people only discover after they have already sent money somewhere. Nothing here is a recommendation, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about the regulatory structure of gold trading for retail clients in the United States. It is not financial advice, not legal advice, not tax advice and not a recommendation to buy, sell or use any product, venue or firm. It is a summary written for general readers and is not a statement of the law; rules change, they depend on your residency, your status and the legal entity holding your account, and only a licensed professional can tell you what applies to you. The regulatory figures are quoted from the CFTC sources linked in the text, which were checked and reachable at the time of writing. The notional value figures were calculated for this article from clearly stated assumptions, and the 3,000 dollars an ounce reference used in the arithmetic is a round number chosen for legibility rather than a market quotation. Leveraged trading in gold carries a high risk of losing money rapidly, and a majority of retail accounts lose money. Past behaviour of any market does not indicate future behaviour. No entry, stop or target discussed should be treated as a signal.


  • How to Modify a Trade on MT4 Without Making It Worse

    How to Modify a Trade on MT4 Without Making It Worse

    There is a button in MetaTrader 4 that has cost more accounts than any indicator ever will. It is not a dramatic button. You right click an open position, choose Modify or Delete Order, and a small window appears with two fields in it. That is the whole feature. And yet how to modify a trade on mt4 is one of those questions where the mechanical answer takes ninety seconds and the important answer takes the rest of this article, because the platform will happily let you do something that quietly doubles what you stand to lose.

    So I am going to cover both. First the mechanics, properly, including the two things that go wrong and the error message nobody explains. Then the arithmetic of what each kind of modification actually does to your risk, which is the part that decides whether you are still trading in a year. No gold price appears anywhere in this article, and nothing here is a signal.

    How to Modify a Trade on MT4: What the Feature Actually Is

    Start with a definition, because the word modify is doing a lot of work and MetaQuotes is precise about it. In their own documentation, managing a trade position consists of opening a position, modifying a position, placing pending orders, modifying or deleting pending orders, and closing a position. And MetaQuotes defines modifying a position as changing the Stop Loss and Take Profit levels attached to the open position.

    Read that again, because it is narrower than most people assume. Modifying a position in MT4 changes two things and only two things: where your stop sits and where your target sits. It does not change your entry price, which has already happened. It does not change your lot size, which is fixed at the moment of execution. If you want a different size, you are not modifying, you are closing part of the position or opening another one, and those are different operations with different consequences.

    That distinction matters more than it sounds, and I will come back to it, because almost every expensive mistake in this area comes from someone changing the stop when what they actually wanted was a different size.

    The mechanical steps

    In the Terminal window at the bottom of the platform, on the Trade tab, you will see your open positions. Right click the one you want and choose Modify or Delete Order. You can also double click the Stop Loss or Take Profit cell on that row, which opens the same window.

    The order window appears with Type set to Modify Order. You will see two fields, Stop Loss and Take Profit, each with a Copy As button next to it that fills in the current market price so you can adjust from there rather than typing a full number. Enter the levels you want and click the long Modify button in the middle. If the field is greyed out or the button does nothing, that is not a bug, and the next section explains it.

    The same window handles pending orders, with one addition: for an order that has not triggered yet you can also change the price at which it triggers and its expiry, because nothing has been executed and everything is still adjustable. The four pending order types, Buy Limit, Buy Stop, Sell Limit and Sell Stop, are all editable in this way until the moment they fill, at which point they become positions and the narrower rules above apply.

    The two things that go wrong

    The Modify button will not activate. The most common reason is that you have not actually changed anything yet, since MT4 keeps the button inert until the values differ from what is already set. Type a different number and it wakes up.

    You get an invalid stops error. This is the one that generates confusion, and it is not your platform misbehaving. Brokers set a minimum distance from the current price inside which a stop or a target may not be placed, and if you try to put your level closer than that, the server rejects the modification. The distance is a broker setting rather than a platform setting, it differs between firms and between instruments, and it can widen during volatile periods precisely when you most want to move something. Which is worth knowing in advance: the ability to place a stop very close to price is not a feature you are guaranteed at the moment you need it.

    The Modification That Is Almost Always Fine

    Moving a stop in the direction of your entry, tightening it, reduces the money at risk on the position. Nothing about that is dangerous to your account arithmetic. You have decided to accept a worse chance of the trade working in exchange for a smaller loss if it does not, and whether that trade off is wise depends on your plan rather than on the platform.

    The specific case worth naming is moving the stop to your entry price, which turns the position into one that can no longer lose money at the broker level, ignoring spread and slippage. It has a name and its own considerations, and I have written about them separately in what a break even stop in gold trading is. The point here is only that it belongs to the safe direction, arithmetically speaking.

    Adjusting a Take Profit is similarly unremarkable in risk terms. Whether you should is a question about your method. It cannot increase your loss.

    The Modification That Ends Accounts

    Now the other direction, and this is the whole reason the article exists.

    Price moves against your open position. It approaches your stop. You look at the chart and a reason arrives, fully formed and entirely convincing, that the stop is a little too tight, that the level is about to hold, that a few more points of room is all this needs. So you open Modify Order and drag the stop further away.

    Here is what you have just done, in numbers. You sized that position so that hitting the stop would cost you a fixed amount, call it one percent of the account. Your lot size is fixed, and MT4 will not change it in this window. Money at risk equals lot size multiplied by the distance to the stop. Move the stop twice as far away and the lot size does not move to compensate, so the money at risk doubles. The risk multiplies by exactly the factor you widened by.

    Chart for how to modify a trade on mt4, showing that widening a stop from S to 3S triples the risk on the trade from 1 percent to 3 percent of the account
    How to modify a trade on mt4 without changing the risk you agreed to: the lot size does not move when the stop does.

    Widen by half and one percent becomes 1.5 percent. Double the distance and it becomes two percent. Triple it and it becomes three percent, three times the loss you agreed to when you had a calm view of the situation.

    And it compounds within a single trade, which is the part people miss. Two drags of fifty percent each are not a hundred percent more risk. They multiply: 1.5 times 1.5 is 2.25. You will have taken a one percent risk and turned it into 2.25 percent while feeling, both times, that you were making a small adjustment.

    The second bar in that chart is the one worth sitting with. Lose ten trades at the original one percent over a year and you are down to 90.44 percent of the account. Lose ten trades that each became 2.25 percent through this exact habit and you are down to 79.65 percent. Same ten losing trades, same method, same market. The gap is 10.79 percentage points of your capital, and every point of it was created by a button rather than by the market.

    Recovery is not symmetric either, which is the quiet part of the arithmetic. Losing 2.25 percent requires 2.30 percent to get back to level, because you are now earning on a smaller base. That gap is trivial at small numbers and brutal at large ones: a 20 percent loss requires 25 percent to recover, and a 50 percent loss requires 100 percent. Every widened stop moves you a little further along that curve.

    Why the Reasoning Feels So Convincing

    I want to be fair to the impulse, because dismissing it as indiscipline is both rude and useless.

    The reason it feels right is that it is occasionally correct. Sometimes price does turn around just past where your stop was, and the trade you widened for goes on to work. That is a genuine outcome and it happens often enough to teach you the wrong lesson very effectively. The problem is not that widening never works. The problem is that it pays out immediately and charges you later, so the feedback arrives in the wrong order for learning anything true.

    There is also a structural point. At the moment you are considering the modification, you are the worst informed you have been about this trade all day. You are holding an open loss, which is a poor state for judgement, and you are looking at price rather than at your plan. The version of you who set that stop had none of those handicaps. The modification is not new analysis. It is a proposal to overrule a calmer person using worse information.

    The honest test, and it costs nothing: if you were flat right now, with no position and no attachment, would you enter this trade at this price with the stop at the new level? If the answer is no, the modification is not a trading decision. It is a way of not accepting a loss that has already happened.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting your account from the small decisions that quietly enlarge a loss, including a rule for when a stop may and may not be moved. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    A Rule Worth Writing Down Before You Need It

    The useful protection is not willpower, it is deciding the policy while nothing is at stake. Mine is three lines and it fits on a card.

    A stop may move toward the entry at any time, and away from it never. Tightening reduces risk and can be done on judgement. Widening increases it and is simply not available, so there is no decision to make in the moment.

    If the stop looks wrong, the position was sized wrong. The correct response to a stop that feels too tight is a smaller position with a wider stop, decided before entry. That is a sizing exercise, and it belongs in how to calculate lot size for gold and forex rather than in the Modify window.

    Set the stop when you open the trade, not afterwards. MT4 lets you attach both levels in the order window at entry, while you still have no position and no opinion about being right. A stop chosen then is a plan. A stop chosen while an open trade is moving against you is a reaction.

    If you want the reasoning behind where the level goes in the first place, where to place a stop loss on XAUUSD covers it, and how to manage a gold trade after you enter covers the legitimate things you can do to a position that is already open, of which widening the stop is not one.

    Frequently Asked Questions

    How do I modify a trade on MT4 in one line?
    Right click the position on the Trade tab of the Terminal window, choose Modify or Delete Order, enter new Stop Loss or Take Profit values, and click Modify. That is the entire feature, and in MetaQuotes’ own terms modifying a position means changing those two levels and nothing else.

    Can I change the lot size of an open position?
    No. Size is fixed at execution and the Modify window will not touch it. You can close part of the position, which reduces size, or open a separate position, which is a new trade with its own risk. Confusing these with modification is how a stop gets widened when a smaller position was what was needed.

    Why does MT4 say invalid stops when I try to modify?
    Your broker enforces a minimum distance between the current price and any stop or target, and your level is inside it. It is a server side rule rather than a platform limitation, it varies by firm and instrument, and it can widen when the market is busy. Place the level further away or wait for the constraint to ease.

    Is it ever right to widen a stop?
    As a general policy for a retail account, no, and the arithmetic is why. Widening does not buy the trade more time for free. It multiplies your risk by the factor you widened by, because the lot size does not change with it. If a wider stop is genuinely correct for the setup, the position should have been smaller from the start.

    Does modifying a trade cost anything?
    There is no charge for the modification itself. The cost is entirely in what the new levels do to your risk, plus the ordinary costs of the position such as spread and any overnight financing, which continue regardless of where your stop sits.

    Where did the numbers in this article come from?
    The definition of modifying a position and the pending order types are from MetaQuotes’ own MetaTrader 4 documentation, linked above. Every percentage is my own arithmetic on assumptions stated in the text: a fixed lot size, an initial risk of one percent, and the stop actually being reached. They are not measurements of any market or of anyone’s results.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily gold analysis with the reasoning attached, losing days included, and an optional Kit for people who want the survival side written down in one place. There is no promise of a return here, because nobody honest can make one.

    Knowing which buttons enlarge a loss is a survival topic rather than a technical one, which is why it sits under risk management in gold trading. If you are still setting the platform up, how to add gold to MetaTrader 4 comes before this one, and how much to risk per trade is where the one percent in the arithmetic above is decided in the first place.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He is more interested in the mechanics that quietly drain accounts than in the setups that fill timelines. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about a platform feature and about the arithmetic of position risk. It is not investment advice, not a recommendation of any broker, platform or account type, and not a solicitation to trade. Platform behaviour, minimum stop distances and order handling rules differ by broker, by instrument and by jurisdiction and change without notice, so verify the current terms with your own firm. The definition of modifying a position and the description of pending order types are taken from MetaQuotes’ published MetaTrader 4 help on trade positions and order types. Every percentage in this article is my own arithmetic on the stated assumptions, chosen to illustrate the method rather than to describe any real account. Trading gold carries a real risk of losing money, including more than you deposit in some account types. No gold price level is quoted anywhere here. Nothing accounts for your personal circumstances, and no entry, stop or target discussed should be treated as a signal. If you are unsure, speak to someone properly qualified in your own jurisdiction before you risk anything.


  • How to Add XAUUSD in MT5, and What You Just Added

    How to Add XAUUSD in MT5, and What You Just Added

    You have installed the platform, the account is funded, and gold is not in the list. So the first question is the practical one, how to add xauusd in mt5, and it has a short answer that takes about fifteen seconds.

    The second question is the one that actually matters, and almost nobody asks it. Having made the symbol appear, what exactly have you added? Because the answer is set by your broker rather than by any standard, and getting it wrong is one of the more expensive ways a new gold account ends.

    This article does both. The fifteen seconds first, then the screen you should read before you place a single order on it.

    How to Add XAUUSD in MT5, the Short Version

    MetaTrader 5 does not show every instrument your broker offers. It shows a working subset in the Market Watch window, and gold is frequently not in the default list.

    The route is documented in the platform’s own Market Watch help page. Open Market Watch, then open the symbol manager, which the documentation describes as the command to Open the window for managing symbols with the command Symbols of the context menu. That gives you the full list of what your broker actually offers rather than what is currently displayed.

    In that window, the documentation notes that you can use the filter at the top of the window. Type the first letters of the symbol name or description in it. Type gold, or type XAU. Then, as the help puts it, Double-click on a symbol name to toggle it into the Market Watch list, or use the Show button.

    Gold now appears in Market Watch and you can open a chart from it. That is the whole of the mechanical answer.

    One detail worth knowing while you are in there, from the same page: If there are open positions or pending orders for the financial instrument, or when its chart is open, the instrument cannot be hidden. If a symbol refuses to disappear later, that is why, and it is not a fault.

    Why Gold Was Missing, and Why It Might Be Called Something Else

    Three ordinary reasons cover almost every case.

    The first is simply that the default list is short. Brokers ship a small Market Watch so the window is usable, and the full catalogue sits behind the symbol manager. Nothing is wrong.

    The second is naming. There is no rule that gold must be called XAUUSD. Depending on the firm you may find GOLD, or XAUUSD with a suffix attached, and the suffix is the part to pay attention to. This is why searching the description rather than the exact ticker is the more reliable move.

    The third is the account type. A demo and a live account at the same firm can carry different instrument sets, and some symbols are restricted by jurisdiction or by account tier. If gold genuinely is not in the symbol manager at all, that is a question for the broker rather than a platform problem.

    A fourth possibility is not a problem at all. Outside trading hours the symbol exists but sits still, which people sometimes read as a broken feed. Gold trades nearly around the clock on weekdays and stops at the weekend, so a frozen quote on a Sunday is the market being shut.

    The Screen to Read Before You Trade It

    Here is where the survival part of this article begins.

    Once the symbol is in Market Watch, the same help page describes reading its trading conditions: click Specification in the context menu of the Market Watch window. That panel states the contract size, the execution mode, the margin requirement and the commission your broker has set for your account.

    Read it once, properly, because those values are not standard across the industry. They are settings. Two firms can offer something called XAUUSD where one full lot means different quantities of metal, and the platform will let you trade either of them with identical confidence.

    Contract size is the line that matters most, and the next section is entirely about why.

    Chart supporting how to add xauusd in mt5, showing the loss at the stop as a share of a 5,000 account at 0.01, 0.06, 0.10, 0.25 and 0.50 lot on a 100 ounce contract
    How to add xauusd in mt5 is the easy half. The contract size on the specification screen is what decides whether 0.10 lot is a small number or a large one.

    What the Contract Size Does to Your Risk

    Take the most common retail convention, where one full lot of gold is one hundred ounces. Every figure below is computed from that assumption, and none of them depends on the price of gold.

    At 0.01 lot you hold one ounce, so a move of one dollar an ounce is worth one dollar to your account. At 0.10 lot you hold ten ounces and the same move is worth ten dollars. At 1.00 lot you hold one hundred ounces and it is worth one hundred dollars.

    The distance between the smallest and largest of those is a factor of one hundred. The distance on screen between them is two keystrokes.

    That is the whole hazard, and it explains a category of account failure that looks mysterious from outside. Nobody intends to trade a hundred times their planned size. They copy a lot figure from a tutorial written for a broker whose contract size was different, or they assume the gold contract behaves like the currency pairs they practised on, and the position is wrong before the chart has been considered at all.

    Note that this has nothing to do with being right about direction. A correctly analysed trade in the correct direction at a hundred times the intended size is still a serious problem, because the loss you had planned for is now a loss you cannot absorb.

    Turning the Specification Into an Order Size

    Once you have read the contract size, sizing is arithmetic rather than judgement.

    Assume a five thousand account, a limit of one percent of it on any single trade, so fifty, and a stop eight dollars an ounce away from entry. On a one hundred ounce lot convention, one full lot would lose eight hundred at that stop. Fifty divided by eight hundred gives 0.0625 lots.

    Round that down, never up, so 0.06 lot. Rounding down leaves you slightly inside your limit. Rounding up puts you outside it, and the habit of rounding up is how a one percent rule quietly becomes something else.

    Compare that with clicking 0.10 because it looks like a small, round, harmless number. At 0.10 lot the same stop costs eighty, which is 1.6 percent of the account, or 1.6 times the risk you decided on. That is not a catastrophe on one trade. Repeated across a losing run it is the difference between a drawdown you recover from and one you do not.

    Higher leverage does not change any of this. Leverage sets the margin your broker holds, not the money you lose at your stop. The two get confused constantly, and the confusion is expensive. For context on where the limits come from, the ESMA product intervention measures of 27 March 2018 capped retail leverage on gold at 20:1 in that regime and required negative balance protection.

    The Suffix Trap

    One specific version of this is worth naming, because it catches people who have done everything else right.

    Where a broker lists several variants of gold, the variants can differ in contract size, in execution mode, in commission and in minimum size. They are different products wearing nearly the same name.

    The failure is undramatic. You read the specification carefully on one variant, size correctly from it, then some weeks later add a chart from a different variant and size it from what you learned the first time. The arithmetic was right. It was applied to the wrong contract.

    The defence is to check the specification of the exact symbol on the exact chart you are about to trade, and to keep only the variant you actually use in Market Watch. Hiding the rest is the same double-click that showed them.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to sizing a gold position from the contract specification rather than from a number you copied, including the arithmetic used on this page. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently Asked Questions

    How to add xauusd in mt5 in one sentence?
    Open Market Watch, open the Symbols window from the context menu, filter for gold or XAU, then double-click the symbol to show it in the list.

    I cannot find XAUUSD anywhere in the symbol list.
    Search for the description rather than the ticker, because your broker may list gold under a different name. If nothing appears at all, the instrument may not be offered on your account type or in your jurisdiction, and that is a question for the broker.

    Why does the price never move after I add it?
    Most often the market is closed, which on gold means the weekend. If quotes stay frozen during normal weekday hours, check the connection status and then the symbol’s trading sessions in its specification.

    Does MT5 work the same way as MT4 for this?
    The idea is the same, a symbol list you can add to, but the windows and menus differ, so instructions written for the older platform will not match exactly. The specification habit described here matters equally on both.

    Is 0.01 lot always one ounce of gold?
    No, and this is exactly the assumption to avoid. One ounce at 0.01 lot follows from a one hundred ounce contract, which is common but is a broker setting rather than a rule. Read the contract size on the specification screen for the symbol you are about to trade.

    Where did the numbers in this article come from?
    The platform instructions are quoted from the MetaTrader 5 Market Watch help page linked above, and the leverage cap and negative balance protection from the ESMA measures also linked above, both checked live before publication. Every other figure is computed from the stated assumptions, a one hundred ounce lot convention, a five thousand account, a one percent risk limit and an eight dollar an ounce stop. None of them depends on the price of gold.

    Gold Empire is free to follow. Daily XAUUSD analysis with the reasoning stated before the trade rather than after it, on Telegram, and a free survival sheet for anyone who wants the capital protection material in one place. There is an optional Kit for people who want the whole method. No profit promises, and nothing here is a signal service.

    If you want the rest of this thread: risk management in gold trading is the pillar this article sits under, how to add gold to MetaTrader 4 covers the same job on the older platform, and how to calculate lot size for gold turns the contract size into an order you can actually place. More about who writes this is on the author page.

    About the author. Matthew writes Gold Empire. He spends most of his time on the unglamorous half of this business, the part concerned with still being here next year, and he has never met an account that was lost because the platform was hard to configure, only ones lost because nobody read what they had configured. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.

    Disclaimer: This article is general educational content about platform configuration, contract specifications and position sizing in retail gold trading. It is not financial advice, not investment advice and not a recommendation to buy, sell or use any product, venue or firm. Platform behaviour and instrument settings vary by broker and may change, and regulatory wording is quoted from the source linked in the text. Trading leveraged products carries a substantial risk of loss and most retail accounts lose money. All figures are illustrative calculations from the stated assumptions, not predictions, and not claims about any past or future performance.