GOLD EMPIRESurvive First, Then Grow

Author: Matthew

  • Micro Gold Futures vs XAUUSD: Which One Fits a Small Account?

    Micro Gold Futures vs XAUUSD: Which One Fits a Small Account?

    A member wrote to me in the spring with a question I get in some form most months. He had four thousand dollars, he wanted to trade gold, and a video had told him futures were the professional route while CFDs were for beginners. Was that true, and should he move? The honest answer took longer than he expected, because micro gold futures vs XAUUSD is not a question about which instrument is more respectable. It is a question about contract size, and contract size is the thing that decides whether a four thousand dollar account survives its first bad week.

    So let me do this the way I would do it on paper. What each instrument actually is, what one move is worth in each, and what account each one quietly requires before the arithmetic stops working against you.

    Every calculation below is mine, from assumptions I state as I go. The contract sizes and the market figures come from the regulator’s own report, linked where I use them. There are no gold price levels anywhere in this article, and nothing here is a recommendation to trade.

    Micro gold futures vs XAUUSD, stated plainly

    Gold futures are exchange traded contracts. The full size gold contract on COMEX covers 100 troy ounces. There is also a micro version covering 10 troy ounces, exactly one tenth. Those two sizes are not marketing copy, they are in the Commitments of Traders report published by the CFTC, which prints “contracts of 100 troy ounces” for gold and “contracts of 10 troy ounces” for micro gold next to the open interest for each.

    XAUUSD is something different. It is a contract for difference, an agreement with your broker that settles the change in the gold price. Nothing is delivered and no exchange stands in the middle. The common retail convention is that one standard lot is also 100 ounces, with a minimum size of one hundredth of a lot, which works out at one ounce. I want to be careful here: that convention is set by each broker rather than by an exchange, so it is an assumption in what follows and it is the one thing on this page you should check against your own account before relying on it.

    That is the whole structural difference. One is an exchange contract in fixed sizes, the other is a private agreement that can be cut much finer.

    The number that decides everything: what one dollar of gold is worth to you

    Forget the branding and price a single move. If gold moves one dollar an ounce, the full size futures contract moves one hundred dollars, because it holds a hundred ounces. The micro contract moves ten dollars. One hundredth of a CFD lot, under the convention above, moves one dollar.

    Those three numbers are the entire argument. They are not opinions about which venue is more serious, they are multiplication.

    Now attach a stop to them. Suppose you decide a trade is wrong if gold moves ten dollars an ounce against you. That is a stop distance, not a prediction, and I am choosing a round number to make the arithmetic legible. At that distance the full size contract puts a thousand dollars at risk, the micro contract a hundred dollars, and the one ounce CFD position ten dollars.

    Here is where it stops being abstract. The rule I keep coming back to, and the one behind nearly everything on this site, is that no single trade should cost more than about one per cent of the account. Run that backwards and each instrument tells you the account it expects:

    • Full size gold futures, one thousand dollars at risk, implies an account of about one hundred thousand dollars.
    • Micro gold futures, one hundred dollars at risk, implies an account of about ten thousand dollars.
    • One ounce on a CFD account, ten dollars at risk, implies an account of about one thousand dollars.

    That is the answer to my member’s question, and it has nothing to do with which instrument is professional. With four thousand dollars, the smallest available position in full size futures would have been a twenty five per cent risk on a single trade. The micro contract would have been two and a half per cent, still more than I would want. The CFD route was the only one where his smallest possible position was smaller than his risk budget.
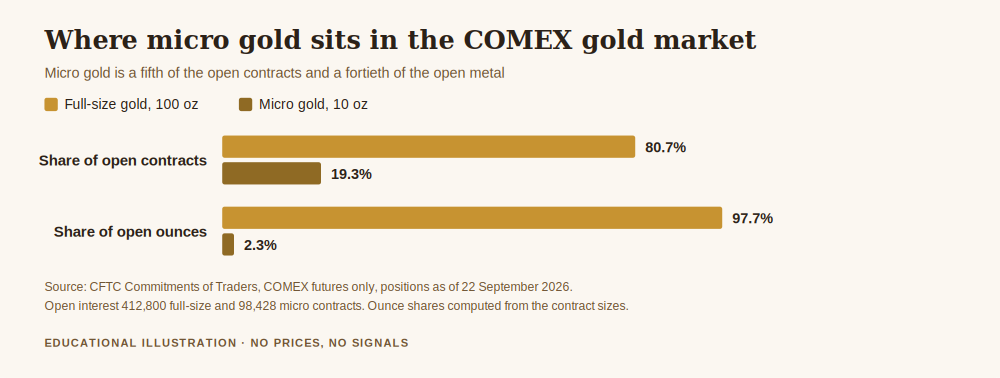
    Micro gold futures vs XAUUSD, chart showing micro gold holds 19.3 per cent of open COMEX gold contracts but only 2.3 per cent of the open ounces
    Micro gold futures vs XAUUSD, in market share: the micro contract is where the small accounts are, and it holds very little of the actual metal.

    The chart is worth a moment because it shows the same point from the market’s side. In the CFTC report for positions as of 22 September 2026, there were 412,800 full size gold contracts open and 98,428 micro contracts. So micro gold is 19.3 per cent of the open contracts, nearly a fifth, which sounds substantial. Convert those contracts into metal and the picture changes: 412,800 contracts of 100 ounces is 41.28 million ounces, while 98,428 contracts of 10 ounces is 984,280 ounces. The micro contract holds 2.3 per cent of the open gold.

    A lot of participants, very little metal. That is the signature of a contract built for small accounts, and it is the clearest evidence I know that trading gold in small size is ordinary rather than second class.

    What the CFD side gives you, and what it charges for it

    If finer sizing were the only consideration, CFDs would win for every small account and the article would end here. It is not, and the differences are worth stating without taking sides.

    The first is who your counterparty is. With futures, you face a clearing house through a broker, and the contract specification is set by the exchange and reported to a regulator. With a CFD, you face your broker. That is not automatically sinister, but it means the terms are the broker’s terms, and it means the quality of the firm matters more than it does on an exchange. I have written separately about what happens if your forex broker goes bust, which is the question this leads to.

    The second is leverage, and here the regulation is explicit. Under the product intervention measures agreed by ESMA, the European Securities and Markets Authority, retail CFD leverage on gold is capped at 20 to 1, which is the same as saying you must post 5 per cent of the position’s value as margin. The same measures set a margin close out at 50 per cent of required margin and require negative balance protection on a per account basis. Those rules apply to retail clients of EU regulated firms, so whether they cover you depends on where your broker is authorised.

    That same ESMA announcement contains the number I would put on the wall of anyone starting out. The national regulators found that between 74 and 89 per cent of retail accounts typically lose money on CFDs, with average losses per client ranging from 1,600 to 29,000 euros. Three quarters to nine tenths. The instrument you pick moves that figure far less than the size you trade and the risk you take per trade.

    The third difference is the running cost. A futures position has no overnight financing charge in the way a CFD does, because the cost of carry is already inside the futures price. A leveraged CFD held overnight is financed, and that financing tracks short term dollar interest rates. In the Federal Reserve’s H.15 release dated 1 October 2026 the effective federal funds rate was 3.88 per cent, so a position held for 30 days carries roughly 0.32 per cent of its notional value in financing before any broker markup. That is small for a day trade and material for a position you intend to hold for months.

    Choosing without pretending the choice is bigger than it is

    Put the three facts side by side and the decision mostly makes itself.

    If your account is small enough that a micro futures contract would be more than one or two per cent of it on a sensible stop, you do not have a choice to agonise over. Trade the instrument that lets you size properly, which for most accounts under ten thousand dollars means a CFD account where you can deal in single ounces. The alternative is not “trading futures like a professional”, it is taking a position four or five times larger than your own rules allow, which ends the same way every time.

    If your account has grown past the point where micro futures fit inside your risk budget, the futures route becomes genuinely attractive for the structural reasons: an exchange contract, a published specification, a clearing house, no financing charge layered on top. Many people make that move, and it is a reasonable one.

    What I would not do is make the move early in order to feel more serious. The size of your position is the only variable in this article that has ever closed an account, and it is the one you control on either venue.

    If you are at the stage of asking this question at all, how to trade gold with a small account and how much money to start trading gold are the two pieces that sit either side of it, and what leverage actually is in gold trading covers the mechanism that makes contract size matter so much in the first place.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes, including how to work out the smallest position your instrument allows before you fund it. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    Is XAUUSD the same as gold futures?

    No. XAUUSD is a contract for difference with your broker that settles the change in the gold price. Gold futures are exchange traded contracts in fixed sizes, 100 troy ounces for the full size contract and 10 for the micro, with a clearing house as counterparty. They track the same metal and behave similarly day to day, but the counterparty, the sizing and the cost structure are different.

    Which is cheaper to hold overnight?

    Futures, usually, because the cost of carry is built into the contract price rather than charged as a nightly financing line. A leveraged CFD is financed at something close to short term dollar rates plus a markup, which was roughly 3.88 per cent a year as a base in the Fed’s H.15 release of 1 October 2026. For a position held a few hours the difference is negligible. For months it is not.

    Can I trade micro gold futures with a small account?

    You can open one, but opening one and sizing it sensibly are different questions. At a ten dollar an ounce stop the micro contract risks about a hundred dollars, so keeping that inside a one per cent risk budget implies an account near ten thousand dollars. Below that the smallest position available is larger than your rules allow, which is the situation worth avoiding.

    Does the 20 to 1 leverage cap apply to me?

    It applies to retail clients of firms authorised in the European Union under the ESMA measures linked above. Other jurisdictions set their own limits, some higher and some lower. Check what your broker is authorised under rather than assuming, because the cap also comes bundled with the margin close out rule and negative balance protection, and those matter more than the leverage number itself.

    Why is micro gold a fifth of the contracts but only a fortieth of the metal?

    Because a micro contract is one tenth the size. A lot of participants holding small contracts produce a high share of the contract count and a low share of the ounces. Both figures are computed from the CFTC report for positions as of 22 September 2026: 412,800 full size and 98,428 micro contracts open.

    Which one should a beginner start with?

    I will not answer that as a recommendation, because the right answer depends on your account size, your jurisdiction and your broker. What I will say is the test to apply: work out the smallest position the instrument permits, multiply it by the stop distance you would actually use, and check the result against one per cent of your account. If it does not fit, that instrument is not yet for you, whatever anybody calls it.

    Where Gold Empire fits

    Gold Empire is a free education channel about surviving in gold before trying to grow in it. Everything here is free to read and free to follow on Telegram. The one optional piece is the survival sheet above, a single page on protecting an account. We do not promise profits, we do not publish account results, and we do not believe anyone can tell you what your account will do. If you want the fuller version of the thinking in this article, risk management for gold trading is the piece everything else here hangs off.

    About the author. Matthew writes Gold Empire. He traded full size contracts on an account that had no business holding them for most of a year, and the habit that saved him was not a better method but a spreadsheet that worked out the smallest position each venue allowed before he funded it. Nothing in this article is financial advice or a recommendation to trade, and no entry, stop or target discussed should be treated as a signal. Trading leveraged gold carries a substantial risk of loss and is not suitable for everyone.


  • Averaging Down in Gold Trading: Why the Habit Feels Safe

    Averaging Down in Gold Trading: Why the Habit Feels Safe

    A member sent me his statement last month with a one line message: “I don’t understand, I was right.” He had been right, in a sense. Gold had come back to where he first bought. The problem was that by the time it got there he had five positions open instead of one, and the account had been closed out two days earlier. Averaging down in gold trading is the most reasonable sounding way I know to lose an account, and the reason it is so hard to argue somebody out of is that it works most of the time.

    That last part is not a figure of speech. I want to show you the arithmetic, because once you see how often it works you understand why nobody believes the warning, and once you see what it costs on the occasion it does not work, you stop needing the warning.

    Everything numerical below is my own calculation from assumptions I state as I go. There are no gold price levels here, and nothing in this article is a recommendation to trade.

    What averaging down in gold trading actually does to the arithmetic

    The tactic is simple. Price goes against the position, so you open another one at the better price. Your average entry improves, so the distance back to break even shrinks. That part is real and it is the whole appeal.

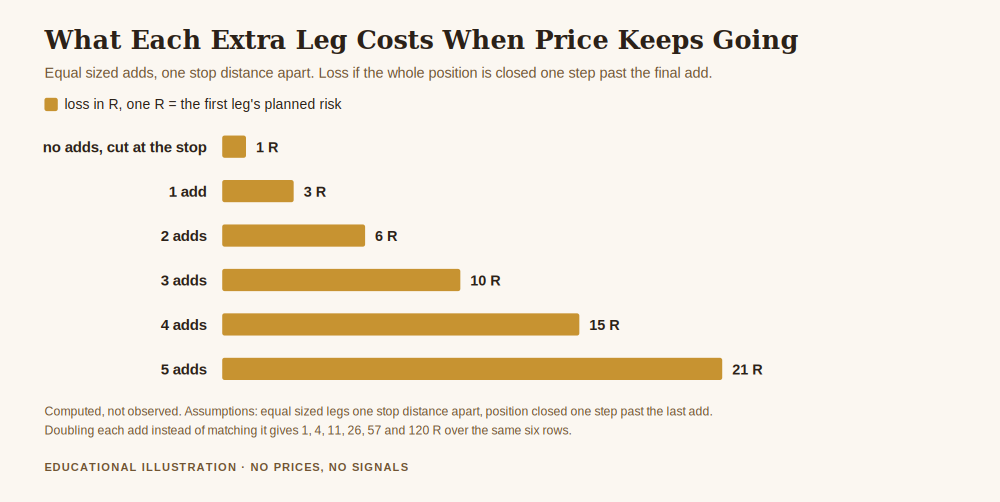
    Measure it properly and it is also where the trouble starts. Let me put distance in units of S, your original stop distance, and money in units of R, the loss the first position alone would take at that stop. One equal sized add, placed one S lower, means the combined position turns profitable while price is still below where you first bought. Two adds and it turns profitable a full S below your first entry. Every add makes the recovery look nearer.

    Averaging down in gold trading, chart of the loss in R rising from 1 R with no adds to 21 R after five equal sized adds
    Averaging down in gold trading, priced: what each extra leg costs if price simply keeps going.

    Now the other column. Close the whole thing one step past your last add and the loss is not one R any more. One add makes it 3 R. Two adds, 6 R. Three, 10 R. Five adds and a 1 R plan has become a 21 R loss. If you double each add instead of matching it, the same six rows run 1, 4, 11, 26, 57 and 120 R.

    That is the trade you are making, stated plainly: you are buying a shorter distance back to break even, and you are paying for it with a loss that grows faster than the number of positions. Nobody would take that deal if it were written on a form. People take it constantly when it arrives one decision at a time.

    Why it feels like it works, and why that feeling is accurate

    Here is the part that most warnings skip, and skipping it is why the warnings do not land.

    Assume, generously, that gold is a coin flip: equally likely to move one step up or one step down. Under that assumption the chance of price touching one step in your favour before running n steps against you is exactly n over n plus one. That is the classic gambler’s ruin result and it is not controversial.

    So if your account can absorb four steps against you, the tactic resolves in your favour 80 per cent of the time. With eight steps of room, 88.9 per cent. And that understates it, because once you have added, the combined position turns green well before price returns to your first entry. Simulating the realistic version, where you add at each step down and close as soon as the whole position shows one R of profit, I get a hit rate of 88.9 per cent with four steps of room and 96.0 per cent with eight.

    Ninety six per cent. The person doing this is not deluded. They are describing their experience accurately.

    The whole game, priced

    A hit rate is not a result, though, and this is where it comes apart. I ran 200,000 independent decisions per rule, with a dealing cost of one tenth of a step per position opened, seed fixed at 20261001 so anyone can reproduce it.

    The plain rule, one position and out at the stop, wins half the time, the average win is 0.90 R and the average loss is 1.10 R. With four steps of grid room the hit rate climbs to 88.9 per cent, the average win drifts down slightly to 0.83 R, and the average loss becomes 10.40 R. With eight steps of room: 96.0 per cent hit rate, 0.80 R average win, 36.80 R average loss.

    Read those three numbers across each row rather than down the column. The hit rate goes up, the win stays roughly the same size, and the loss multiplies. Expected result per decision goes from minus 0.101 R on the plain rule to minus 0.687 R on the widest grid, on a game that was a fair coin flip before costs. The grid does not change your odds of being right. It changes the size of the bill when you are wrong, and it charges you a fresh dealing cost for every position you open on the way down.

    Over a year of 200 decisions the deepest hole tells the same story. The plain rule digs a median worst drawdown of 27 R, with a worst case across 20,000 simulated accounts of 85 R. The eight step grid digs a median of 174 R and a worst case of 683 R.

    Where the close-out actually lands

    There is one more thing the grid does that people do not see coming, and it is not a market risk, it is a contractual one.

    Under the ESMA product intervention measures, retail gold CFD leverage is capped at 20:1 and there is a margin close out rule set at 50 per cent of minimum required margin. Your broker is required to close positions when equity falls below that line.

    Suppose one R is one per cent of your equity and your stop distance is half a per cent of the gold price. Those two assumptions fix the size of a position: a notional of twice your equity, needing ten per cent of equity as margin at the 20:1 cap. With one position open, the close-out sits 95 steps below your entry, which is so far away it may as well not exist. That is why the close-out feels like something that happens to other people.

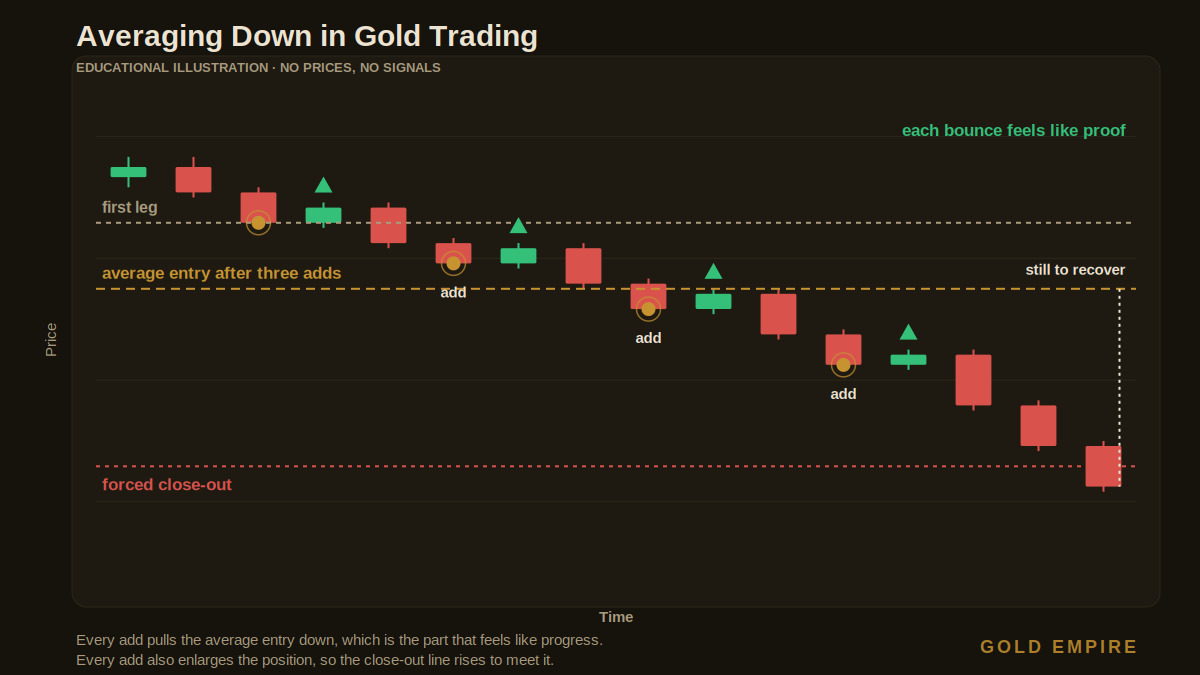
    Add positions and the line walks toward you. With two open it sits at 45.5 steps. With three, 29.3. With four, 21.5. With five open, the forced close-out is 17.0 steps below your first entry, and the arithmetic from the first section says you are already 15 R down by five steps.

    The close-out is not a distant safety net you are drifting toward. It is a line that moves up to meet you every single time you add, and it fires at the broker’s discretion rather than yours. My member’s account did not choose to close. It was closed.

    Averaging down in gold trading, candlestick diagram showing legs added at each step down while the average entry drifts lower and the forced close-out line rises to meet it
    Averaging down in gold trading: every bounce teaches the habit, and every add moves the close-out closer.

    Why the lesson never arrives in time

    Put the hit rate and the loss together and you get the thing that makes this so durable.

    At 96 per cent, the expected number of decisions before the first failure is about 25. Twenty five straight successes. The probability of ten clean in a row is 66.8 per cent, and of twenty five clean in a row, 36.4 per cent. A trader running a wide grid will very likely have a long, quiet, entirely successful run.

    That run is the teacher. By the time the failure arrives, the habit has been reinforced two dozen times, the position sizes have crept up because the tactic has been working, and the account is larger, so the loss is larger too. The lesson always arrives against the biggest position the habit has yet produced. That is not bad luck. It is the structure of the thing.

    What I would do instead

    I am not going to tell you where to put anything, and none of this is a rule for your account. But the survival logic here is not complicated.

    The first thing is to notice that “averaging down” and “scaling into a planned position” are different animals wearing the same coat. If you decided before entering that the position would be built in three parts across a range, and you sized the whole thing so that the full position at its full stop is still one R, that is a plan being executed. If you are adding because price went against you and you did not want to take the loss, that is the grid, whatever you call it in your journal. The test is whether the total risk was decided before the first entry or after the second.

    The second is that the number worth protecting is total open risk, not the risk of any one position. Five positions each sized at one R is a five R decision, and the arithmetic above says it is worse than that, because they are all the same trade in the same instrument moving the same way. I have written about how much to risk per trade and about position sizing for gold, and both of those assume the number they produce is the whole exposure rather than the first instalment of it.

    The third is the uncomfortable one. The reason people average down is almost never analytical. It is that taking the loss means being wrong in a way that is recorded, and adding means the question stays open. A position you are still holding has not lost yet. That is the appeal, and naming it honestly does more than any amount of arithmetic. If this pattern is familiar, why you keep blowing your trading account covers the same reflex from the other direction.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes, including how to count total open risk rather than risk per position. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    Is averaging down always wrong?

    Not always, and the distinction is whether the total risk was decided in advance. A position planned as three instalments across a range, sized so the whole thing at its full stop is still the loss you budgeted, is a plan. Adding because price moved against you and the loss felt unacceptable is the grid described above, no matter how it is labelled afterwards.

    What about averaging down in a long term physical gold holding?

    Different question entirely, because the two risks that drive this article are absent. An unleveraged holding has no margin close out that can end the position on someone else’s timetable, and no dealing cost charged per add on the scale a leveraged account pays. Everything here is about leveraged gold positions.

    Does it help if I use wider stops and smaller positions instead?

    It changes the units rather than the shape. The arithmetic above is written in R and in steps of your own stop distance precisely so it holds whatever those distances are. A grid of five positions is 15 R by the fifth step whether that step is large or small.

    Why does the hit rate in your simulation differ from the gambler’s ruin figure?

    Because they model different exit rules. The n over n plus one figure is for price touching one step above your original entry. The simulation uses the realistic rule, closing when the combined position shows one R of profit, which after a couple of adds can happen while price is still below your first entry. That is an easier target, so the hit rate is higher. Both are stated so you can see which is which.

    Where did the 96 per cent and the 36.80 R come from?

    From a simulation of 200,000 independent decisions under the assumptions stated in the article: price moving one step up or down with equal probability, equal sized adds one step apart, a dealing cost of one tenth of a step per position, and a fixed seed of 20261001. Change any assumption and the numbers change, which is the point of writing them down.

    My broker offers negative balance protection, so what is the worst case?

    Losing the account rather than more than the account, which is a genuine protection and not the one people think they are getting. Negative balance protection caps your loss at what you deposited. It does nothing to make a 36 R loss smaller, and the margin close out will have ended the position long before it becomes relevant.

    Where Gold Empire fits

    Gold Empire is a free education channel about surviving in gold before trying to grow in it. Everything here is free to read and free to follow on Telegram. The one optional piece is the survival sheet above, a single page on protecting an account. We do not promise profits, we do not publish account results, and we do not believe anyone can tell you what your account will do. If you want the fuller version of the thinking in this article, risk management for gold trading is the piece everything else here hangs off.

    About the author. Matthew writes Gold Empire. He spent a long stretch early on treating a losing position as a question that could be kept open by adding to it, and he stopped the year he sat down and worked out what the tactic had actually cost him across all the times it had worked. Nothing in this article is financial advice or a recommendation to trade, and no entry, stop or target discussed should be treated as a signal. Trading leveraged gold carries a substantial risk of loss and is not suitable for everyone.


  • Bearish Divergence in Gold Trading, and What 75 of Them Actually Did

    Bearish Divergence in Gold Trading, and What 75 of Them Actually Did

    Somebody sends me a screenshot most weeks with a note that says bearish divergence in gold trading, price is making a higher high while the oscillator is making a lower one, so the top is in. The pattern in the screenshot is usually real. The conclusion drawn from it usually is not. I went and measured every one of these I could find in fifty eight years of gold data, and the honest answer is more interesting than either the people selling the pattern or the people mocking it would like.

    Everything below is arithmetic I ran myself on the London afternoon gold auction record, with the assumptions written out so you can disagree with them specifically. There are no gold price levels in this article and nothing here is a recommendation.

    What bearish divergence in gold trading actually describes

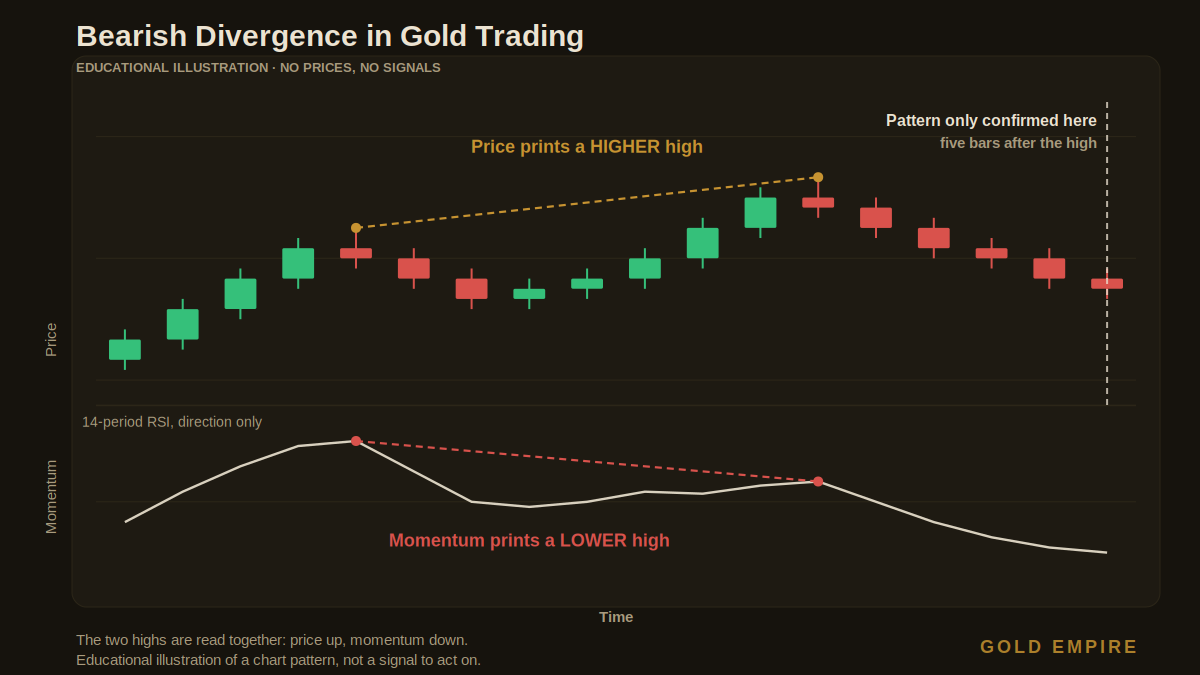
    The pattern has two halves and they have to be read together. Price makes a high, pulls back, then makes a second high that is above the first. Momentum, usually measured with a fourteen period Relative Strength Index, makes a high at the same time as that first price high, then makes a second high that is below the first. Price up, momentum down, in the same stretch of chart.

    The reasoning behind it is sound enough as reasoning. RSI measures the size of recent up moves against the size of recent down moves. If price grinds to a new high on smaller daily gains than it used before, the ratio falls even as the price rises. So the pattern is a description of something genuine: the market got to a higher number with less force behind it than last time.

    The leap people make is from that description to a forecast. Less force now is taken to mean lower prices soon. That leap is the part I wanted to test, because it is the part that costs money.

    Bearish divergence in gold trading, an educational chart showing price printing a higher high while the fourteen period RSI prints a lower high, with the bar where the pattern can first be confirmed
    Bearish divergence in gold trading: the two highs are read together, price up and momentum down, and the pattern can only be confirmed several bars after the high has already passed.

    How I measured it, and why the method matters more than the result

    The price series is the LBMA Gold Price PM, the London afternoon auction print, published by the London Bullion Market Association. It runs from the first of April 1968 to the twenty ninth of September 2026, which is 14,693 trading days. One print per day, so this is an auction record rather than an intraday bar, and a high here means a high in the run of daily fixings.

    I defined a swing high as a fixing that is the strict maximum of the eleven day window centred on it, five days either side. That produced 835 swing highs. Then a bearish divergence is a swing high whose price is above the previous swing high while its RSI is below the RSI at that previous swing high, with the two highs between five and sixty trading days apart, and with RSI at the later high at or above 55, which is the usual textbook precondition that the market be at least moderately stretched.

    That gives 75 of them in fifty eight years. One every 196 trading days, about 1.29 a year. The first thing worth saying is that this is a rare pattern if you define it strictly, and most of what gets posted in group chats as a divergence would not survive the definition.

    The trap that makes the pattern look far better than it is

    Here is the part that changed my mind while I was writing the code, and it is the reason I am writing this article at all.

    A swing high defined as the maximum of five days either side cannot be identified on the day it happens. By construction, you need the next five days to have printed lower before you can call it a high at all. So if you measure what price did starting from the high itself, the definition has already guaranteed you the first five days of the answer. That is not a finding. That is the test marking its own homework.

    When I made that mistake deliberately and measured forward from the high, the pattern looked spectacular. Price was lower ten days later in 85.3 per cent of cases. If I had stopped there, this would be a very different and much more popular article.

    Measured properly, from the confirmation day, which is the first day a human being could actually have known the pattern existed, price was lower ten days later in 52.0 per cent of cases. The gap between 85.3 and 52.0 is not a subtlety. It is the whole difference between a tradeable claim and a coin flip, and it is entirely an artefact of when you start the clock.

    The size of what gets handed over for free in that window is measurable too. Between the high and the confirmation day, the median case had already fallen 1.92 per cent. A look ahead test gives you that move as a gift. The market does not.

    What 75 bearish divergences in gold actually did

    Comparing against all days would be a soft test, because a swing high is by definition a local top and local tops tend to be followed by weakness whether or not momentum diverged. So the fair comparison is against other swing highs that were also stretched, RSI at or above 55, and confirmed the same way, but showed no divergence. There are 474 of those.

    Ten days after confirmation, price was lower in 52.0 per cent of divergence cases against 48.7 per cent of the control group. Twenty days, 54.7 against 46.8. Sixty days, 41.3 against 44.6, which is to say that at the longest horizon the divergences were followed by slightly fewer declines than the swing highs without them.

    So the strongest reading the data supports is this: there is a small effect at twenty days, about eight percentage points over a comparable group, on a sample of 75. That is not nothing. It is also nowhere near enough to carry a decision on its own, and it inverts by sixty days.

    Two more numbers finish the picture. In 46.7 per cent of cases the market printed a fixing above the divergence high within twenty days of confirmation, meaning the high the pattern was pointing at did not hold at all. And splitting by decade, the twenty day hit rate runs from 33.3 per cent in the 2020s to 80.0 per cent in the 2000s, on samples of nine to nineteen. A statistic that swings that far between decades on samples that small is not a stable property of the market. It is noise wearing a pattern’s clothing.

    Why the pattern survives anyway

    Patterns like this persist because of how they are remembered rather than how they perform. A divergence that preceded a fall is memorable, screenshot, and posted. A divergence that preceded a new high is quietly reclassified as a failed signal or as the wrong timeframe, and it does not get posted. Nobody is lying. The sample is just being assembled by memory, and memory is not a random sampler.

    The look ahead problem makes it worse, because it is invisible from the inside. If you scroll back through a chart and mark the divergences, your eye finds them at the completed highs, where they are obvious. You are doing the 85.3 per cent version of the test without knowing you are doing it. The pattern feels reliable because you are seeing it under conditions you will never have in real time.

    What I think it is honestly good for

    I am not telling you to delete the indicator. I am telling you what its output supports.

    A bearish divergence is a reasonable description of a market that is climbing with less force than it climbed before. Read as a description, it is accurate and sometimes useful context, in the same way that knowing where the crowd is positioned is context. Read as a forecast of the next twenty days, the evidence is an eight point edge over a comparable group, on 75 samples, that reverses at sixty days and swings between 33 and 80 per cent depending on which decade you happen to be trading in.

    The practical consequence is about sizing rather than direction. Nothing in these numbers justifies a bigger position, an earlier entry or a conviction that a level will hold. If an observation moves your size, it needs to be far more reliable than this one is. That is the same test I would apply to market structure or to a liquidity sweep, and most chart observations fail it.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    Does a bearish divergence mean gold is about to fall?

    On this data, no, not reliably. Measured from the first day the pattern could be seen, price was lower twenty days later in 54.7 per cent of the 75 cases, against 46.8 per cent for comparable stretched highs without a divergence. That is a small edge on a small sample, and it disappears and reverses by sixty days.

    Why is your hit rate lower than what other sites report?

    Almost certainly because of when the clock starts. If forward returns are measured from the swing high itself, the same data gives 85.3 per cent at ten days rather than 52.0 per cent. A swing high defined with a five day window cannot be known until five days later, so measuring from the high builds the answer into the question.

    Would a different RSI setting or timeframe change the result?

    It would change the numbers, certainly. It would not change the structural problem, which is that any swing based definition carries a confirmation lag, and any test that ignores that lag will flatter the pattern. If you test a variant, test it from the confirmation bar and compare it against similar highs without divergence rather than against all days.

    Is a divergence on a longer timeframe more reliable?

    This test used daily auction prints, so I cannot answer for intraday charts from this data, and I would rather say so than guess. What I would point out is that a longer timeframe means a longer confirmation lag in calendar time, so the cost of the delay gets bigger, not smaller.

    What about bullish divergence?

    Same method, mirrored, and the same caution applies. I have not published those numbers because I have not run them with the same care, and I am not going to assert a result I have not measured.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily gold analysis with the reasoning written out, the losing days included rather than quietly dropped, plus an optional Kit for people who want the method in one place. There is no promise of profit here, because nobody honest can make one.

    If this article stopped you from sizing up on a divergence, it did its job. The habit it belongs to is the unglamorous one: decide what an observation is worth before you let it change your risk. That sits with risk management in gold trading and with reading a gold chart with a clear head, and if you want to know who is writing this, the about page covers it.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He has a particular impatience with backtests that start the clock at a moment nobody could have traded, because those are the ones that turn a coin flip into a conviction. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about a chart pattern and about how to test one. It is not investment advice, not a recommendation of any indicator, technique or platform, and not a solicitation to trade. The price series used is the LBMA Gold Price PM published by the London Bullion Market Association, covering 14,693 trading days from April 1968 to September 2026. Every statistic here is my own arithmetic on that series under the definitions stated in the text, a fourteen period Wilder RSI, a five day swing window, an RSI threshold of 55 and a five to sixty day separation between highs; different definitions will give different numbers, which is rather the point. Past behaviour of a pattern is not a forecast of its future behaviour, and no gold price level appears anywhere in this article. Trading carries risk of loss.


  • Gold ETF vs Gold Fund Which Is Better: Structure, Fee and Tax Rate

    Gold ETF vs Gold Fund Which Is Better: Structure, Fee and Tax Rate

    Someone in the channel asked me a question that sounds simple and is not. He had found two products at his broker, one called a gold ETF and one called a gold fund, and he wanted to know which one to put his savings into. The question of gold etf vs gold fund which is better gets asked constantly, and almost every answer I have read online compares the wrong things: past performance, ticker popularity, which one the platform pushes on the front page.

    None of that is the useful comparison. The useful comparison is structural, and it decides three things that will follow you for as long as you hold the position: what you actually own, what it costs you every year, and what rate your gains get taxed at. Two of those three are knowable in advance with certainty. Let me go through them.

    Gold etf vs gold fund which is better starts with what you actually own

    The first trap is that neither name tells you what is inside. “Gold fund” is not a legal category, and “gold ETF” describes how a thing trades, not what it holds.

    Under those two labels you will find at least three genuinely different products. There are funds that hold physical bullion in a vault. There are funds that hold shares in gold mining companies. And there are funds that hold other funds, or that hold futures contracts rather than metal. A mining fund and a bullion fund can both be sold to you as “gold”, and they behave differently, because a mining company is a business with debt, costs, management and a share price that can fall while the metal rises.

    So the first thing to do, before any comparison of fees, is to open the document and find out which of those three you are looking at. That distinction matters more than everything else in this article combined, and it is the one people skip because it takes ten minutes and the fee number takes ten seconds.

    What “fund” means legally, and why the wrapper is not decoration

    There is a real legal distinction underneath the marketing, and it is worth knowing because it changes what protections apply.

    A conventional mutual fund is a registered product. The SEC’s own investor education material describes a mutual fund as an SEC-registered open-end investment company that pools money from many investors, whose portfolio is managed by an SEC-registered investment adviser, and whose investors buy and redeem shares from the fund itself at the next calculated net asset value on any business day.

    Read what that gives you: registration, a regulated adviser, and redemption at net asset value once a day. It also tells you what it does not give you, which is the ability to sell at eleven in the morning at a price you can see. You get the day’s NAV, whatever that turns out to be.

    A bullion-backed exchange traded product is often organised differently, commonly as a trust that holds metal, rather than as a registered investment company of that kind. It trades on an exchange all day like a share, so you can deal intraday at a visible price, and you are buying from another market participant rather than from the fund. That is a genuine convenience. It is also a different legal object with a different rulebook, and you should not assume the protections are identical because the marketing language is.

    The practical instruction here is boring and I am going to give it anyway: find the prospectus, find the section that says how the thing is organised, and read that section. It is usually one page. It is the highest return ten minutes available to a person at this stage of the decision.

    The tax difference that almost nobody checks first

    Now the part that surprises people, and the reason I think this question deserves a whole article rather than a one line answer.

    In the United States, long term capital gains for most assets are capped at a top rate of 20 per cent. But the IRS treats collectibles differently. Its guidance on capital gains states plainly that net capital gains from selling collectibles are taxed at a maximum 28 per cent rate.

    And gold is a collectible for this purpose. IRS Publication 550 defines a collectibles gain or loss as gain or loss from the sale or trade of a work of art, rug, antique, metal (such as gold, silver, and platinum bullion), gem, stamp, coin, or alcoholic beverage held more than 1 year. The same passage adds the sentence that matters most here: collectibles gain includes gain from the sale of an interest in a partnership, S corporation, or trust due to unrealized appreciation of collectibles.

    Hold those two together. If the product you own is a trust whose appreciation comes from bullion, the gain can be a collectibles gain, taxed at up to 28 per cent rather than up to 20 per cent. On 10,000 USD of gain that is the difference between keeping 8,000 USD and keeping 7,200 USD, or 800 USD, purely because of how the wrapper is built.

    I want to be careful about how far I take that. Your own situation, your country, your account type and the specific structure of your fund all change the answer, and a fund held inside a tax sheltered retirement account is a different conversation entirely. I am not a tax adviser and this is not tax advice. What I am telling you is that the wrapper has a tax consequence, that the consequence is large enough to notice, and that it is the sort of thing worth asking a qualified person about before you buy rather than in April afterwards.

    What the annual fee does while you are not looking

    The third structural difference is the annual fee, and this is the one you can calculate exactly.

    A fund charges a percentage of assets every year, whether the year was good or bad. Bullion exchange traded products tend to sit at the lower end, and actively managed funds and funds that hold other funds tend to sit higher, because the second layer of management gets paid too.

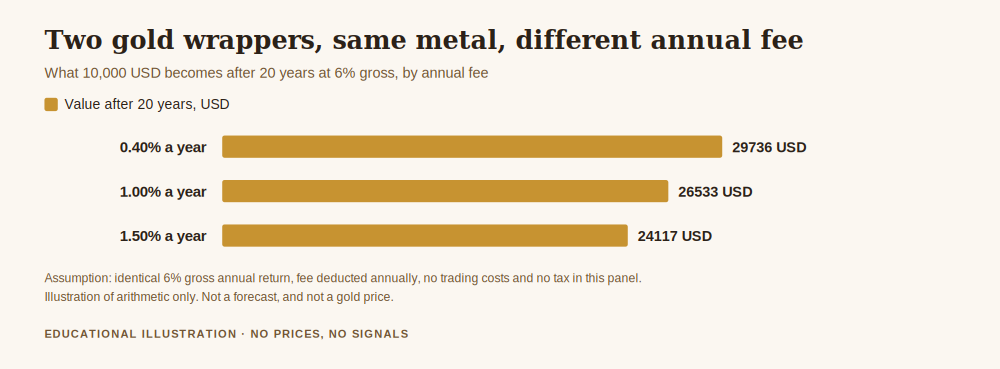
    Gold etf vs gold fund which is better, chart comparing what ten thousand US dollars becomes after twenty years at a six per cent gross return under annual fees of 0.40, 1.00 and 1.50 per cent
    Gold etf vs gold fund which is better, answered on cost alone: at 6 per cent gross over 20 years, a 1.50 per cent fee gives up 5,619 USD against a 0.40 per cent one.

    Take 10,000 USD, assume an identical 6 per cent gross annual return for both, and change nothing but the fee. After 20 years the 0.40 per cent product is worth 29,736 USD and the 1.00 per cent product is worth 26,533 USD. The gap is 3,203 USD, which is 10.8 per cent of the cheaper result. Push the fee to 1.50 per cent and the gap becomes 5,619 USD, or 18.9 per cent.

    Those are assumptions, stated openly: same gross return, fee deducted annually, no trading costs, no tax in that particular calculation, and a 6 per cent figure chosen to make the arithmetic comparable rather than as any forecast of what gold will do. Nobody knows what gold will do. The fee, by contrast, is published in advance and is one of the very few numbers in this business you can know before you commit.

    That is the reason I keep returning to costs in everything I write. You cannot control the return. You can control the fee and the tax treatment, and over twenty years those two do more visible damage than most of the things people worry about instead.

    So which one is better

    Neither, as a general answer, and I would be suspicious of anyone who gives you one without asking what you are trying to do.

    What I can offer is the order to think in. Decide what exposure you want first, metal or mining companies, because that is the largest difference and it is not a cost question. Then check the annual fee, because it is knowable and it compounds. Then check the structure and its tax consequence, because an 8 percentage point difference in rate is not a detail. Then, last, consider whether intraday dealing actually matters to you, which for someone buying to hold for years it usually does not.

    And if what you actually want is the metal itself rather than a claim on it, that is a third road with its own costs, covered in gold ETF vs physical gold returns. If you are weighing metal against the companies that dig it up, is it better to buy physical gold or gold stocks takes that comparison apart.

    One thing this article is not about, and I want to say it clearly: none of this is a view on whether you should own gold at all, or when. It is about what happens to the money once you have decided. Whatever you hold it in, size it as part of a plan rather than as a reaction, which is the argument in risk management in gold trading.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting your account, including the costs worth checking before you commit money to anything. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    Is a gold ETF always cheaper than a gold fund?
    Usually but not reliably, and “usually” is not a good enough basis to skip checking. Bullion exchange traded products tend to sit at the low end of the fee range because they are doing something mechanical, holding metal, while an actively managed fund is paying people to make decisions and a fund that holds other funds is paying two layers. But fee ranges overlap, and a cheap wrapper around the wrong exposure is not a bargain. Look up the actual published figure for the actual product rather than reasoning from the category name.

    Does the 28 per cent collectibles rate apply to every gold product?
    No, and this is exactly why the structure matters. The rate attaches to collectibles gain, which the IRS defines to include gold bullion and to include gain from selling an interest in a trust due to unrealized appreciation of collectibles. A fund holding mining company shares is holding equities, not metal, so it is not the same case. Account type changes it again. The honest answer is that it depends on the specific product and on your situation, which is the whole argument for reading the prospectus and asking a qualified person in your country.

    Where did the fee numbers in the chart come from?
    They are my own arithmetic, not quoted from any provider. I took 10,000 USD, applied a 6 per cent gross annual return, deducted the fee annually, and compounded for 20 years at three fee levels. The 6 per cent is a comparison device, not a prediction, and the point survives whatever number you substitute: the gap between fee levels is a fixed share of the result and grows with time. Put your own product’s published fee into the same calculation and you will get a figure that means something for your case.

    Can I just hold the metal instead?
    You can, and plenty of people should consider it, but understand that you are swapping one set of costs for another rather than escaping costs. Physical metal brings a dealer spread when you buy and again when you sell, storage or insurance if you do not want it in a drawer, and the practical problem of verifying and selling it later. It removes the annual management fee and it removes counterparty questions. Which set of costs suits you depends on size, timeframe and how much practical hassle you are willing to absorb.

    Does any of this tell me whether gold will go up?
    Not even slightly, and I would be wary of any page that mixes the two questions. Everything here is about the container, not the contents. Choosing a cheaper wrapper does not make gold rise, and choosing the most expensive one does not make it fall. The reason to get the container right is that it is the part of the outcome you can actually determine in advance, which is rare enough to be worth the ten minutes.

    What Gold Empire actually does

    Gold Empire is a free Telegram channel and a free library of market notes about gold, written for people who want to survive their first few years in this market rather than get rich in them. Everything on the site is free and there is no profit promise anywhere on it, because nobody can make one honestly. The model is simple: follow along for free, and take the free survival sheet if it is useful to you.

    About the author. Matthew writes the Gold Empire market notes and has spent most of his time in this market learning what not to do. He is not a licensed adviser and does not want to be one, and he paid a fee for years without once checking what it compounded to. His interest is in the part of this business nobody posts screenshots of: staying in the game long enough for a method to matter.

    Disclaimer: This article is general educational content about the structure and cost of investment products. It is not financial advice, not tax advice, not a recommendation, and not a solicitation to buy or sell anything. All cost figures are illustrations computed from stated assumptions and are not quoted from any provider. Tax treatment depends on your individual circumstances and on the jurisdiction you are in, and it can change. Trading and investing carry a risk of losing money, and no entry, stop or target discussed should be treated as a signal. Consider your own circumstances and seek independent regulated advice if you need it.


  • What Is an ECN Broker, and Does the Label Change Who Takes the Other Side

    What Is an ECN Broker, and Does the Label Change Who Takes the Other Side

    Someone in the community sent me two broker adverts last week and asked which one to open with. Both used the same three letters in the headline. He wanted to know what is an ecn broker, whether it was better than what he had, and whether switching would stop the bleeding in his account.

    I want to answer the first part properly, because the term has a real technical meaning and it is worth knowing. Then I want to show you the arithmetic on the second part, because I have watched a lot of people change broker looking for a fix and arrive at the new one with exactly the same problem.

    What is an ecn broker, in the original sense

    ECN stands for Electronic Communication Network. It came out of the equity markets, and it described something specific: a system that matched buy and sell orders from many participants directly against each other, displayed the resulting book, and charged a fee for the match rather than making money on the difference between the two prices.

    The important word in that description is match. In a true ECN, the venue is not the other side of your trade. It is a place where your order meets somebody else’s. If you buy, another participant sold. The venue took a fee and went home flat, not caring at all which way the price went afterwards.

    Set against that is the dealer model. You click buy, and the firm you clicked with sells to you. It is your counterparty. It now holds a position, and it either hedges that position somewhere else or it holds the risk itself. Its revenue is the difference between the price it showed you and the price it can get elsewhere, plus whatever your position does.

    Those are genuinely different arrangements and it is reasonable to want to know which one you are in. The problem is what happened to the label on the way to the retail advertising department.

    The label is not a regulated category, and here is the proof

    This is the part almost nobody checks, and it took me one page of a regulator’s website to find.

    The US Commodity Futures Trading Commission wrote the rulebook for off-exchange retail foreign exchange after Dodd-Frank. Its Foreign Currency Trading page sets out what that rulebook requires, and the relevant sentence is this: the regulations “require the registration of counterparties offering retail foreign currency contracts as either futures commission merchants (FCMs) or retail foreign exchange dealers (RFEDs), a new category of registrant.”

    Read the word the regulator chose. Counterparties. Not venues, not networks, not matching engines. In the eyes of the rulebook governing retail forex in the United States, the firm offering you the contract is the other side of it, and the category it must register under is literally called a dealer.

    There is no ECN category in that list. Not because ECNs are banned, but because what is being offered to a retail client is not a match on a venue, it is a contract with a firm.

    Two more numbers from the same page, and they are worth having. The final rules were published on 10 September 2010 at 75 Fed. Reg. 55410, effective 18 October 2010. And the capital requirement is specific: FCMs and RFEDs “are required to maintain net capital of $20 million plus 5 percent of the amount, if any, by which liabilities to retail forex customers exceed $10 million.”

    Twenty million dollars, before a single client deposits. That figure tells you more about the business you are dealing with than any three letter label. It exists because the regulator concluded the firm is carrying your risk and must be solvent enough to honour it.

    What the label usually means in practice

    None of this makes the word meaningless. When a retail broker advertises an ECN or raw spread account, it is normally signalling three real things, and they are worth understanding on their own terms rather than as a brand.

    • A different pricing structure. Tighter quoted spread, plus an explicit commission per round turn, instead of a wider spread and no visible commission. This is a cost question, and it is the whole subject of a separate article, what is an ECN account, which takes the same three letters from the account side, works through the US equity market definition at 17 CFR 242.600, and does the spread against commission sum. This article is about the firm and who is on the other side. That one is about the account and what it costs you.
    • Aggregated pricing. The quote is built from several liquidity providers rather than one internal desk. That usually does mean a tighter and more competitive price.
    • An intention to hedge rather than warehouse. The firm is telling you it expects to pass your risk on rather than sit against it.

    Every one of those is a genuine thing a broker might do. What none of them is, is a regulated guarantee. A firm can hedge one client’s flow and hold another’s, and switch which is which based on how the client is doing. That practice has a name in the industry and it is entirely legal and disclosed in the terms you agreed to. The label on the account does not decide it.

    Now the arithmetic, which is why I am not excited about the label

    Here is the calculation that changed how I think about this, and you can check every step.

    Take an account with no edge at all. Not a bad trader, not an emotional one. A perfectly disciplined account whose trades are a fair coin flip: 200 trades in a year, each one either winning exactly one unit of risk or losing exactly one unit of risk, with equal probability. Then subtract a fixed cost per round turn, expressed in those same units.

    This is exact binomial arithmetic, not a simulation, so there is no seed and no sampling error. The question is: what share of those accounts finish the year in profit?

    What is an ecn broker, chart showing the share of accounts with no edge that finish two hundred trades in profit at four different cost levels per round turn
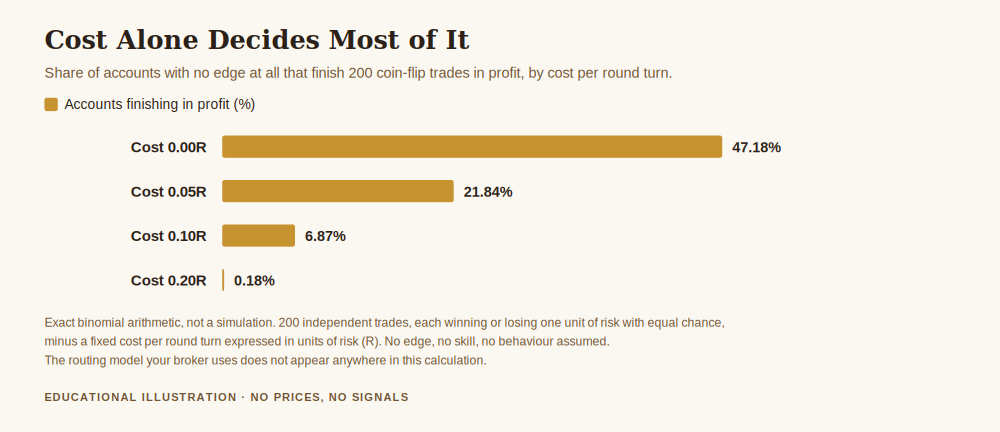
    What is an ecn broker worth to you, answered sideways: the share of no-edge accounts finishing 200 trades in profit, by cost per round turn. The routing model does not appear in this calculation.
    • At zero cost, 47.18 per cent finish in profit. Not fifty, because with an even number of trades a good many land exactly at break even.
    • At 0.05R per round turn, it falls to 21.84 per cent.
    • At 0.10R, it falls to 6.87 per cent.
    • At 0.20R, it falls to 0.18 per cent. Roughly one account in five hundred and fifty.

    Read those four numbers again, because they are the whole article. Nothing changed between them except the cost per trade. No psychology, no revenge trading, no bad entries, no leverage, no news event. Cost alone took a group of accounts from a near coin flip to a near certainty of loss.

    And now hold that against what the European Securities and Markets Authority found when it looked at real accounts. In the announcement of its measures on binary options and CFDs, ESMA reported that national regulators’ analyses “shows that 74-89% of retail accounts typically lose money on their investments, with average losses per client ranging from €1,600 to €29,000.”

    Between 74 and 89 per cent losing. My no-edge accounts at 0.05R cost lose 78.2 per cent of the time. At 0.10R they lose 93.1 per cent of the time. The regulator’s observed range sits almost exactly where friction alone would put it.

    I want to be careful about what I am claiming. I am not saying costs are the only reason retail accounts lose, and I cannot prove that from this. Real traders are not coin flips, some have an edge and some have habits far worse than random. What I am saying is narrower and I think more useful: you do not need to assume anybody behaved badly to reproduce the regulator’s numbers. Ordinary friction, applied to an account with no advantage, gets you there on its own.

    What this means for the question you actually asked

    So, should you move to an ECN account? Here is how I would order it, and notice that the label comes last.

    First, the break-even win rate. On a 1:1 payoff, cost 0.05R per round turn means you must win 52.5 per cent of the time to break even. At 0.10R it is 55.0 per cent. At 0.20R it is 60.0 per cent. Those are the hurdles your method has to clear before it produces anything at all. Work out yours before you compare any two accounts, because it tells you how much a cost saving is worth to you specifically.

    Second, trade count. Every figure above scales with the number of round turns. Two hundred trades a year at 0.10R is a 20R drag. Cut to fifty trades and the same cost per trade is a 5R drag. For most people the largest available reduction in friction is not the account type, it is the number of times they click.

    Third, solvency and regulation. The twenty million dollar figure above is the kind of thing worth checking. Is the firm registered, where, and what does that regime actually require of it. That question matters far more than routing when something goes wrong.

    Fourth, and only fourth, the cost structure. Raw spread plus commission against an all-in wider spread. This is arithmetic you can do in ten minutes for your own trade count, and it is a real saving when it goes your way, and it is usually smaller than people expect.

    The gentleman who wrote to me was trading roughly eight times a week. Moving accounts might have shaved a fraction of a unit of risk off each round turn. Halving his trade count would have done several times more, cost him nothing, and required no paperwork at all.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account from the kind of slow friction this article describes, before it becomes the reason you quit. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    So what is an ecn broker, in one sentence?
    Strictly, a venue that matches your order against another participant’s and charges a fee for the match rather than earning the spread. In retail forex advertising it usually means an account with a tight raw spread, a separate commission and aggregated pricing from several liquidity providers. Those are two different statements and the marketing rarely separates them.

    Is an ECN account safer than a dealing desk account?
    Safety comes from regulation, segregation of client money and the firm’s capital, not from routing. The CFTC page above requires registered counterparties to hold net capital of $20 million plus 5 per cent of retail liabilities above $10 million, and that requirement applies to the firm regardless of what its account types are called. Check the registration and the regime. The label tells you about pricing, not about what happens if the firm fails.

    Does an ECN account mean my broker cannot trade against me?
    No, and I would treat any firm that claims otherwise with caution. Under the US rules the firm offering the contract is registered as a counterparty, which is what the word dealer means. Whether it hedges your particular flow in the market or holds it internally is an operational decision described in your terms, and it can differ between clients and change over time. The account label does not control it.

    Will switching to a lower cost account fix a losing account?
    It helps, and the numbers above show exactly how much it can help, but look at the direction of the effect. Going from 0.10R to 0.05R per round turn moves a no-edge account from a 6.87 per cent chance of a profitable year to 21.84 per cent. That is a real improvement and still a losing proposition, because cost reduction does not manufacture an edge. It makes an existing edge survive. If there is no edge to protect, a cheaper account only slows down the same outcome.

    Where do the percentages in the chart come from?
    They are my own exact binomial arithmetic, computed in Python and reproducible with a pocket calculator and patience. 200 independent trades, each winning or losing one unit of risk with probability one half, minus a fixed cost per round turn in the same units. An account finishes in profit when wins minus losses exceed total costs. No behaviour, skill, leverage or market condition is modelled, which is the entire point: these are the numbers before anything human happens.

    What are the limits of that calculation?
    Several, and I would rather state them than have you find them. Real trades are not 1:1 payoffs and not independent. Real costs vary with volatility, time of day and how the order fills. Real traders are not coin flips. And a 200 trade year is one choice of many. The calculation is not a model of you, it is a floor: it shows what cost does before anything else is added, and everything else is added on top of it.

    Does Gold Empire recommend a particular broker?
    There are broker articles on this site and some carry partner links, which are always disclosed on the page itself. Nothing here, including this article, is a recommendation to open any particular account, and the arithmetic above is deliberately the sort that no broker’s marketing department would commission.

    What Gold Empire actually does

    Gold Empire is a free resource for people trying to survive their first years in gold rather than get rich in them. The articles are free, the daily analysis on Telegram is free, and the Gold Survival Sheet is free. There is no profit promise anywhere on this site and there never will be, because the arithmetic in this article is precisely why nobody can make one honestly.

    If cost is the thread you want to pull, raw spread account vs standard account does the full comparison with your own trade count, and what is the spread in gold trading covers the first cost every trade pays. The article underneath all of them is risk management in gold trading, and if you are choosing a firm rather than an account type, best broker for gold trading is the one to read.

    About the author. Matthew writes Gold Empire. He changed broker three times early on looking for the thing that was wrong, and the thing that was wrong turned out to be how often he was clicking. Nothing in this article is financial advice or a recommendation to open any account, and no entry, stop or target discussed should be treated as a signal.


  • What Is Hedging in Gold Trading, and What the Lock Actually Costs

    What Is Hedging in Gold Trading, and What the Lock Actually Costs

    Sooner or later somebody in the group asks what is hedging in gold trading, and almost always they ask it while holding a position that is down. That timing is the whole story. The question arrives dressed as a technical one, but underneath it is a request for a way to not take the loss yet. I want to answer the technical part properly, and then I want to be straight with you about the other part, because the arithmetic is unkind and almost nobody runs it before they press the button.

    Everything below is either quoted from a rulebook you can open yourself, or arithmetic I have shown in full with the assumptions written out. There are no gold prices in this article and nothing here is a recommendation.

    What is hedging in gold trading, and what people usually mean by it

    In the textbook sense, hedging means holding one position to offset the risk of another, where the two things are genuinely different. A refiner with metal in a vault sells futures against it. A mining company with production coming in nine months locks in a price today. In both cases there is a real exposure sitting outside the trading account, and the market position exists to cancel it.

    That is not what the question usually means. What retail traders almost always mean is opening a sell of the same size, in the same instrument, in the same account, while the buy is still open. Long one lot, short one lot, both live. The floating loss stops moving. People call this a hedge. The more honest name, and the one used in most trading rooms, is a lock.

    The distinction matters because the two things do different work. A refiner’s hedge cancels a risk that exists elsewhere. A lock cancels nothing. It freezes a number on a screen, and the position it freezes is one you already own the consequences of. You have not removed the loss. You have paid to stop looking at it.

    The rule that says the position cannot exist

    Here is the part that surprises people, and it is the cleanest evidence that this is not a normal trading technique.

    If your account is with a US registered forex dealer, the lock is not allowed. It is not discouraged, not penalised, not a matter of platform settings. It is prohibited by rule. NFA Compliance Rule 2-43, section (b), reads in full:

    Forex Dealer Members may not carry offsetting positions in a customer account but must offset them on a first-in, first-out basis. At the customer’s request, an FDM may offset same-size transactions even if there are older transactions of a different size but must offset the transaction against the oldest transaction of that size.

    Read that slowly. Offsetting positions may not be carried. If you are long a lot and you sell a lot, the sell does not sit alongside the buy, it closes the buy, oldest first. The rule was adopted effective 15 May 2009 and has been amended four times since, most recently on 15 September 2022, so it is neither new nor an accident of drafting.

    A regulator does not write a first in, first out requirement into a rulebook because the alternative is merely inelegant. It writes it because carrying both sides at once obscures what the customer actually owns, doubles the transaction costs the customer pays, and makes the account statement harder to read than the position it describes. The rule exists to stop the thing this article is about.

    Plenty of brokers outside that jurisdiction do allow it, and their platforms have a button for it. The button existing is not evidence that the manoeuvre is sound. It is evidence about where the firm is registered, which is a different fact, and one worth checking for its own reasons before you check anything else.

    What the lock actually costs, with the assumptions written out

    Let me do the arithmetic, because this is the part that gets skipped.

    I am going to assume one standard lot of gold is 100 troy ounces, which is the usual contract convention. I am going to assume a spread of 0.30 US dollars an ounce and a combined overnight financing cost across both legs of 0.02 dollars an ounce per session. Both of those are assumptions I have chosen to make the arithmetic concrete, not quotes from any broker, and I will show you further down what happens when you change them. I am also assuming each position pays the spread once across its lifetime, which is the standard way to count a round turn.

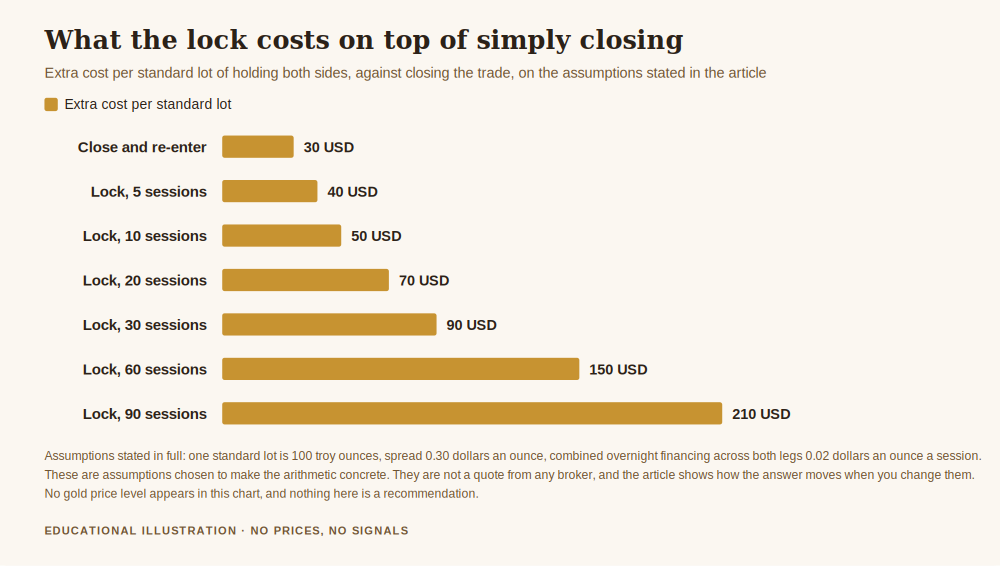
    One position, opened and later closed, costs 0.30 times 100, which is 30.00 dollars a lot.

    A lock is two positions. That is 60.00 dollars a lot before anything else happens. You have doubled your transaction cost, permanently, in exchange for freezing a number.

    Then the financing starts. Both legs are open, so both accrue overnight, every session, for as long as the lock exists. At the assumed 0.02 dollars an ounce a session, that is 2.00 dollars a lot a day, and it does not stop because you have stopped thinking about the trade.

    What is hedging in gold trading, chart comparing the extra cost of a locked gold position against simply closing the trade, across holding periods from five to ninety sessions
    What is hedging in gold trading costs, once you total it. Extra cost per standard lot of a locked position against closing and re-entering, on the assumptions stated in this article.

    Adding the second spread to the accumulated financing gives the total extra cost of the lock, over and above simply having one position. Hold it five sessions and it is 40.00 dollars a lot. Ten sessions, 50.00. Twenty sessions, 70.00. Thirty sessions, 90.00. Sixty sessions, 150.00. Ninety sessions, 210.00 dollars a lot, which is seven times the cost of the single round turn you were trying to avoid paying.

    Expressed per ounce, so it is comparable to a price move, the thirty session lock costs 0.900 dollars an ounce and the sixty session lock costs 1.500 dollars an ounce. That is the distance the market has to travel in your favour after you unwind, purely to get you back to where you would have been if you had closed the position on day one and done nothing else.

    Now change the assumptions, because yours will be different. At a narrower 0.20 dollar spread and cheap 0.01 dollar financing, a thirty session lock costs 50.00 dollars a lot. At a wider 0.50 dollar spread and 0.04 dollar financing, the same thirty sessions cost 170.00 dollars a lot. Across that range the answer moves by a factor of more than three, and every single version of it is a cost you would not have paid by closing the trade. There is no combination of inputs where the lock is cheaper. That is not a coincidence, it is structural: you are paying to hold two positions where one would do, and the arithmetic cannot come out any other way.

    The decision you did not avoid

    Cost is the easy objection. The harder one is that the lock does not do the job people believe it does.

    When you lock, the loss is frozen but it is not resolved. At some point you have to take one leg off, and the moment you do, you are directional again, with exactly the same question you had before: which way is this going. You have not answered it. You have deferred it, at a price, and you have deferred it to a version of yourself who has now been sitting with the position for weeks and is more invested in being right about it, not less.

    Worse, the decision has become harder rather than easier. Before the lock there was one position and one question. After it there are two positions, two entry levels, two financing lines and a choice about which leg to remove first, and the two legs no longer move in step once you start removing one. People who lock frequently describe the same experience, which is that unwinding it well turns out to require better timing than the original trade did.

    Against that, consider what closing actually costs. You crystallise the loss, which is the part that hurts, and you pay one more spread when you want to be in the market again. That is 30.00 dollars a lot on the assumptions above. The thirty session lock costs 90.00, which is three times as much, and at the end of it you still have to decide. The loss was going to be the loss either way. The only variable you controlled was how much you paid on top of it, and the lock is the expensive branch.

    This is the same logic that runs through everything in risk management in gold trading. The costs that ruin accounts are rarely dramatic. They are small, repeated, and incurred while avoiding a decision. It is worth understanding what swap in gold trading is charging you before you double it, and worth knowing what the spread in gold trading takes on a single position before you commit to paying it twice.

    What the position size question looks like underneath

    There is one more thing worth saying, because it is the actual problem in most cases where this comes up.

    Nobody wants to lock a position that is comfortably sized. The urge appears when the position is large enough that closing it would hurt in a way the trader is not prepared to accept. The lock is not a market judgement at that point. It is a response to sizing, arriving several days too late to help.

    For scale, take the afternoon gold auction published by the London Bullion Market Association, in US dollars. Across the 14,690 day to day changes in that record, the middle of the distribution is a move of 0.511 per cent. That is what an ordinary day does. If an ordinary day in a normal market is producing a floating loss you feel you have to freeze rather than accept, the position was too big when it was opened, and no amount of clever position management afterwards fixes a sizing decision made in the past.

    The rules in Europe point at the same conclusion from the other direction. The measures agreed by ESMA for retail contracts for difference set leverage at 20:1 for gold, require providers to close out retail positions at 50 per cent of minimum required margin, and provide negative balance protection on a per account basis. Notice what a margin close out rule implies. The regulator has assumed that at some point a retail position will need to be closed rather than managed, and has written the threshold into the rulebook rather than leaving it to the trader in the moment. There is a reason for that, and it is not a flattering one, but it is realistic, and a locked position sitting on both sides of the book does not exempt anyone from it.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    Is hedging the same thing as a stop loss?
    No, and they are close to opposites in what they commit you to. A stop is a decision made in advance about the point at which you are wrong, and it removes the position when that point arrives. A lock is a decision made in the middle of the trade to not decide, and it keeps both positions. One resolves the exposure, the other preserves it and charges you for the privilege.

    My broker allows it, so why would it be a problem?
    Whether a platform permits something and whether it serves you are separate questions. US registered forex dealers cannot carry offsetting positions at all under NFA Compliance Rule 2-43(b), quoted above, and the same manoeuvre is freely available elsewhere. That tells you about the regulatory perimeter your account sits inside, not about the merits of the trade. Both facts are worth knowing, and neither is a reason to use the button.

    Are there situations where holding both sides genuinely makes sense?
    Yes, when there is a real exposure outside the trading account that the market position offsets, which is the textbook case: a producer, a refiner, a jeweller with inventory, a business with a contracted delivery. In each of those the hedge cancels a risk that exists in the physical world. If both your positions are in the same account and there is no outside exposure, there is nothing being cancelled, and the description does not fit however it is labelled on the platform.

    What if I lock and then the market moves a long way?
    Then the two legs offset and your account equity barely changes, which sounds like the point until you notice that this is true in both directions. You have given up the recovery you were hoping for along with the loss you were avoiding. The frozen position captures nothing, and it accrues financing on both legs the entire time it is frozen.

    Where do the numbers in this article come from?
    The quoted rule text is from NFA Compliance Rule 2-43 on the National Futures Association’s own rulebook page, linked above. The leverage, margin close out and negative balance protection measures are from the ESMA announcement, also linked. The median daily move of 0.511 per cent is my own calculation across 14,690 day to day changes in the LBMA afternoon gold auction in US dollars, linked above. Every cost figure is my own arithmetic on two assumptions stated in the text, a spread of 0.30 dollars an ounce and combined financing of 0.02 dollars an ounce per session, with a sensitivity range shown. None of them is a quote from a broker, and no gold price level appears anywhere in this article.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily gold analysis with the reasoning written out, the losing days included rather than quietly dropped, plus an optional Kit for people who want the method in one place. There is no promise of profit here, because nobody honest can make one.

    If this article talked you out of one lock, it has more than paid for itself. The habit it belongs to is the boring one: decide the size before you enter, so that the moment where freezing the screen feels necessary never arrives. That sits with risk management in gold trading and with managing a gold trade after you enter, and if you want to know who is writing this, the about page covers it.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He has a particular impatience with manoeuvres that feel like action while changing nothing, because those are the ones that quietly empty an account over a year. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about position management, trading costs and the rules that apply to retail forex accounts in different jurisdictions. It is not investment advice, not a recommendation of any broker, platform, jurisdiction or technique, and not a solicitation to trade. The rule text is quoted from NFA Compliance Rule 2-43 published by the National Futures Association, and the retail CFD measures referenced are those agreed by ESMA; rules differ by jurisdiction and by entity and they change over time, so check the rules that actually apply to your own account rather than relying on a general description. All cost figures are arithmetic on assumptions stated in the text and are not quotes from any firm. Trading carries risk of loss.


  • What Happens If Your Forex Broker Goes Bust, and Where Your Money Actually Sits

    What Happens If Your Forex Broker Goes Bust, and Where Your Money Actually Sits

    Most people choose a broker on spread, platform and withdrawal speed, and never once ask what happens if your forex broker goes bust. It is an uncomfortable question because it has nothing to do with trading well. You can have a sound method, disciplined sizing and a year of patient work, and still lose the account to an event that happens in a legal filing rather than on a chart. The good news is that this is one of the few risks in this business you can inspect before you take it, using documents the regulators publish for free.

    This article is about where your money actually sits, who stands behind it, and what the published compensation limits genuinely cover. I have used the regulators’ own numbers throughout, and I have shown my arithmetic so you can redo it.

    What happens if your forex broker goes bust is a custody question, not a platform question

    Three different failures get filed under the same worry, and they have almost nothing in common.

    The first is an outage. The platform stops responding, you cannot close a position, and you sit there watching. That is painful and it is operational, but the firm still exists and your balance is still recorded. The second is the firm being unregulated in the first place, where there is no filing to read because nobody required one. The third, the one this article is about, is the firm ceasing to exist as a going concern while it is holding your money.

    Only the third raises the question that matters: is the money you can see in your account balance actually yours in a legal sense, held apart from the firm’s own funds, or is it a number on a screen that represents a claim on a company that no longer has assets? Those are very different positions to be in, and the answer is not decided at the moment of failure. It was decided when you opened the account and chose which jurisdiction you were dealing with, which is worth thinking about before how to open a gold trading account becomes a form you click through.

    Six firms out of seventy four, which is what the CFTC file actually shows

    In the United States, firms that hold retail forex money must file monthly financial reports with the CFTC, and the regulator publishes a summary spreadsheet every month. Anyone can download it. I pulled the file for the month ended 31 July 2026 and counted.

    Seventy four firms are listed. Of those, exactly six report any retail forex obligation at all. Their combined retail forex obligation is 471,577,840 US dollars. Across every firm in that same file, customer assets held in segregation total 382,273,801,362 US dollars, so the entire regulated retail forex pool is 0.123 per cent of the customer money sitting in that system.

    Sit with that proportion for a moment. The retail forex corner of the regulated American market is a rounding error next to the futures business it shares a rulebook with. It is not that retail forex is small worldwide, it plainly is not. It is that most of the firms advertising to retail traders are not in this file, because they are not registered here. When someone tells you a broker is large, the honest follow up is: large where, and filed with whom.

    A firm’s own capital is not a fund that pays you back

    The same file reports each firm’s adjusted net capital, which is the regulatory measure of the firm’s own financial cushion. It is tempting to read that as protection money set aside for clients. It is not. It is the firm’s own resources, and comparing it with what the firm owes retail forex customers produces a spread wide enough to be worth seeing.

    What happens if your forex broker goes bust, chart showing the share of an account balance covered by an 85,000 pound compensation cap at six account sizes
    What happens if your forex broker goes bust depends partly on a cap that does not move with your balance. Share of the balance covered by the FSCS limit, calculated across six account sizes.

    Set each firm’s adjusted net capital against its retail forex obligation for that month and the ratios run like this. GAIN Capital Group reports an obligation of 204,121,663 dollars against adjusted net capital of 82,904,419, which is 41 per cent. OANDA Corporation reports 132,445,959 against 33,191,483, which is 25 per cent. tastyfx reports 49,950,447 against 67,394,162, which is 135 per cent. Charles Schwab Futures and Forex reports 55,996,755 against 301,491,825, which is 538 per cent. Trading.com Markets reports 2,872,026 against 24,180,804, which is 842 per cent. Interactive Brokers reports 26,190,990 against adjusted net capital of 10,238,479,537, which is roughly 39,092 per cent.

    From the lowest to the highest, that is a factor of about 1,560.

    Now the important part, because this is exactly where a number like that gets misused. A low ratio is not evidence that a firm is unsafe, and I am not suggesting it is. The ratio mostly reflects what else the business does. A firm whose main activity is retail forex will naturally show a smaller multiple than a diversified broker for whom retail forex is a side line, and both can be perfectly compliant with the capital rules that apply to them. What the spread tells you is something more basic: adjusted net capital is not a client protection pot, and a firm being well capitalised in the regulatory sense is a statement about the firm, not a guarantee attached to your balance. If you want to judge a firm, judge the custody arrangement and the authorisation, which is a different exercise from the one in best broker for gold trading and sits alongside knowing what an ECN account actually changes about execution.

    What a compensation scheme promises, and exactly where it stops

    Compensation schemes are the part people half remember and badly overestimate. In the United Kingdom the Financial Services Compensation Scheme covers eligible investment claims up to 85,000 pounds per eligible person, per firm, for firms that failed after 1 April 2019. The FSCS states the condition plainly: the PRA or the FCA must have authorised the provider or adviser, as well as regulated the service and product it provided. It may protect you where a provider goes out of business and there is a shortfall in the money or assets it was holding for you, and it does not pay for investments that simply lost value.

    Two words in there carry most of the weight. Per firm means the cap is not per account and not per currency. Eligible means the authorisation has to be real and has to cover what you were actually doing.

    Separately, across the European Union, the measures agreed by ESMA for retail contracts for difference include negative balance protection on a per account basis, alongside leverage caps and a margin close out rule. Negative balance protection answers a different question from a compensation scheme. It limits what you can lose to the funds in the account while the firm is running. It says nothing about recovering those funds if the firm stops running.

    The arithmetic of a fixed cap is worth doing once, properly, because a cap does not scale with you. Assume a single eligible claim against one failed firm, and assume the whole balance is a genuine shortfall. At a balance of 10,000 pounds you are fully covered. At 50,000 pounds you are fully covered. At 85,000 pounds you are fully covered, right up to the line. At 150,000 pounds the cap covers 56.7 per cent and 65,000 pounds sits outside it. At 250,000 pounds it covers 34.0 per cent, leaving 165,000 pounds uncovered. At 500,000 pounds it covers 17.0 per cent, and 415,000 pounds is uncovered.

    Which means the protection quietly stops being protection somewhere around the point where the account starts to matter to your life. Splitting changes the arithmetic, because the cap is per firm. The same 250,000 pounds held at one firm is 34.0 per cent covered, at two firms 68.0 per cent, and at three separately authorised firms it is fully covered. The catch is that splitting only works if the firms are genuinely separate authorised entities. Two brands owned by the same legal entity count once, and finding that out afterwards is an expensive way to learn it.

    What this does and does not change

    It does not mean any firm named here is in difficulty. Every one of them filed the report the rules require, and the figures are theirs. It does not rank brokers, and it is not a recommendation to use or avoid any of them.

    The figures are also a snapshot. They describe one month, self reported by the firms, and they will be different next month. A monthly filing is evidence that a supervisory system exists and is producing public data, which is genuinely useful, rather than a live guarantee of solvency.

    What it does change is the shape of the question. Custody and authorisation are decided when you open the account, they cost nothing to check, and they are invisible in every spread comparison you will ever read. That puts them in the same family as position sizing: unglamorous decisions made in advance that quietly determine whether an account survives an event nobody scheduled. It is the same logic as everything under risk management in gold trading, applied one level further out, to the firm rather than the trade.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to protecting your account through the kind of market this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    How do I check whether my broker is actually regulated where it claims to be?
    Go to the regulator’s own register rather than the broker’s website, and match the exact legal entity name, not the brand. A group can hold a licence through one subsidiary while your account is opened with a different one in another jurisdiction. The entity named on your client agreement is the one that matters, and it is the one you should be searching for.

    Does negative balance protection mean my money is safe?
    No, and this is the most common mix up. Negative balance protection limits your loss to the funds in the account while the firm is operating normally, which is a real protection against a gap moving against you. It is not a custody arrangement and it is not compensation. It does not help you recover funds from a firm that has failed.

    Is a bigger broker automatically safer?
    Size tells you about the business, not about your claim. As the figures above show, the relationship between a firm’s own capital and what it owes retail forex customers varies by a factor of over a thousand, and a firm can be large in one activity while its retail forex book is small. Authorisation, custody and the applicable compensation scheme are what determine your position, and none of those is a function of size.

    Should I split my account across several brokers?
    That is a decision about your own circumstances and I am not going to make it for you. What I can tell you is the arithmetic: a per firm cap means the covered share of a fixed total rises as you split it across separately authorised firms, from 34.0 per cent at one firm to full coverage at three, on a 250,000 pound balance. Against that, more firms means more account admin, more platforms and more places to get something wrong.

    Where did the numbers in this article come from?
    The firm level figures are from the CFTC’s published Financial Data for FCMs, the FCM webpage update for the month ended 31 July 2026, linked above. Counting the firms, totalling the retail forex obligation, dividing it by total customer assets in segregation, and calculating each capital to obligation ratio are all my own arithmetic on that file. The 85,000 pound limit and its conditions are quoted from the FSCS page linked above. The coverage percentages are simple division under one stated assumption: a single eligible claim against one failed firm where the entire balance is a genuine shortfall. No gold price appears anywhere in this article.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily gold analysis with the reasoning written out, losing days included, plus an optional Kit for people who want the method in one place. There is no promise of profit here, because nobody honest can make one.

    Checking who holds your money is the least exciting thing you will do this year and one of the few that cannot be undone later. It belongs next to risk management in gold trading, and if you want to know who is writing this, the about page covers it.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He would rather spend an article on a filing cabinet than on a setup, because the filing cabinet is what decides whether the account is still there to trade. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about broker custody, regulatory capital reporting and compensation schemes. It is not investment advice, not a recommendation of any broker or jurisdiction, not an assessment of the financial condition of any named firm, and not a solicitation to trade. Firm level figures are taken from the monthly Financial Data for FCMs published by the CFTC for the month ended 31 July 2026 and are self reported by the firms concerned; they describe one month and will change. Compensation limits and conditions are quoted from the FSCS, and the retail CFD measures referenced are those agreed by ESMA. Eligibility, limits and protections differ by jurisdiction, by entity and by product, and they change over time, so check the current rules of the scheme that actually applies to your account and read your own client agreement rather than relying on a general description. Trading carries risk of loss.


  • What Happens If a Market Order Is Not Filled, and Why Your Stop Is One

    What Happens If a Market Order Is Not Filled, and Why Your Stop Is One

    There is a particular kind of message that arrives in the Gold Empire group after a fast hour, and it always has the same shape. The stop was set. The stop was hit. The account lost more than the stop said it would. Somewhere underneath that message is a question the person has never had to ask before, because nobody warned them it was a question at all: what happens if a market order is not filled at the price you were looking at when you sent it.

    The honest answer is that a market order is almost never rejected outright, and that is exactly why the problem catches people. It fills. It just fills somewhere else. That distance is not a glitch, not your broker being dishonest, and not something you can appeal. It is written into the definition of the order type, and most people trading gold have simply never read it. This article is about where the distance comes from, how large it gets, when it gets large, and what it does to an account that was sized on the assumption it would not exist.

    What happens if a market order is not filled at your price, in the regulator’s own words

    Start with the definition, because the definition contains the whole answer and it is a single sentence. The United States Commodity Futures Trading Commission maintains a public glossary of market terms. Its entry for a market order reads:

    An order to buy or sell a futures contract at whatever price is obtainable at the time it is entered in the order book, ring, pit, or other trading platform.

    Read the phrase “at whatever price is obtainable” again, slowly. There is no reference to the price on your screen. There is no reference to the price you clicked. A market order is an instruction about urgency, not about price. You are telling the market that you want the trade done now and that you are accepting, in advance, whatever the market charges for doing it now.

    Which means the question “what happens if a market order is not filled” is slightly the wrong question, and finding the right one is the useful part. The order will get filled. The thing that can fail is the assumption you attached to it. You assumed the price would be the one you saw. Nothing in the instruction you sent contained that assumption.

    People accept this reasonably calmly when it applies to an entry. They do not accept it calmly when they discover where else it applies.

    Your stop loss is a market order wearing a different name

    Here is the same glossary, a few entries further down, defining a stop order:

    This is an order that becomes a market order when a particular price level is reached. A sell stop is placed below the market, a buy stop is placed above the market. Sometimes referred to as stop loss order.

    That is the sentence that changes how you should think about your risk. The protective order most traders rely on, the one that lets them say “my risk on this trade is fixed”, is not a promise of a price. It is a trigger that converts into a market order, and a market order takes whatever is obtainable. Your stop defines the moment you leave. It does not define the price at which you leave.

    Chart showing what happens if a market order is not filled at your level: a stop converts to a market order and fills below the level set
    What happens if a market order is not filled at the level you set: the order still executes, at whatever price is obtainable when it arrives.

    This is not a flaw somebody should fix. It is the only way a stop could work. An order that guaranteed your price would have to refuse to trade whenever your price was unavailable, which is precisely when you most need out. That version exists, it is called a stop limit, and its failure mode is worse: it can decline to fill at all and leave you holding a position you had decided to close. You get to choose which of the two ways your safety equipment is allowed to disappoint you. You do not get to choose neither.

    The exchanges treat cascading stops as a known hazard rather than an edge case. The same CFTC glossary documents a feature on CME’s electronic platform called Stop Logic Functionality, which deliberately pauses matching when triggered stop orders would otherwise push the market too far too fast. The mechanism exists because stops firing into thin liquidity is a normal, expected event that markets are engineered around.

    Why the fill moves furthest exactly when you need it most

    The distance between your level and your fill is not random across time. It concentrates. To show how much, I took the daily gold benchmark published by the London Bullion Market Association, every afternoon auction in US dollars from 1 January 1975 to 24 September 2026, which is 12,979 day to day changes. I measured each day’s absolute move, added them all together, and asked how that total was distributed.

    Bar chart for what happens if a market order is not filled: gold's busiest 1 percent of days carry 7.4 percent of all daily movement
    Movement concentration in gold, the background condition behind the question of what happens if a market order is not filled at your level.

    The busiest one percent of days, 129 sessions out of 12,979, carry 7.4 percent of all the movement gold has made in fifty one years. The busiest five percent carry 22.7 percent. The busiest ten percent carry 35.7 percent. The busiest quarter of all days carry 61.1 percent, which leaves the remaining three quarters of the calendar sharing 38.9 percent between them.

    The median day moves 0.533 percent. Days that move two percent or more happen 7.85 percent of the time, and when they happen their average size is 3.10 percent, which is 5.8 times the median day.

    Now put the two facts side by side. A stop is a market order, so its fill quality depends on how fast price is travelling when it triggers. And gold’s travelling is concentrated into a small number of days. Your stop does not trigger on a random day. It triggers disproportionately on the days that are moving, because those are the days that reach it. The distribution of days on which your protection is tested is not the distribution of ordinary days. It is skewed towards exactly the sessions where “whatever price is obtainable” is furthest from what you were looking at.

    This is why comparing your average fill to your expected fill across a calm month tells you almost nothing about the month that matters.

    What the distance costs, counted in planned risks

    Say your stop sits one planned risk away from your entry. Call that distance 1R, which is simply the amount you decided in advance you were willing to lose on the trade. If the fill arrives past your level, the realised loss is no longer 1R. Here is the arithmetic, and the only assumption in it is that your winners pay two planned risks:

    • Fill 10 percent of the stop distance beyond your level, and the loss is 1.10R. The winners needed to recover it rise by 10 percent.
    • Fill 25 percent beyond, and the loss is 1.25R. Recovery cost rises 25 percent.
    • Fill 50 percent beyond, and the loss is 1.50R. Recovery cost rises 50 percent.
    • Fill a full stop distance beyond, and the loss is 2.00R. You now need a whole winner to undo one loser, where you had planned on half of one.

    The number that should get your attention is not any single row. It is that this tax is charged on losing trades only. Slippage on an entry can help you as often as it hurts. Slippage on a stop is asymmetric by construction, because the stop only triggers when the trade is going against you, and going against you fast is precisely the condition that widens the fill. A cost that only ever lands on your worst days compounds differently from a cost spread evenly across all of them.

    Notice what this does to position sizing. If you size so that a 1R loss is a survivable fraction of the account, and the real distribution of your losses has a tail at 1.5R and 2R, you have sized for a distribution you do not have. The gap is invisible in a quiet month and expensive in the month that is not.

    The four ways a market order actually goes wrong

    Rejection is real but rare, and the four failure modes deserve separating, because the response to each is different.

    It fills away from your price. The common one, described above. Not an error, not appealable, and the only one that reliably costs money on stops.

    It is rejected for insufficient margin. The account lacks free margin at the moment the order arrives, usually because something else moved against you in the meantime. This one is silent in a way the others are not, because you may believe you are in a trade that you are not in.

    It is rejected because the instrument is not trading. Weekend, a scheduled break, or a venue level halt. Your order waits or dies depending on the platform, and the price on the other side of the pause is whatever the pause produces.

    It is requoted. Some venues answer a market order during fast conditions with a new price and a request to confirm. In the seconds you spend deciding, the market keeps moving.

    The first is a cost. The other three are a different problem, which is believing you are protected when you are not. That is why “did my order actually execute” belongs on the same short checklist as “where is my stop”, especially after any minute where price moved quickly.

    The regulatory backstops define the floor rather than the fill. When European regulators intervened in retail contracts for difference, the measures included a margin close out rule and negative balance protection, both applied per account, alongside leverage caps. The same ESMA announcement recorded that between 74 and 89 percent of retail accounts lost money on these products. Negative balance protection bounds the worst case at the account. It does not mean your stop filled where you wanted.

    What to do about it without pretending you can control it

    You cannot control the fill. You can control four things around it, and all four are decisions made before the market is moving.

    The first is to stop treating 1R as a ceiling and start treating it as an estimate. If your sizing only survives when every loss is exactly the planned size, it is not sizing, it is a hope.

    The second is to measure your own fills instead of assuming them. Every platform shows the price you asked for and the price you received. Two columns in whatever record you already keep will tell you more about your real cost of trading than any general article can, including this one. If you do not have that record yet, how to track my trades covers what is worth writing down.

    The third is to know which sessions you are asking your stop to work in. Holding through a scheduled release means holding through the part of the day where the distance is widest, which is the subject of how to trade gold through high impact news. That is not an instruction to avoid news, it is an instruction to know the trade you are making.

    The fourth is to choose the level before the market is in front of you, so that when the fill arrives past it you are dealing only with the distance and not also with the decision. Where to place a stop loss on XAUUSD deals with that half.

    None of this makes the fill better. It makes the account able to absorb a fill that is worse than planned, which is the only version of this problem that has a solution.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting your account through the kind of fast market this article describes. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently asked questions

    What happens if a market order is not filled at all?
    Outright rejection is uncommon and has specific causes: not enough free margin, the instrument not currently trading, or a platform level refusal during fast conditions. In each case no position is created, which matters most when the order was meant to close a trade rather than open one. Check the order status rather than assuming, because a rejected closing order leaves you exposed while you believe you are flat.

    Is a fill away from my price the same thing as my broker cheating me?
    Usually no. A market order is defined as accepting whatever price is obtainable, so a fill away from your screen price is the order working as specified. What would be worth investigating is a pattern that only ever runs one way across many trades in ordinary conditions. Without your own record you have no way to tell an ordinary cost from an unusual one.

    Does a stop loss guarantee my maximum loss?
    No, and this is the single most expensive misunderstanding in retail trading. A stop becomes a market order when touched, so it fixes the moment of exit, not the price of exit. The loss can be larger than planned, and it is largest in exactly the fast conditions that triggered it. Size on the assumption that some losses will exceed the plan.

    How is this different from a limit order not filling?
    Completely different, and in your favour. A limit order that does not fill costs nothing at all, because there is no trade: no spread, no commission, no exposure, as covered in what happens if a limit order is not filled. A market order that fills badly has already cost you money. One is a missed opportunity, the other is a realised expense.

    What about an order that only partly fills?
    That is a third case again, with its own consequences for the risk you are actually carrying, and what happens if an order is partially filled works through it. The short version is that a partial fill quietly changes your position size, so the risk you calculated is no longer the risk you have.

    Would a stop limit order solve this?
    It solves the price problem by creating a worse one. A stop limit will not fill beyond the limit you set, which sounds like protection until the market moves past your band without trading inside it. Then the order does nothing and you still hold the position. You are choosing between a bounded exit at an uncertain price and an uncertain exit at a bounded price.

    Where did the numbers in this article come from?
    The two definitions are quoted from the CFTC glossary, linked above. The movement statistics are my own arithmetic on the LBMA afternoon gold auction in US dollars, also linked, using every observation from 1 January 1975 to 24 September 2026, which is 12,979 daily changes. Movement is measured as the absolute logarithmic change between consecutive auctions, then summed. The stated limitation is that one auction price per day cannot see what happened inside the day, so these figures describe the shape of the distribution rather than the size of any individual fill. The R arithmetic is straightforward division under the single stated assumption that winners pay two planned risks. No gold price level appears anywhere in this article.

    Where Gold Empire fits

    Gold Empire is free to follow. Daily gold analysis with the reasoning written out, losing days included, plus an optional Kit for people who want the method in one place. There is no promise of profit here, because nobody honest can make one.

    Knowing that your protective order is an estimate rather than a guarantee is a sizing question before it is anything else, which is why this sits under risk management in gold trading. If you are still setting the account up, how to open a gold trading account covers the ground before any of this applies, and you can read more about who writes this on the about page.

    About the author

    Matthew has spent a long time around gold, most of it learning things the slow way, and now writes them down so other people can learn them the fast way. He would rather explain the mechanism that quietly widens a loss than the setup that fills a timeline, because the first one is what decides whether an account is still here next year. Nothing in this article is personal advice, and no entry, stop or target discussed should be treated as a signal.


    This article is educational content about order types and execution mechanics. It is not investment advice, not a recommendation of any broker, platform or order strategy, and not a solicitation to trade. The order definitions are quoted from the public glossary of the CFTC. The price series is the daily gold benchmark published by the LBMA, and every statistic drawn from it is my own arithmetic under the assumptions written out above, including the limitation that a single daily auction price cannot observe intraday execution. Historical frequencies describe what has already happened and are not a forecast of what any future order will do. Order handling, rejection rules, requote policy and margin treatment differ between venues, so check your own platform’s documentation and client agreement rather than relying on a general description. Trading carries risk of loss.


  • Best Forex Telegram Channel for Forex Signals: How to Judge One Before You Trust It

    Best Forex Telegram Channel for Forex Signals: How to Judge One Before You Trust It

    Search for the best forex telegram channel for forex signals and you will get lists. Ranked lists, “top ten” lists, lists with star ratings and affiliate links underneath them. What you will almost never get is the one thing that would actually help you, which is a method for telling a good channel from a lucky one using nothing but arithmetic you can do yourself.

    That is what this article is. I run a channel, so read everything below with that in mind, and then apply the same test to mine. If it does not survive the test, you should not follow it either. That is the only honest way I know to write this piece.

    Why the Usual Way of Picking the Best Forex Telegram Channel for Forex Signals Fails

    Here is the normal process. Someone joins three or four channels, watches them for a fortnight, notices that one of them called several moves correctly, and stays with that one. It feels like evidence. It feels like due diligence, even, because you watched rather than just believing a screenshot.

    The problem is that a fortnight of correct calls is exactly what luck looks like. Not sometimes. Routinely. And the arithmetic that shows this is simple enough to do in your head once you have seen it done once.

    Take a channel with no skill at all. Not a fraud, just someone with no genuine edge, whose calls are effectively coin flips at one to one risk and reward. Ask how often that channel finishes a run of signals looking impressive.

    • Over 20 signals, a pure coin flipper finishes at 60 per cent winners or better 25.17 per cent of the time.
    • Over 50 signals, 10.13 per cent of the time.
    • Over 100 signals, 2.84 per cent of the time.
    • Over 250 signals, 0.09 per cent of the time.

    Those are exact binomial probabilities, not estimates from a simulation. One in four channels with zero skill will show you a 60 per cent hit rate over twenty calls. If you are comparing four channels over a fortnight, you should expect one of them to look good. The impressive one is not the outlier. It is the arithmetic working normally.

    Chart for choosing the best forex telegram channel for forex signals, showing how often a channel with no skill at all still finishes above sixty per cent winners across twenty, fifty, one hundred and two hundred and fifty signals
    Choosing the best forex telegram channel for forex signals from a short record is guesswork: a channel with no skill whatsoever clears 60 per cent winners a quarter of the time over twenty signals.

    The Streak Screenshot, Explained

    The other thing you will be shown is a streak. Eight winners in a row, twelve winners in a row, posted as a screenshot with the losses cropped out.

    Run the same arithmetic. In 50 coin flips, the chance of at least one run of eight consecutive winners somewhere in there is 8.36 per cent. In 100 flips it is 17.02 per cent. In 250 flips it is 38.40 per cent. So a channel that has been posting for a year, with no skill at all, is more likely than not to have produced at least one eight winner streak it can screenshot forever.

    This is the part I want you to take away even if you remember nothing else. A streak is not evidence of skill, because a long enough record produces streaks by accident. The only thing a streak proves is that the channel has been posting for a while.

    How Much Evidence Would Actually Be Enough

    Turn the question around. Suppose a channel genuinely does win 60 per cent of the time. How many signals do you need to see before that result separates itself from luck?

    Working it the other way, at a one sided five per cent threshold, you need 62 signals. At that point a channel showing 38 wins out of 62 has produced something a coin flipper manages only 4.90 per cent of the time. Below 62 signals, you genuinely cannot tell the difference, and no amount of confidence in the presentation changes that.

    Sixty two is the floor, and it assumes the record is complete. It assumes nothing was deleted. In practice, a deleted losing call is worth far more than a posted winning one, because it corrupts the entire sample. So the real requirement is sixty plus signals in a record you have reason to believe is complete, which is a much harder thing to find.

    The Four Questions That Actually Separate Channels

    Since the track record is mostly unreadable, judge the process instead. These are the four things I would check, in order.

    One. Is the reasoning posted before the outcome, or after it? This is the single most informative signal available to you, and it costs nothing to check. Scroll back six months. Does each call state a reason at the time it was made, or do explanations only appear once the market has moved? Hindsight commentary is free to produce and worth nothing. A channel that commits to a reason in advance is making itself falsifiable, which is the entire game.

    Two. Are the losses still there? Scroll for losing days specifically. If you cannot find any, that is not a good channel, it is an edited one. Every genuine record has bad weeks in it. A channel that posts its worst month is telling you something a channel that posts its best month never can.

    Three. Is there a number attached to the risk? Look at whether calls mention position size, invalidation, or what happens when the idea is wrong. A channel that only ever posts direction is not giving you a trade, it is giving you an opinion with a ticker attached. The thing that decides whether your account survives is not the direction, it is how much you had on, which is the whole reason I keep pointing people back to how much to risk per trade before anything else.

    Four. What is the business model? Somebody is paying for the channel to exist. If it is you, through a subscription, then the incentive is to keep you subscribed, which rewards excitement. If it is a broker, through a referral fee per lot you trade, then the incentive is volume, which rewards overtrading. Neither is automatically disqualifying, but you are entitled to know which one you are in, and a channel that will not say is answering the question anyway.

    The Regulatory Numbers Nobody Puts in the Ranked Lists

    Two published figures put the rest of this in context, and both come from public bodies rather than from anyone selling anything.

    The first is the scale of the loss. The FBI’s Internet Crime Complaint Center publishes an annual report, and its 2024 Internet Crime Report records 47,919 complaints in the investment category, with reported losses of 6,570,639,864 US dollars in that category alone, against 16.6 billion dollars of reported losses across all categories that year. Investment fraud is not a fringe risk in this space. It is the largest single category of reported loss in the report.

    The second is more useful still, because it tells you what the honest baseline looks like. When the European Securities and Markets Authority restricted contracts for difference sold to retail clients, one of the measures it imposed was a standardised risk warning, including the percentage of losses on a CFD provider’s retail investor accounts. The same package capped leverage on gold at 20 to 1 and required negative balance protection on a per account basis.

    Read that second one slowly. A regulator looked at this market and concluded that the single most useful thing a retail client could be told was what share of accounts lose money. Not which strategy works. Not which channel is best. What share of accounts lose money. If a signal channel has never once mentioned that most retail accounts lose money, it is presenting a version of this business that a regulator specifically legislated against.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one page guide to protecting an account before you follow anyone’s analysis, including the questions worth asking of any channel you join. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    The Mistake That Costs More Than Picking Wrong

    Here is the thing I have seen do the most damage, and it has nothing to do with which channel someone picked.

    People size their positions based on how much they trust the source. A call from a channel they rate highly gets three times the risk of a call from a channel they are still evaluating. It feels rational. It is the single fastest way I know to turn an ordinary losing streak into a closed account, because the losing streak arrives regardless of how good the analysis was, and it arrives exactly when confidence is highest, which is after the run of winners that earned the trust in the first place.

    Position size is a decision about your account. It is not a vote of confidence in someone else’s analysis. Those are two different things and merging them is how people who followed perfectly reasonable channels still ended up blown out, which is the pattern behind why accounts keep getting blown up even when the analysis was fine.

    The right structure is boring. Decide your risk per trade before you open Telegram. Apply it identically to every idea regardless of who posted it. Let the source affect whether you take the trade, never how much you put on it.

    What a Channel Can Honestly Offer You

    Nobody can hand you a shortcut past your own decision making, and any channel implying otherwise is selling something. What a channel can genuinely do is narrower and more useful than that.

    It can show you a process being applied consistently, so you can learn the shape of it. It can point out context you would have missed, like a data release you had not checked. It can give you a second opinion that is not your own anxiety talking. And it can model what it looks like to sit out, which is the hardest habit in this business to learn alone.

    What it cannot do is make a bad position size safe, and it cannot make you a trader by proxy. The account is yours. The decision is yours. That does not change no matter how good the analysis is.

    Frequently Asked Questions

    How do I find the best forex telegram channel for forex signals?
    Judge process, not results. Check four things: whether the reasoning is posted before the outcome, whether losing calls are still visible in the history, whether risk and invalidation are stated alongside direction, and how the channel makes money. A short run of correct calls tells you almost nothing, because a channel with no skill at all clears 60 per cent winners a quarter of the time over twenty signals.

    How many signals do I need to see before I can judge a channel?
    At least 62, and only if you believe the record is complete. Below that number, a genuine 60 per cent hit rate cannot be separated from luck at a one sided five per cent threshold. Most people decide after ten or twenty, which is well inside the range where coin flips look like skill.

    A channel showed me eight winners in a row. Is that good?
    It is unremarkable. In 100 coin flips the chance of at least one run of eight consecutive winners is 17.02 per cent, and in 250 flips it is 38.40 per cent. Any channel that has been posting for a year has probably produced one by accident. Ask to see the month either side of the streak instead.

    Are paid signal channels better than free ones?
    Price tells you about the business model, not the quality. A subscription means the incentive is to keep you subscribed. A broker referral fee means the incentive is the volume you trade. Free with no funnel at all usually means the channel is marketing for something else. None of these is disqualifying, but you should know which one applies before you join, and be wary of any model that pays more when you trade more.

    Where did the probabilities in this article come from?
    Exact binomial arithmetic, computed rather than estimated, on the stated assumption that a channel with no edge produces independent signals that win half the time at one to one risk and reward. The streak figures come from an exact dynamic programming calculation over the same assumption. Anyone can reproduce all of them. They are properties of coin flips, not claims about any particular channel.

    Where Gold Empire Fits

    Gold Empire is free to follow, and I would rather you applied the test above to it than took my word for anything. Daily XAU/USD analysis goes out on Telegram with the reasoning stated before the trade rather than after it, and the losing days stay up. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the whole method. Nothing here promises a profit, and nothing here is a signal service in the sense that phrase usually means.

    If you are working through this properly, the pillar underneath all of it is risk management for gold trading. The companion piece on whether these groups are legitimate at all is are forex signal groups legit, and the practical mechanics of using one without handing over your judgement are in how to get signals for forex trading.

    Looking for the best forex telegram channel for forex signals is a reasonable thing to do. Just do it with arithmetic rather than with screenshots, and remember that the number which decides your outcome is the one you choose, not the one someone else posts.

    About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He has been keeping a count of his own losing calls for long enough to know exactly how ordinary a good fortnight is. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about evaluating information sources and about probability. It is not financial advice, not investment advice and not a recommendation to buy, sell or hold any instrument or product, nor an endorsement of any channel or provider. Trading gold and leveraged products carries a substantial risk of loss and is not suitable for everyone. Most retail accounts lose money. Past results of any source do not guarantee future results. Only risk capital you can afford to lose, and seek independent advice if you are unsure.


  • How to See Gold Chart in TradingView, and Which Gold It Shows

    How to See Gold Chart in TradingView, and Which Gold It Shows

    Most people asking how to see gold chart in TradingView want a two minute answer, and there is one. Type XAUUSD into the symbol box, press enter, and a chart appears. Done. The trouble is that the chart which appears is one of several different gold charts the platform can show you, they do not all say the same thing, and almost nobody checks which one they landed on.

    That sounds pedantic until you realise what it costs. You size a position using the volatility you see on the screen, but you get filled on a feed that belongs to your broker, and if those two are not the same thing, your risk calculation was built on someone else’s data. So I want to cover the two minute answer properly, and then spend the rest of this on the part that actually protects an account.

    How to See Gold Chart in TradingView, Step by Step

    Open the platform and click the symbol box at the top left, where the current instrument name sits. Type gold, or XAUUSD, and wait for the dropdown to populate.

    Here is the first thing worth noticing. You will not get one result. You will get a list, and each entry has a small provider name attached to it on the right hand side. Some of those entries are spot gold quotes contributed by different liquidity providers. Some are futures contracts with expiry months attached. Some are contracts for difference offered by individual brokers. Some are gold priced in other currencies entirely.

    Pick one and the chart loads. To keep it, click the star to add it to a watchlist, then set the timeframe from the toolbar. That is the mechanical answer, and if that is all you came for, you now have a gold chart.

    But scroll that dropdown list again before you move on, because the length of it is the actual lesson. There is no single instrument called gold. There is a family of related instruments, and knowing which branch of that family you are looking at is the difference between analysis and guesswork.

    Chart supporting how to see gold chart in TradingView, showing how often the LBMA gold benchmark moved more than one, two and three per cent between sessions and across weekend gaps
    Once you know how to see gold chart in TradingView, the next question is what the chart does not draw: the weekend gap is the likeliest stretch of all to move more than one per cent.

    The Three Different Golds You Might Be Looking At

    Spot gold is a quote for metal for immediate settlement, traded over the counter between large institutions rather than on an exchange. When a platform shows XAUUSD without a broker name attached, it is usually an aggregate of contributed quotes. It has no expiry and no central order book, which means there is no single authoritative version of it. Two providers can show slightly different spot gold at the same instant and neither is wrong.

    Gold futures are exchange traded contracts for delivery at a set date. The US Commodity Futures Trading Commission’s weekly Commitments of Traders report for the COMEX division lists the benchmark gold contract under code 088691, and states its unit in capitals directly under the column headings: contracts of 100 troy ounces. A futures chart trades at a different level from spot because it carries the cost of holding metal to the delivery date, and that difference narrows as expiry approaches. A futures chart is not a spot chart with a different skin.

    Your broker’s CFD is a third thing again. It is priced off the first two, with your broker’s own spread applied, and possibly a financing charge for holding it overnight. This is almost certainly what you are actually trading, and it is the only one of the three that determines what price you get filled at.

    There is a fourth reference that is not a chart at all but is worth knowing about, because it is what the industry settles against. The London Bullion Market Association runs an auction that produces a published benchmark twice each trading day, and those LBMA precious metal prices are used for valuation and settlement worldwide. Two fixed prints per day, not a continuous line.

    Why the Chart You Choose Has to Match the Account You Trade

    This is the survival point, and it is simple enough to state in one sentence: analyse on the instrument you trade, or accept that your levels are approximations.

    If you mark a level on an aggregated spot chart and place an order on your broker’s CFD, the two are near each other but not identical. Most of the time the difference is small enough to ignore. The times it is not small are precisely the times it matters most, which is at the week’s open, around major data releases, and in thin liquidity, exactly when a stop is most likely to be tested.

    The practical fix takes one minute. If your broker publishes a feed on the platform, chart that. If it does not, chart the closest available and know that you are working with a proxy. Either way, place the order on your platform and look at the fill you actually received rather than the price you expected. Keeping a record of that difference is one of the cheapest habits in this business, and it is part of what I mean by tracking your trades properly.

    What the Chart Does Not Draw

    Here is the part that does not show up in any tutorial, and it is the reason for the chart above.

    A gold chart looks continuous. It is not. The market closes for the weekend, and during that closure the world keeps happening. To put a size on what that means, I took the LBMA Gold Price PM benchmark, which is a published reference rather than any broker’s feed, over the twelve months to 22 September 2026. There were 251 auction sessions in that period, and 250 session to session changes to measure.

    • The median absolute change between consecutive sessions was 1.00 per cent, and the mean was 1.29 per cent.
    • 125 of the 250 changes, exactly 50.0 per cent, exceeded 1 per cent.
    • 55 of them, 22.0 per cent, exceeded 2 per cent.
    • 14 of them, 5.6 per cent, exceeded 3 per cent. The largest single change was 7.83 per cent.

    Now isolate the weekend. I counted every pair of consecutive auctions three or more calendar days apart, which captures weekends and holiday closures. There were 53 of them. Their median absolute change was 1.14 per cent, slightly larger than an ordinary session, and 31 of the 53 exceeded 1 per cent, which is 58.5 per cent of them against 50.0 per cent for sessions generally. The largest weekend change was 5.36 per cent.

    Read that back. The stretch your chart draws nothing at all for is, on this evidence, marginally more likely to produce a move above 1 per cent than a normal trading day. The blank space is not quiet. It is unobserved, which is a very different thing, and it is why I keep coming back to what a weekend gap does whenever someone tells me their stop protects them at all times.

    These are percentage changes in a published benchmark. They are not a forecast, and no gold price appears anywhere in this article.

    Chart Settings That Reduce Mistakes

    A few small things, each of which has caused someone a bad morning.

    Set your timezone deliberately. TradingView defaults to a timezone that may not match your broker’s server, and gold trades in distinct session patterns. A daily candle that closes at a different hour than your broker’s is a different candle, with a different high and a different low, which means a different level.

    Check whether the symbol shows extended or continuous hours, especially on futures contracts, because a chart that hides part of the day will hide part of the range with it.

    Beware the continuous futures contract, usually written with a 1! suffix. It stitches successive contract months into one line, which is convenient for looking at long history and misleading for precise levels, because the join between two contracts is a step that no trade ever printed.

    Finally, and this is the boring one that matters most, put the instrument name somewhere you will actually see it. Screenshot a level from one chart, come back two hours later on a different symbol, and you have a level from an instrument you are not trading, which is how people end up defending a line that was never there.

    Free gold survival sheet

    Get the free Gold Empire survival sheet, a one-page guide to working out what a position actually exposes you to before you take it, including the gap you cannot see on the chart. One email, no spam, unsubscribe anytime.

    Get the free survival sheet →

    Frequently Asked Questions

    How do I see gold chart in TradingView in the fastest way?
    Click the symbol box at the top left, type XAUUSD, and choose from the dropdown. The chart loads immediately. The part worth an extra thirty seconds is checking the provider name next to the entry you picked, because the list contains spot quotes, futures contracts and individual brokers’ CFDs, and they do not all show identical prices.

    Which gold symbol should I actually use?
    The one closest to what you trade. If your broker publishes its own feed on the platform, use that, because it is the price you will be filled at. If not, an aggregated spot quote is a reasonable proxy, but treat your marked levels as approximate and confirm the fill on your own platform before drawing conclusions.

    Why does my TradingView gold chart differ from my broker’s?
    Because they are different instruments. Spot gold is an over the counter aggregate with no central order book, futures carry the cost of holding metal to a delivery date, and a broker CFD adds its own spread on top. Small differences are normal. They widen when liquidity is thin, which tends to be when it matters most.

    Is TradingView’s gold data good enough to trade from?
    For analysis, yes, provided you know which instrument you selected. For execution, your broker’s price is the only one that pays you. Treat the chart as the map and your platform as the road.

    Where did the numbers in this article come from?
    From the LBMA Gold Price PM benchmark series, linked above, over the twelve months to 22 September 2026: 251 auction sessions and 250 session to session changes. The percentages are counts of those changes exceeding each threshold, arithmetic anyone can repeat on the same public series. The weekend figures count the 53 pairs of consecutive auctions three or more calendar days apart. None of it is a forecast.

    Where Gold Empire Fits

    Gold Empire is free to follow. Daily XAU/USD analysis on Telegram, with the reasoning stated before the trade rather than after it, losing days included. There is a free survival sheet for anyone who wants the capital protection material in one place, and an optional Kit for people who want the whole method. Nothing here promises a profit, and nothing here is a signal service.

    The pillar this sits under is risk management for gold trading, the settings companion is best chart settings for TradingView, and if you are weighing up which platform to analyse on at all, TradingView vs MetaTrader covers that comparison.

    Knowing how to see gold chart in TradingView takes a minute. Knowing which gold you are looking at, and what the chart leaves out, is the part that keeps an account open.

    About the author. Matthew writes Gold Empire and spends most of his attention on the boring mechanics that decide whether an account is still open in two years. He has a long standing habit of checking which instrument a screenshot came from before arguing about the level on it, which has saved him more money than any indicator. Nothing in this article is a recommendation to trade, and no entry, stop or target discussed should be treated as a signal.


    Disclaimer: This article is general educational content about charting software and the differences between gold instruments. It is not financial advice, not investment advice and not a recommendation to buy, sell or hold any instrument or product. Trading gold and leveraged products carries a substantial risk of loss and is not suitable for everyone. Most retail accounts lose money. Past behaviour of any price series does not guarantee future results. Only risk capital you can afford to lose, and seek independent advice if you are unsure.